Listed by Jason LaFlesch, Results Realty · Financing by Mike Barnhart, Swift Mortgage
Gilbert, AZ 85298 · The Bridges at Gilbert
3743 E Strawberry Dr, Gilbert, AZ 85298
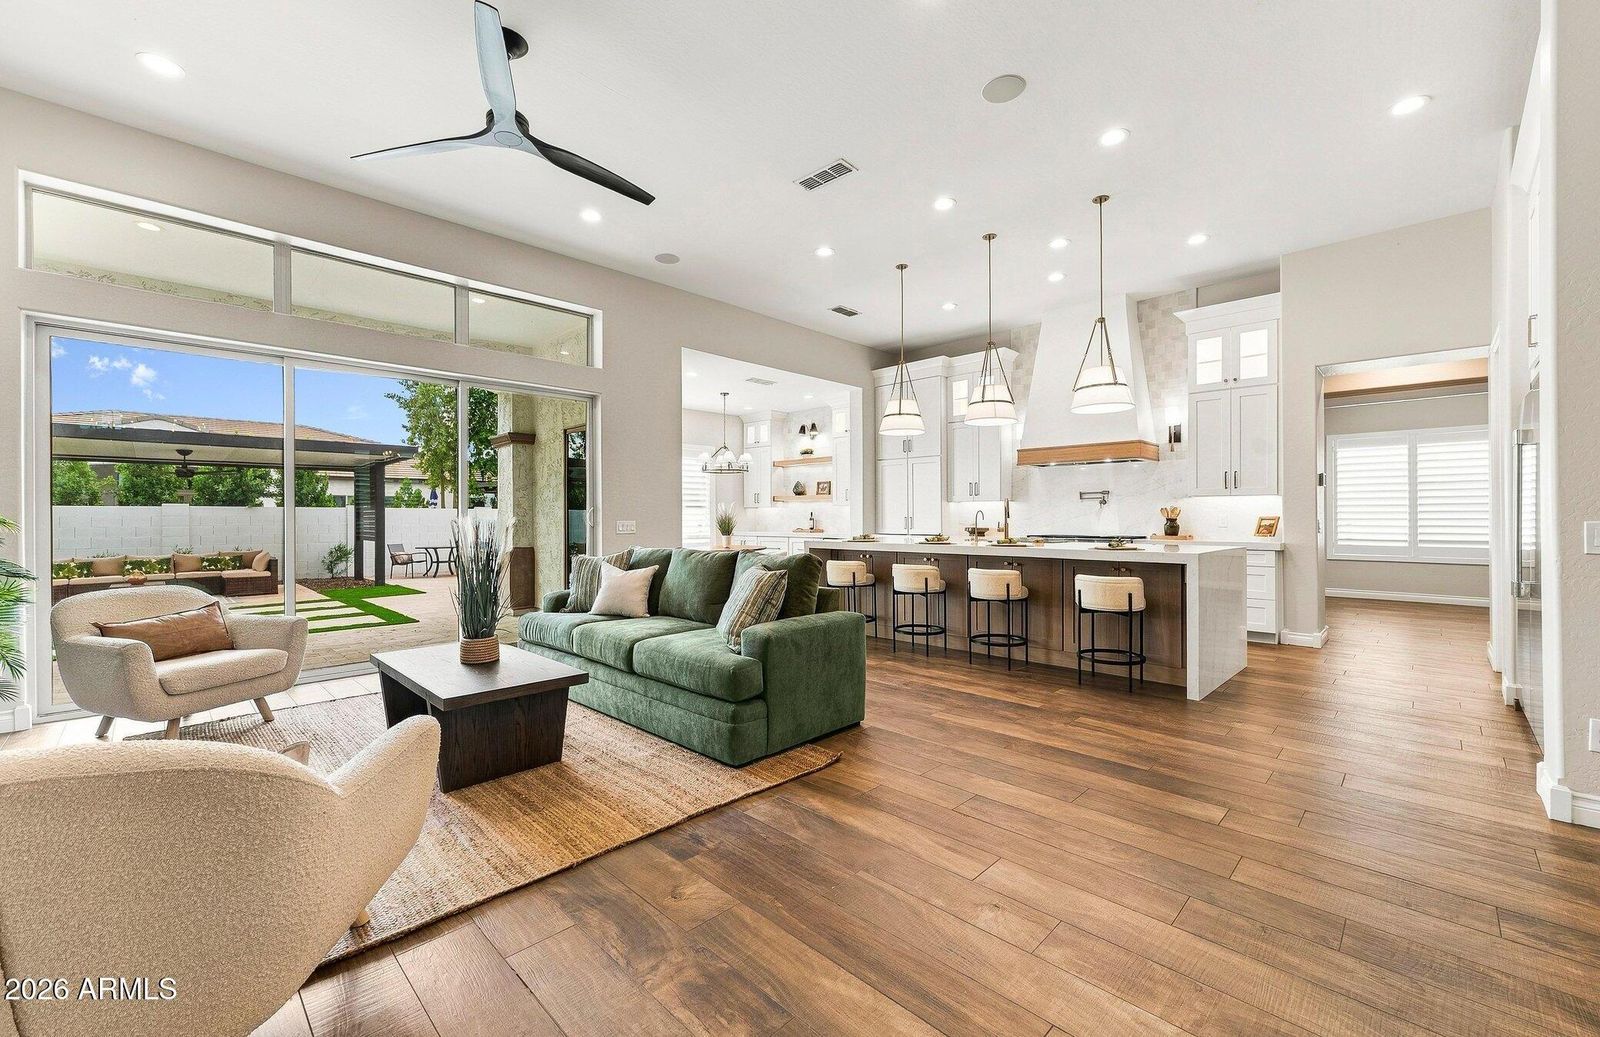
A completely remodeled single-story home in The Bridges at Gilbert, with a chef inspired kitchen, 12 foot ceilings, and a resort style backyard built around a heated pool and spa, now offered at $1,300,000. Structured with a 2% seller concession, an offer on this home can fund a 2-1 buydown that starts the buyer's payment over a thousand dollars lower for the first two years.
$1,300,000
5 bed3 bath3,465 sq ftSingle-storyPool + spa3-car garage2.00% concession · $26,000 · can fund a 2-1 buydown
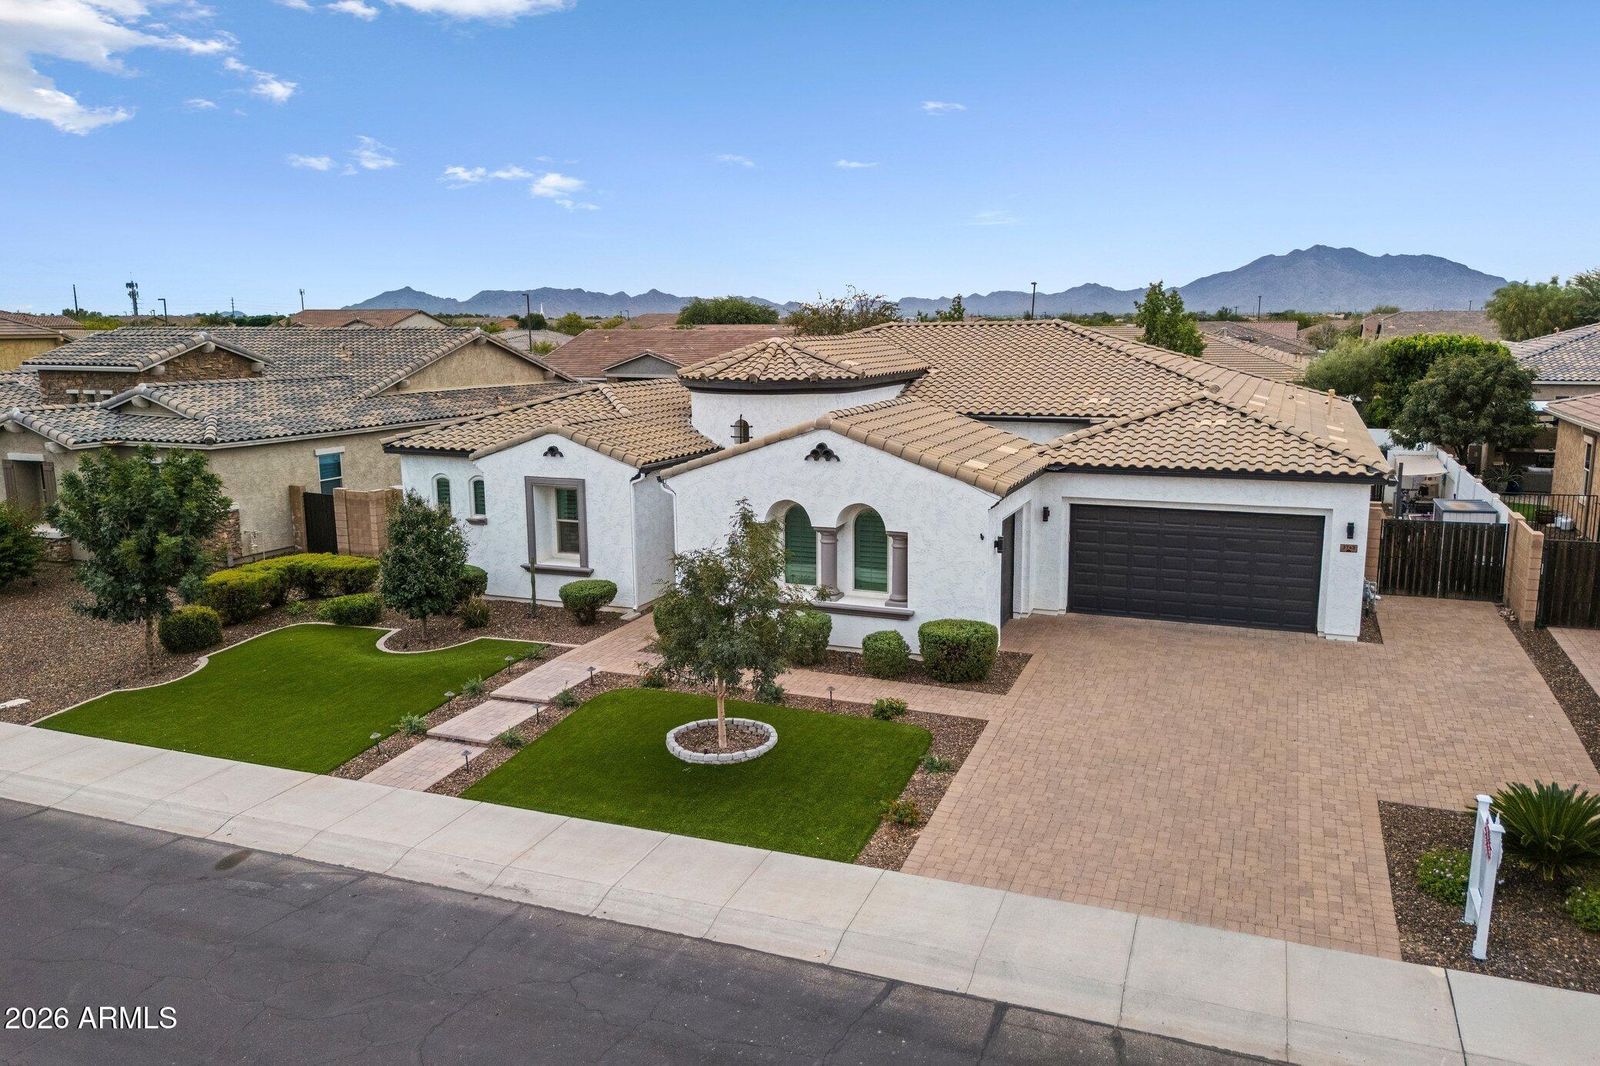
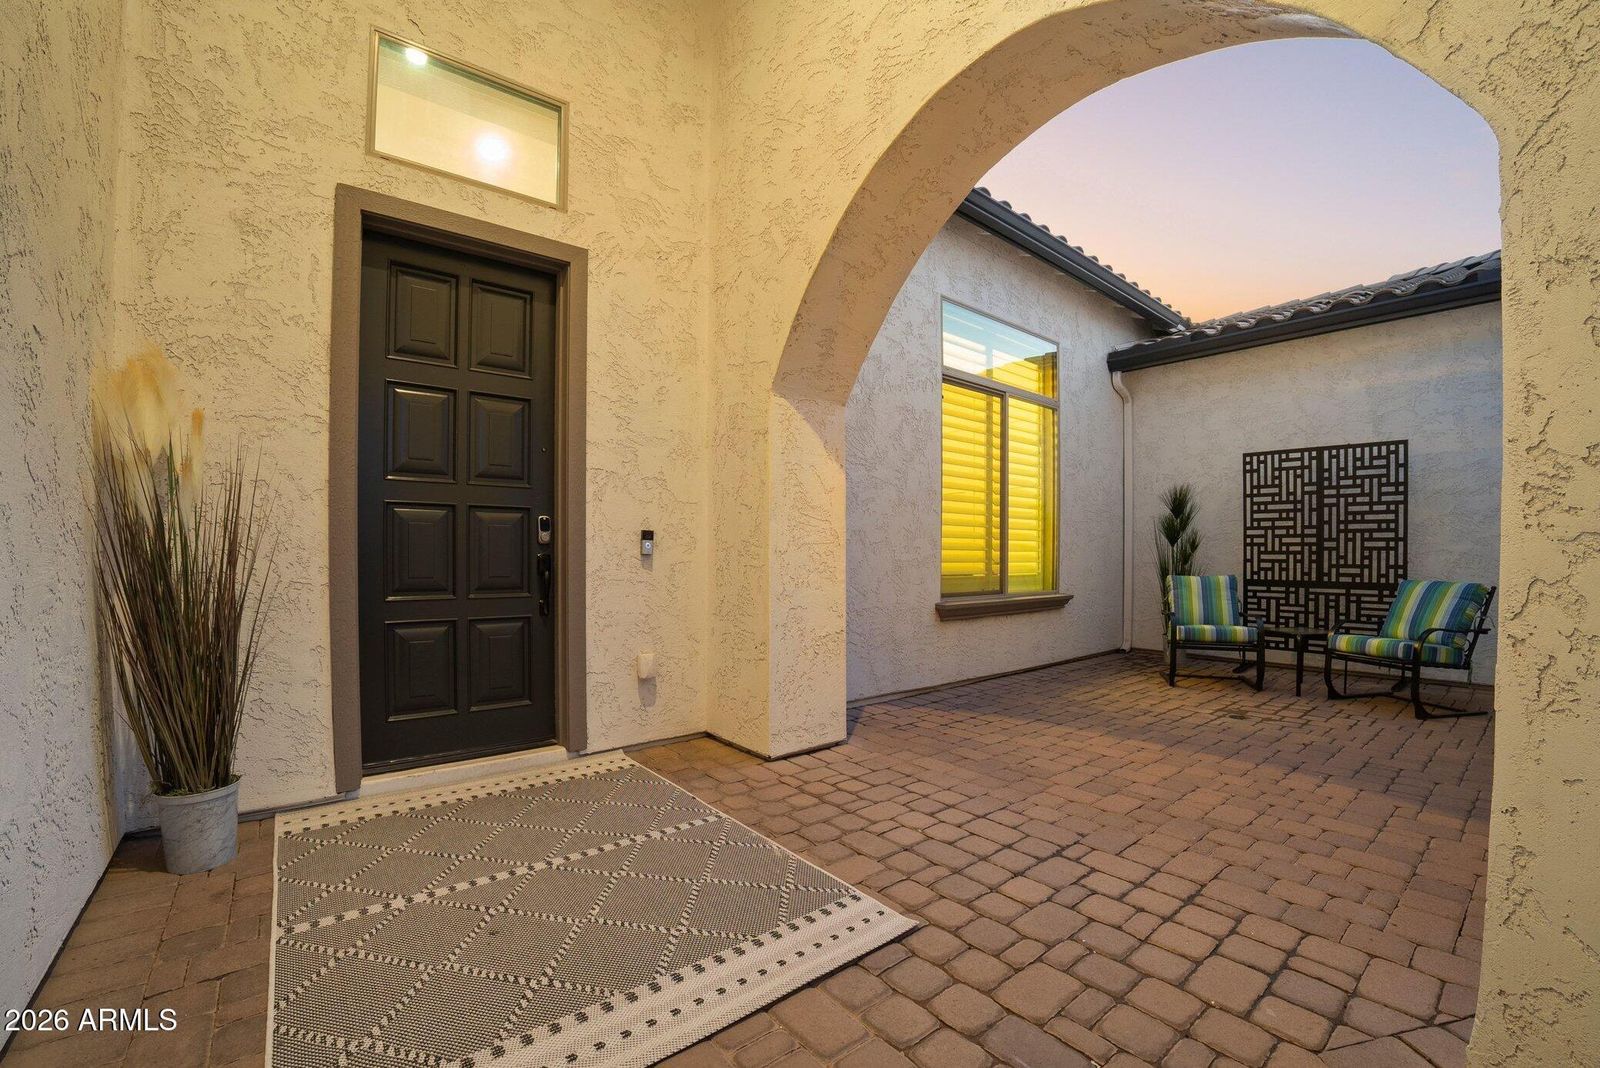
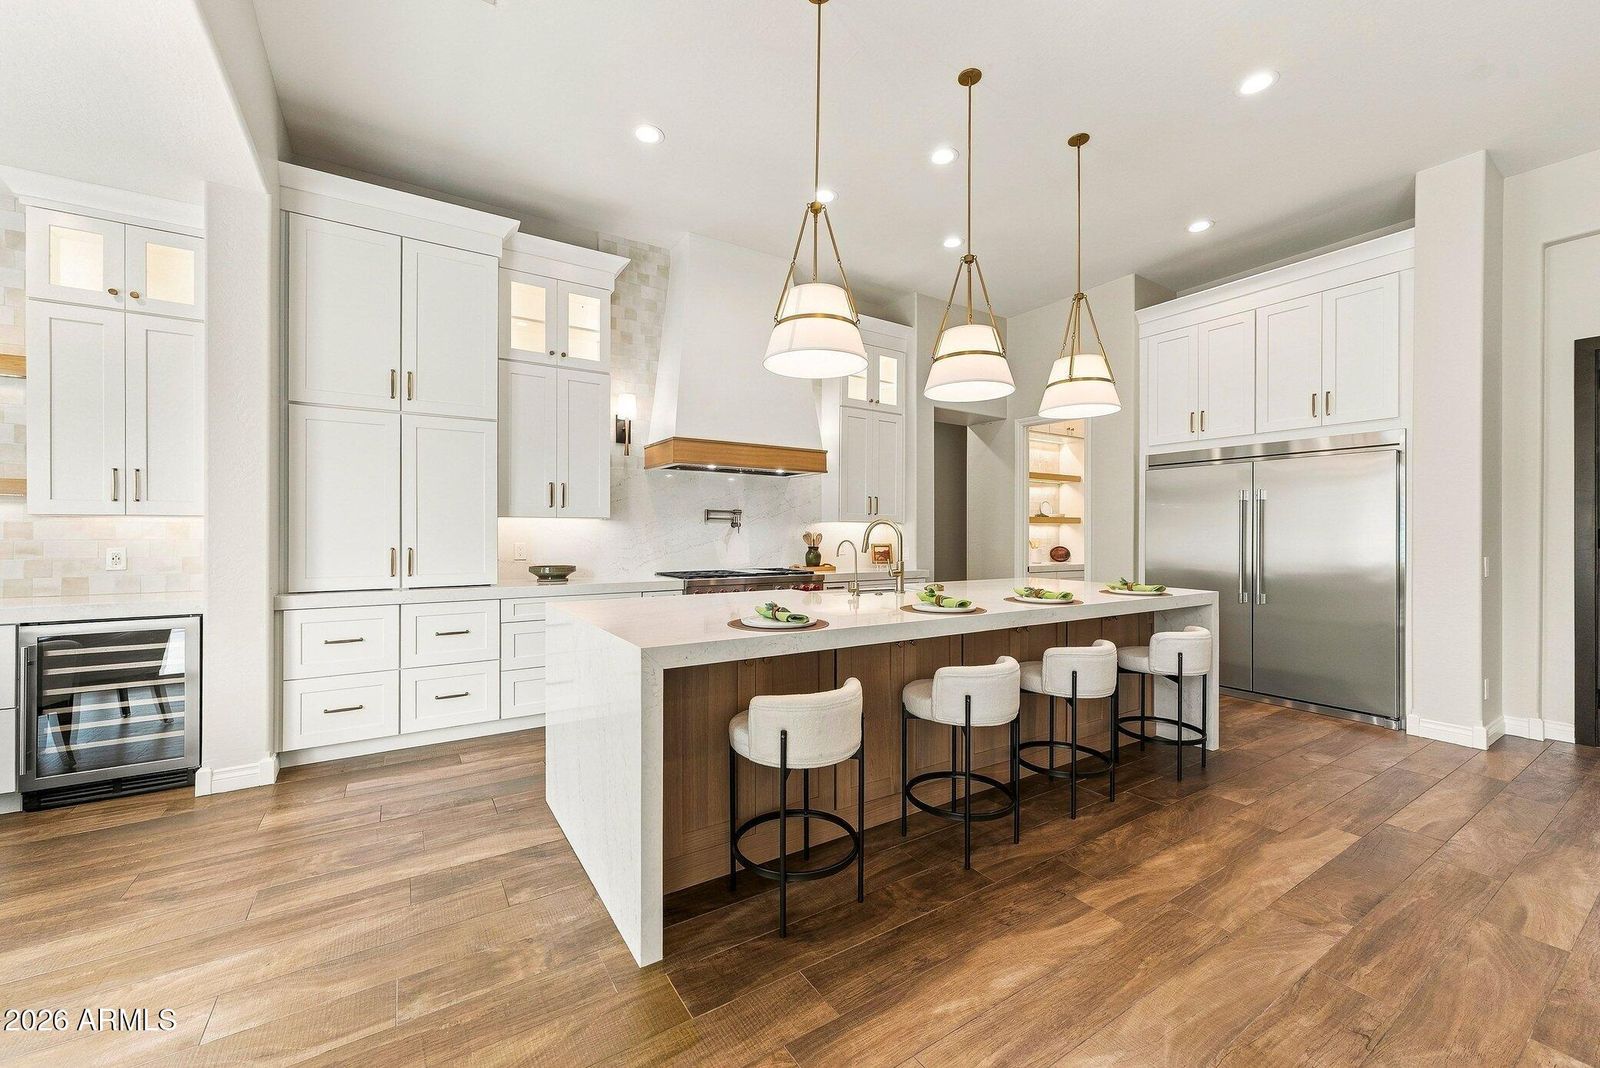
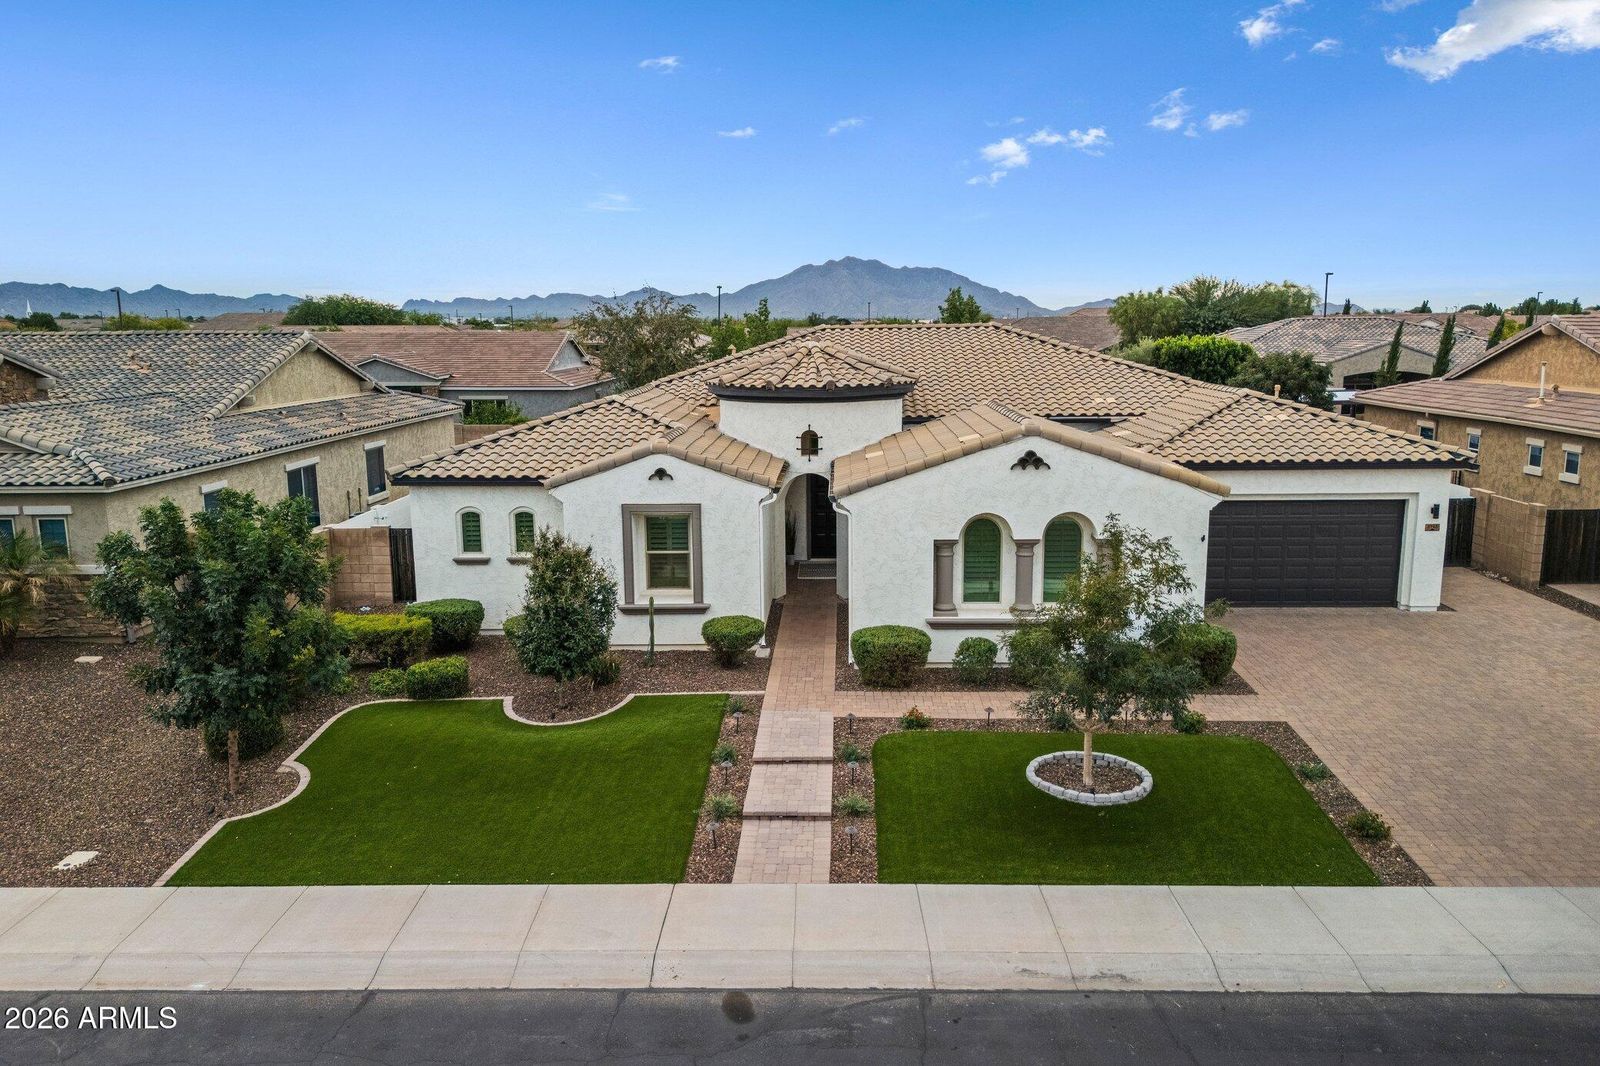
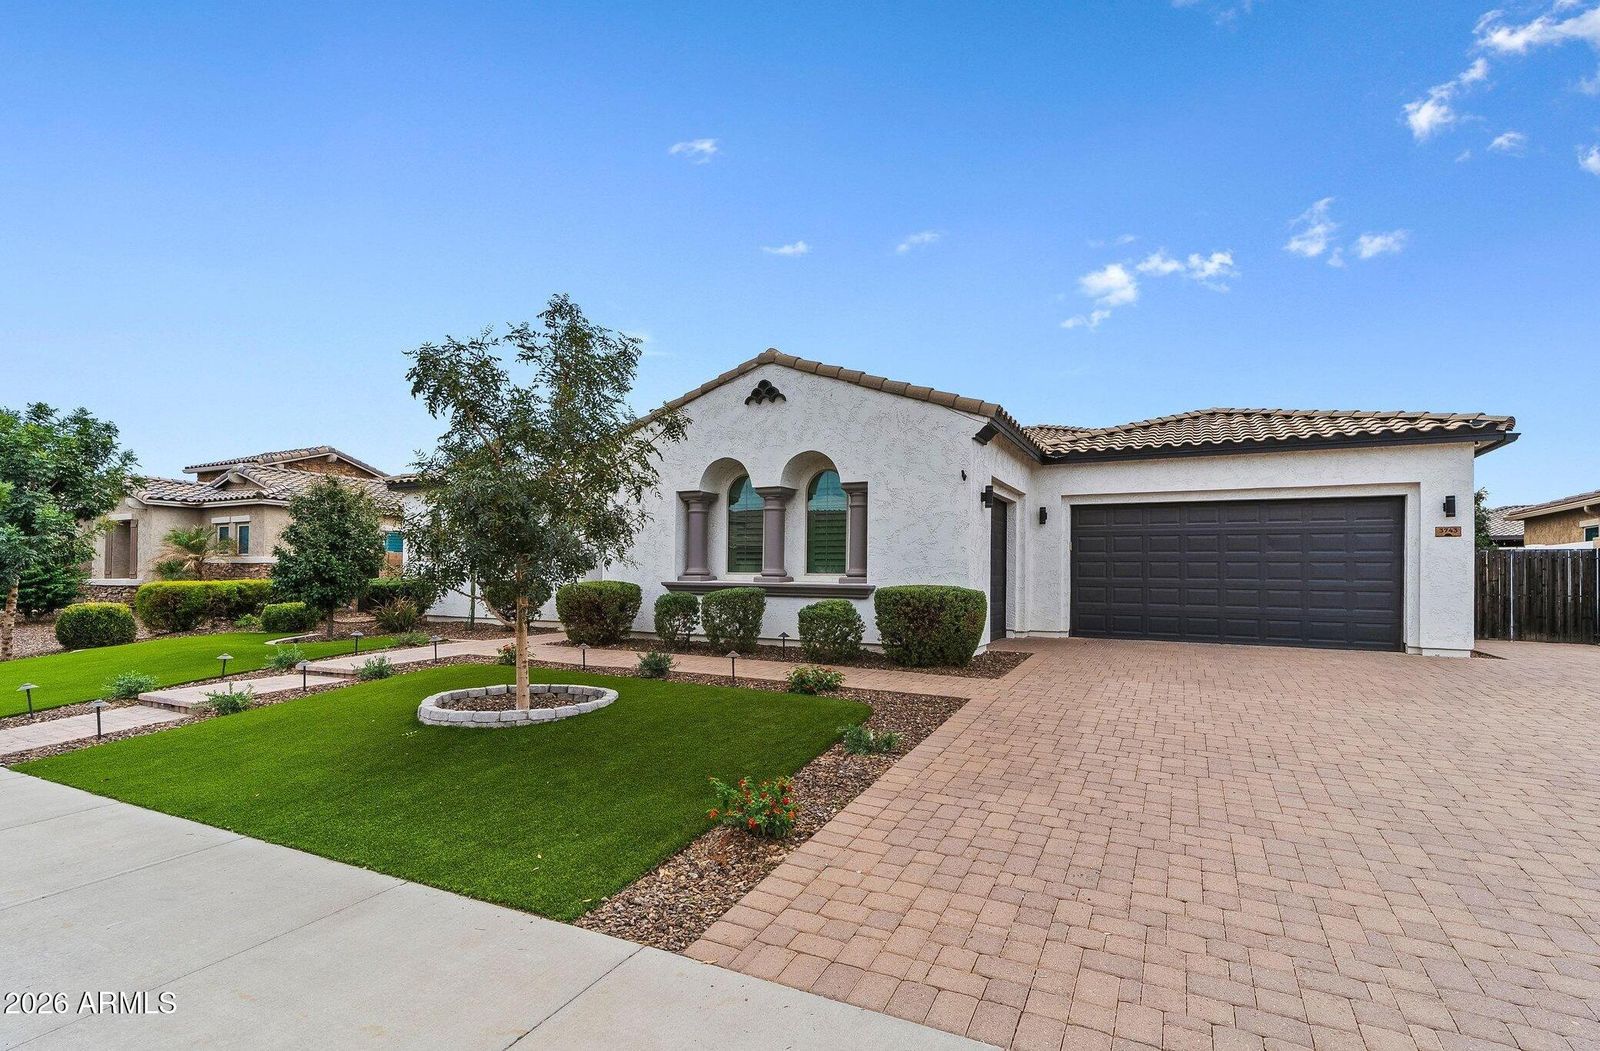
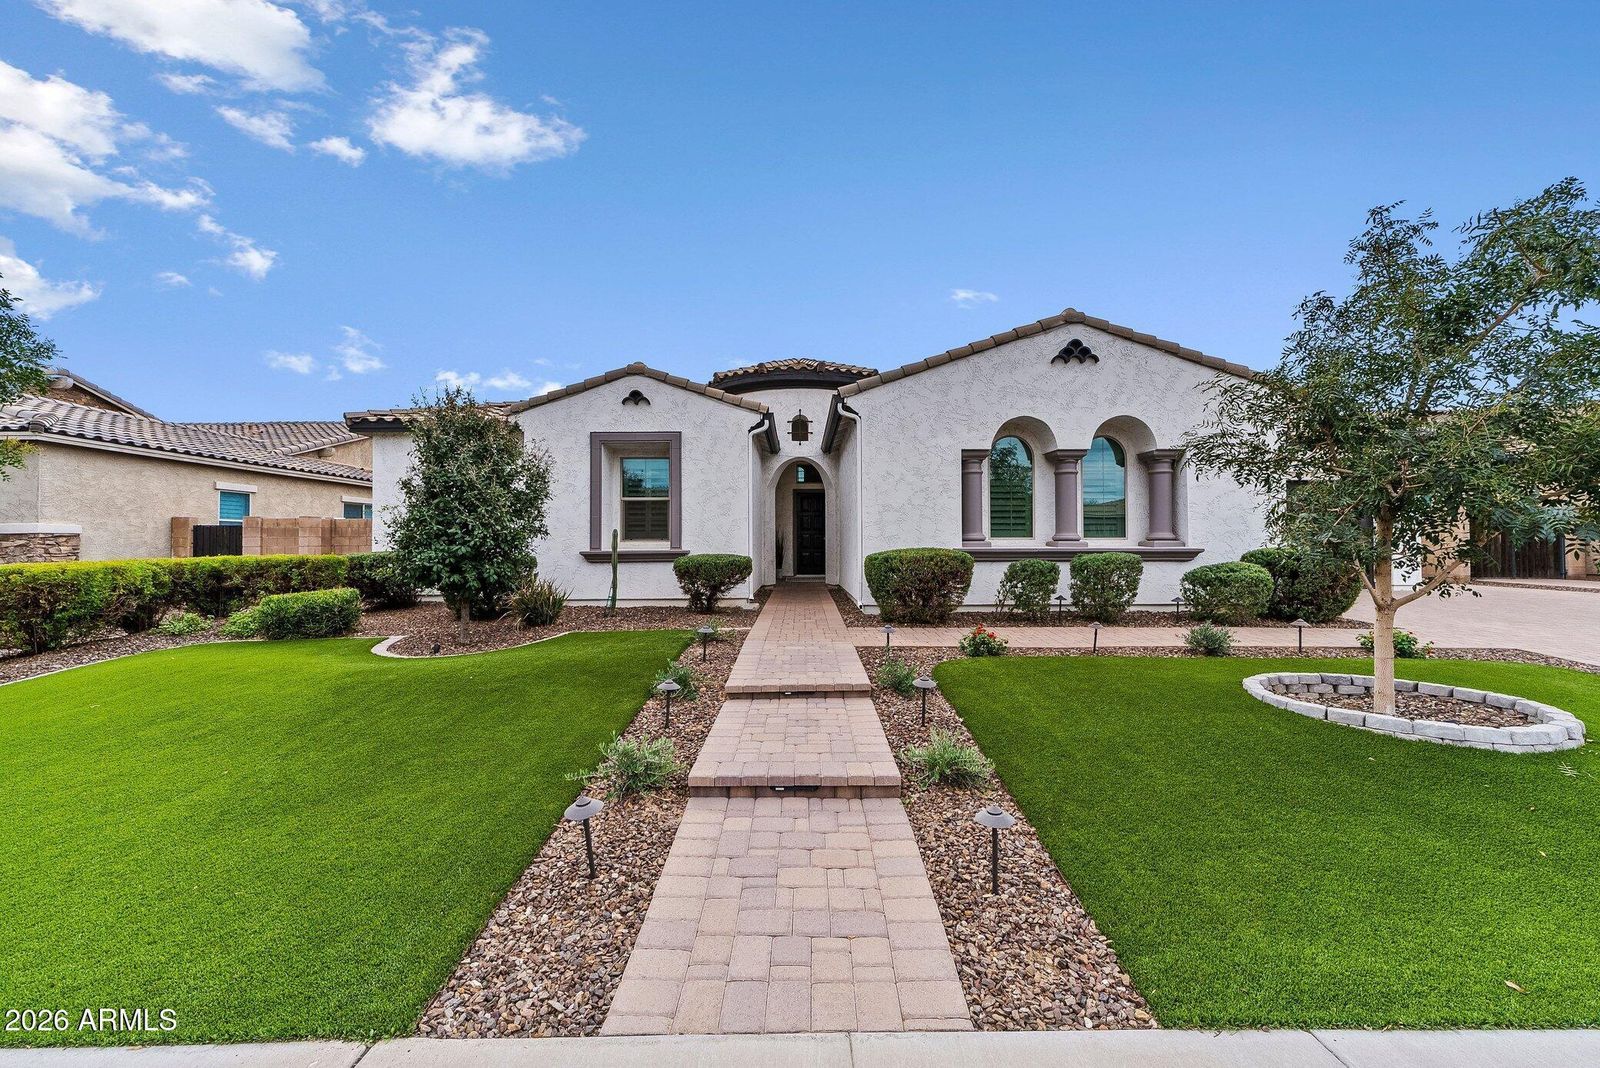
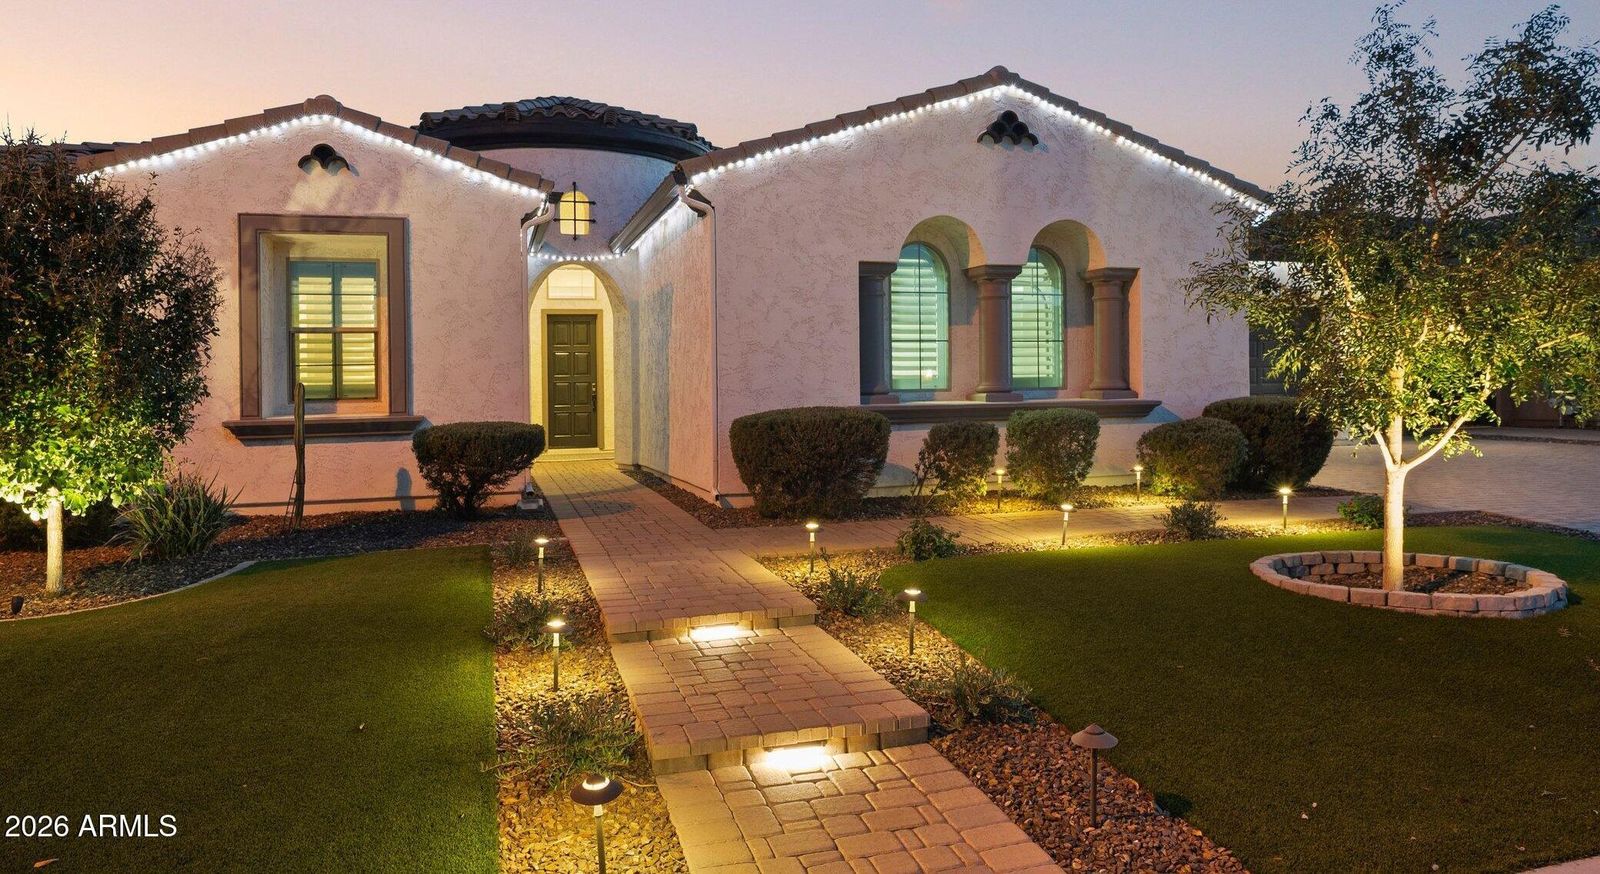
3743 E Strawberry Dr, Gilbert. Listing photo, ARMLS.
List price
$1,300,000
Listed November 19, 2026 with Results Realty, ARMLS #7106481.
The home
5 bd · 3 ba · 3,465 sf
Single-story home built in 2014 on a 0.27 acre homesite, completely remodeled, with a dedicated flex room, an enclosed office, and a split 3-car garage.
The financing angle
$26,000
A 2.00% seller concession written into an offer, enough to fund the 2-1 buydown featured below.
Photos of this home
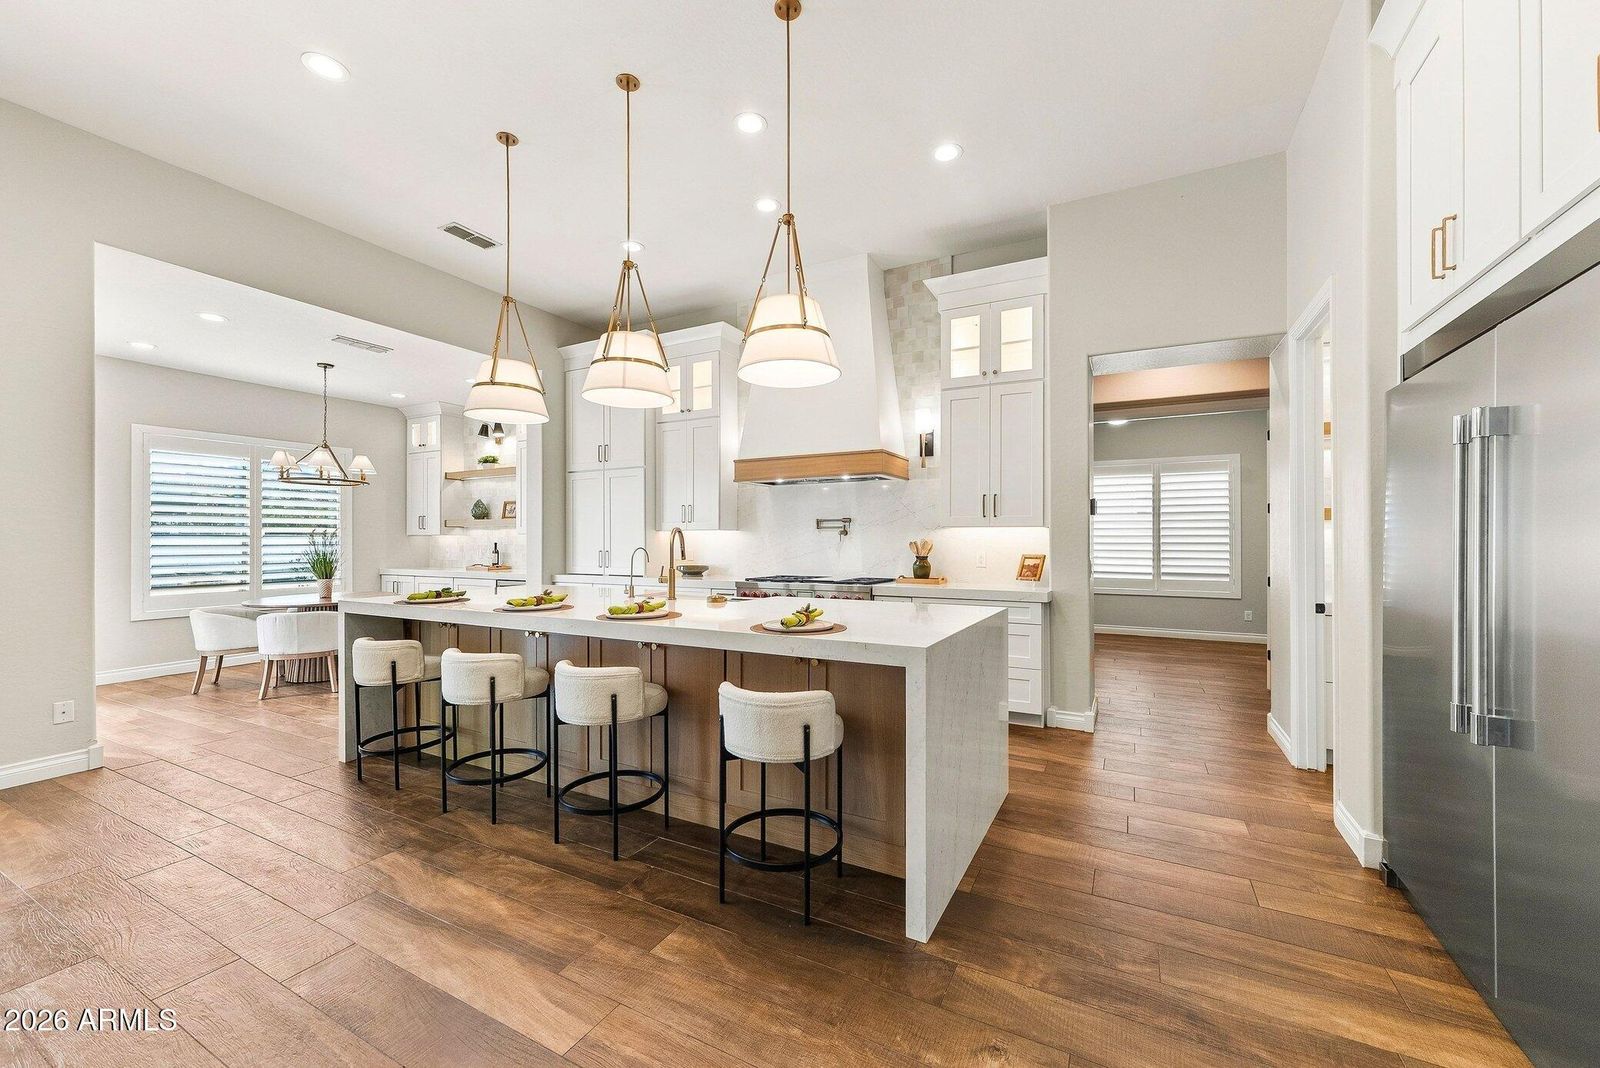
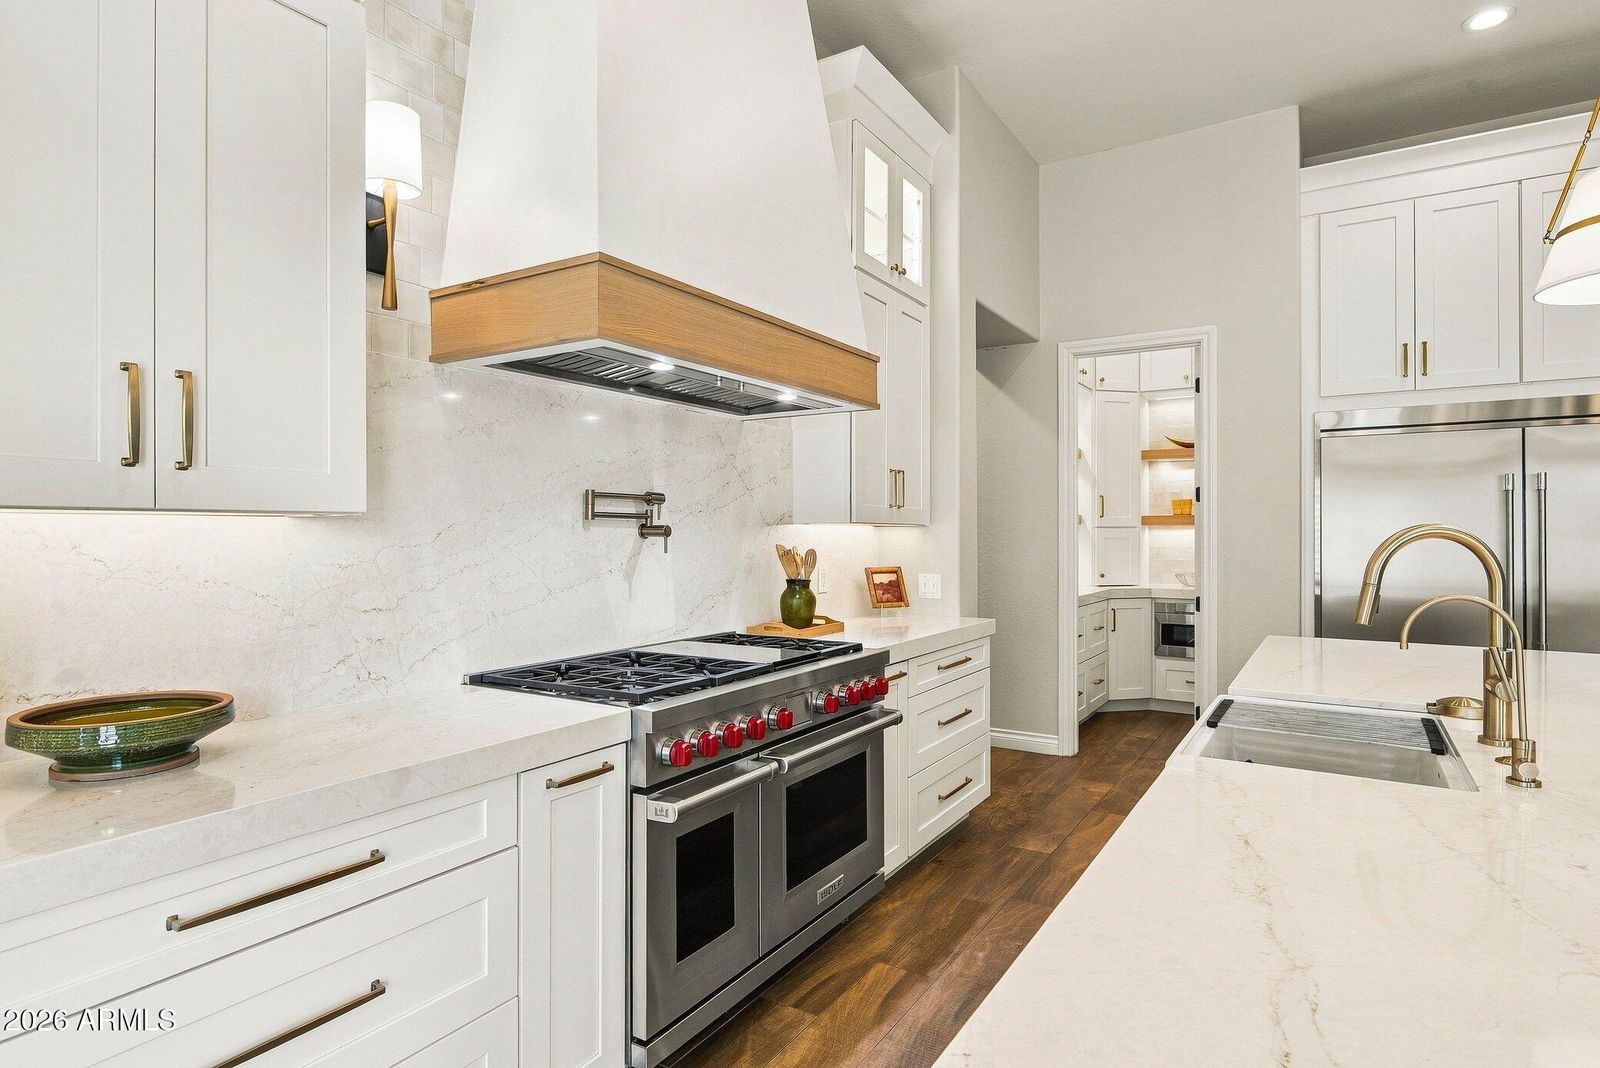
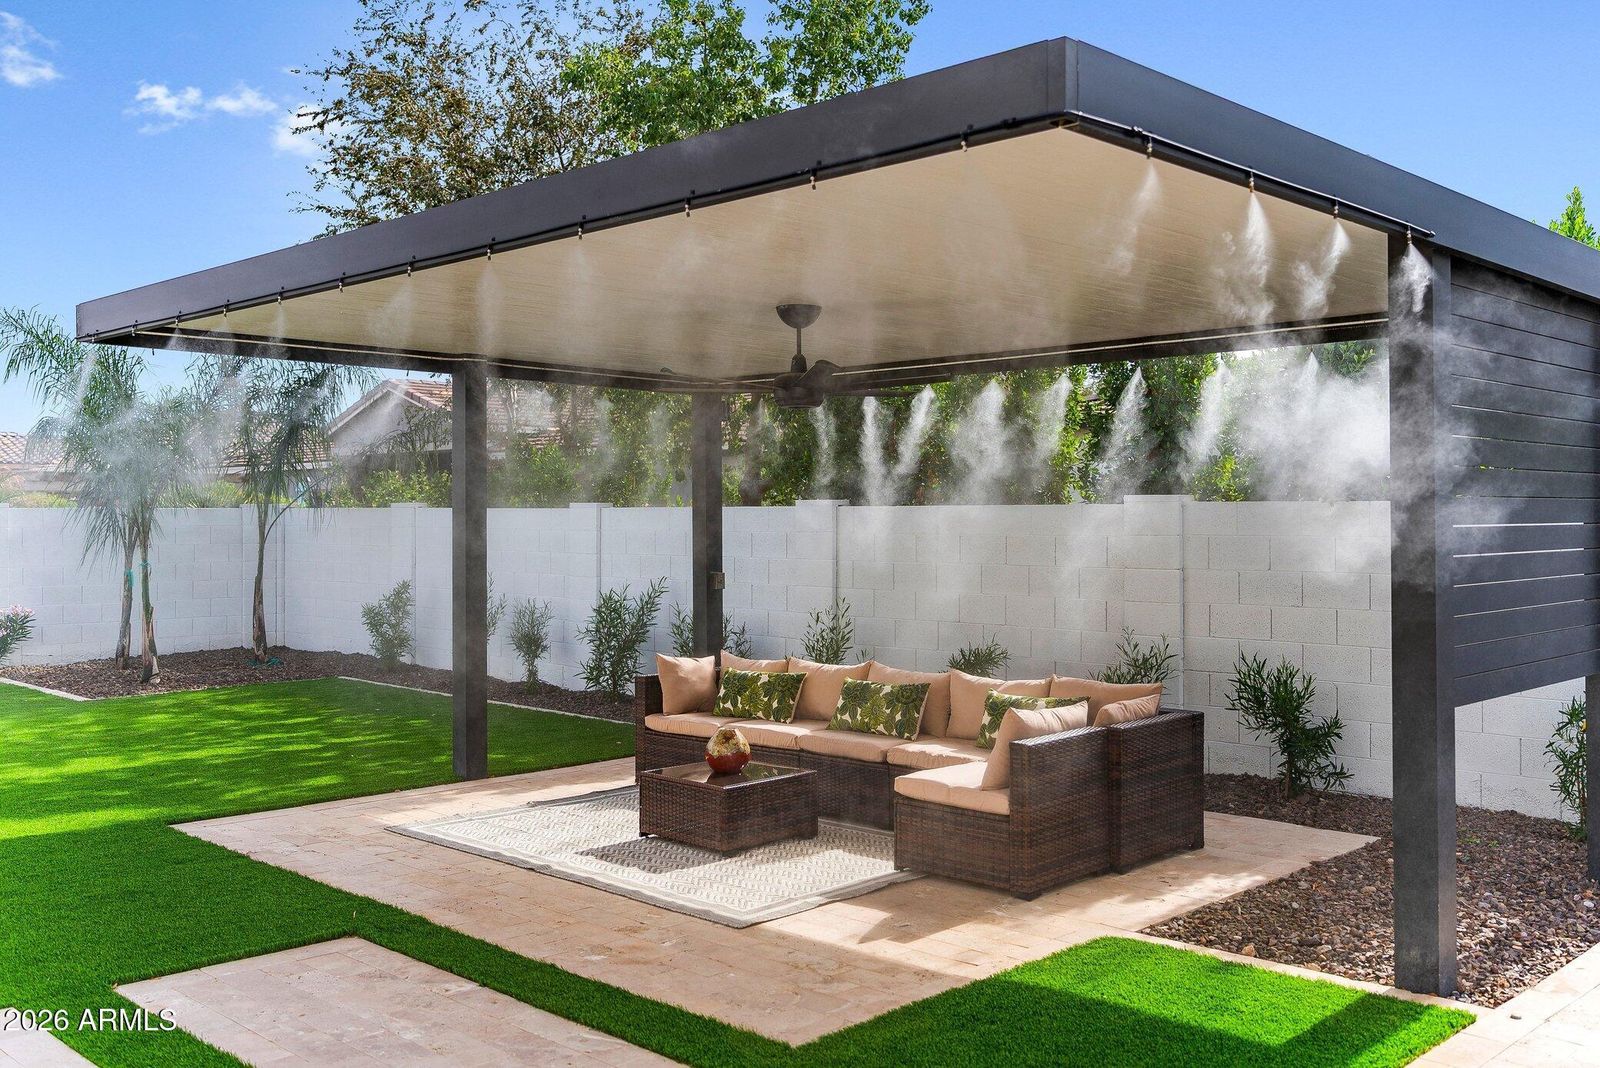
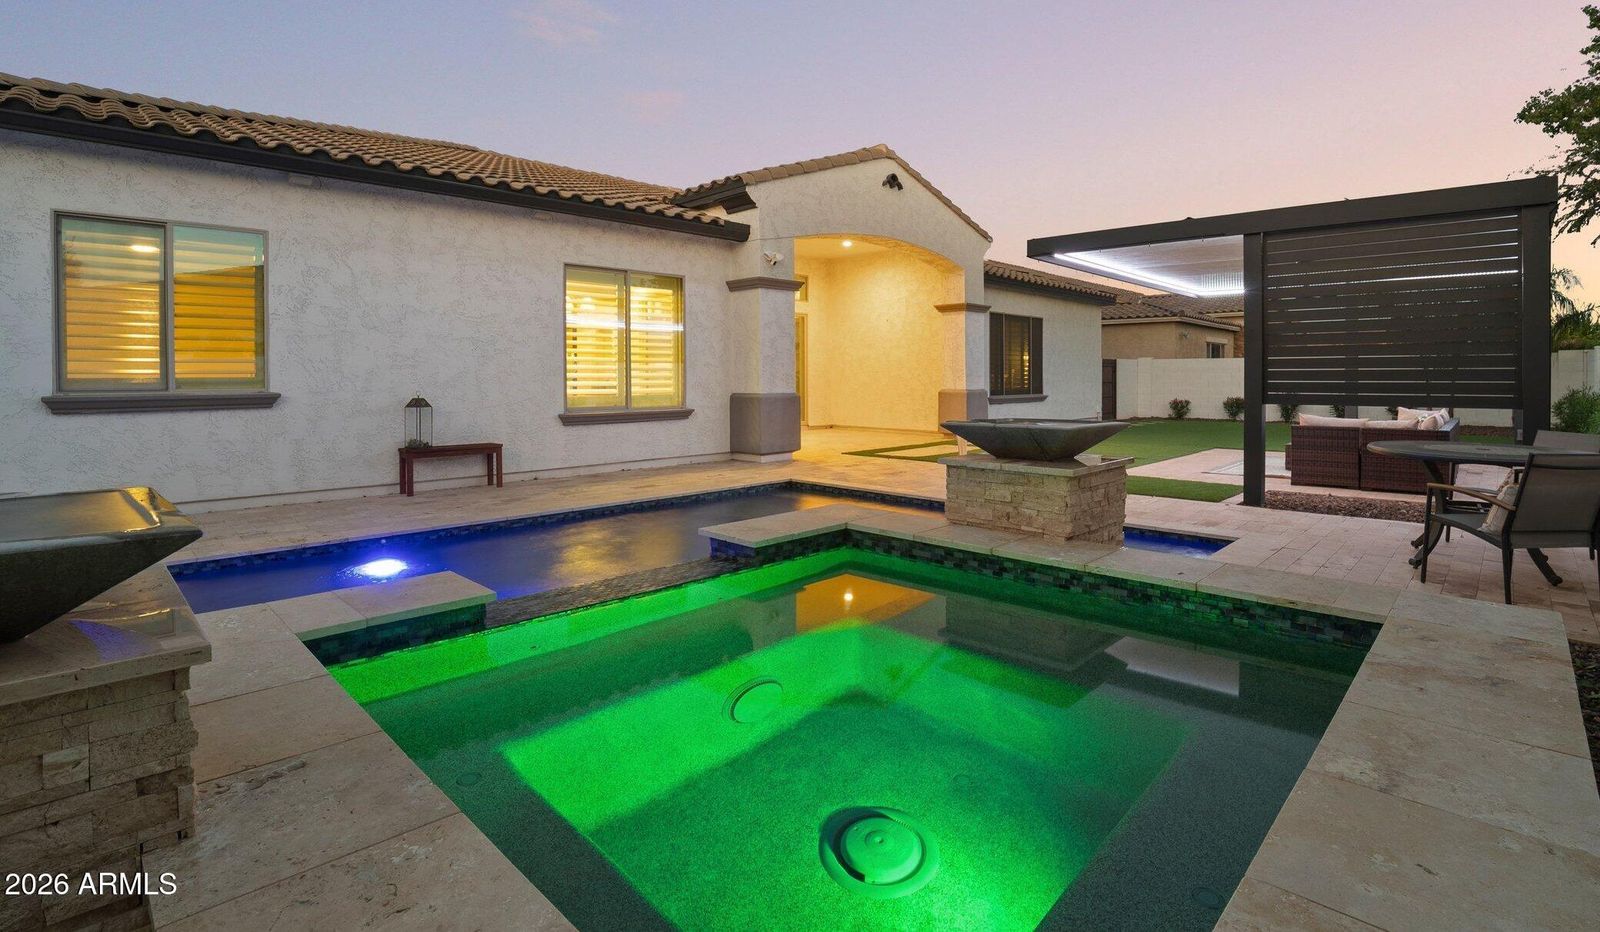
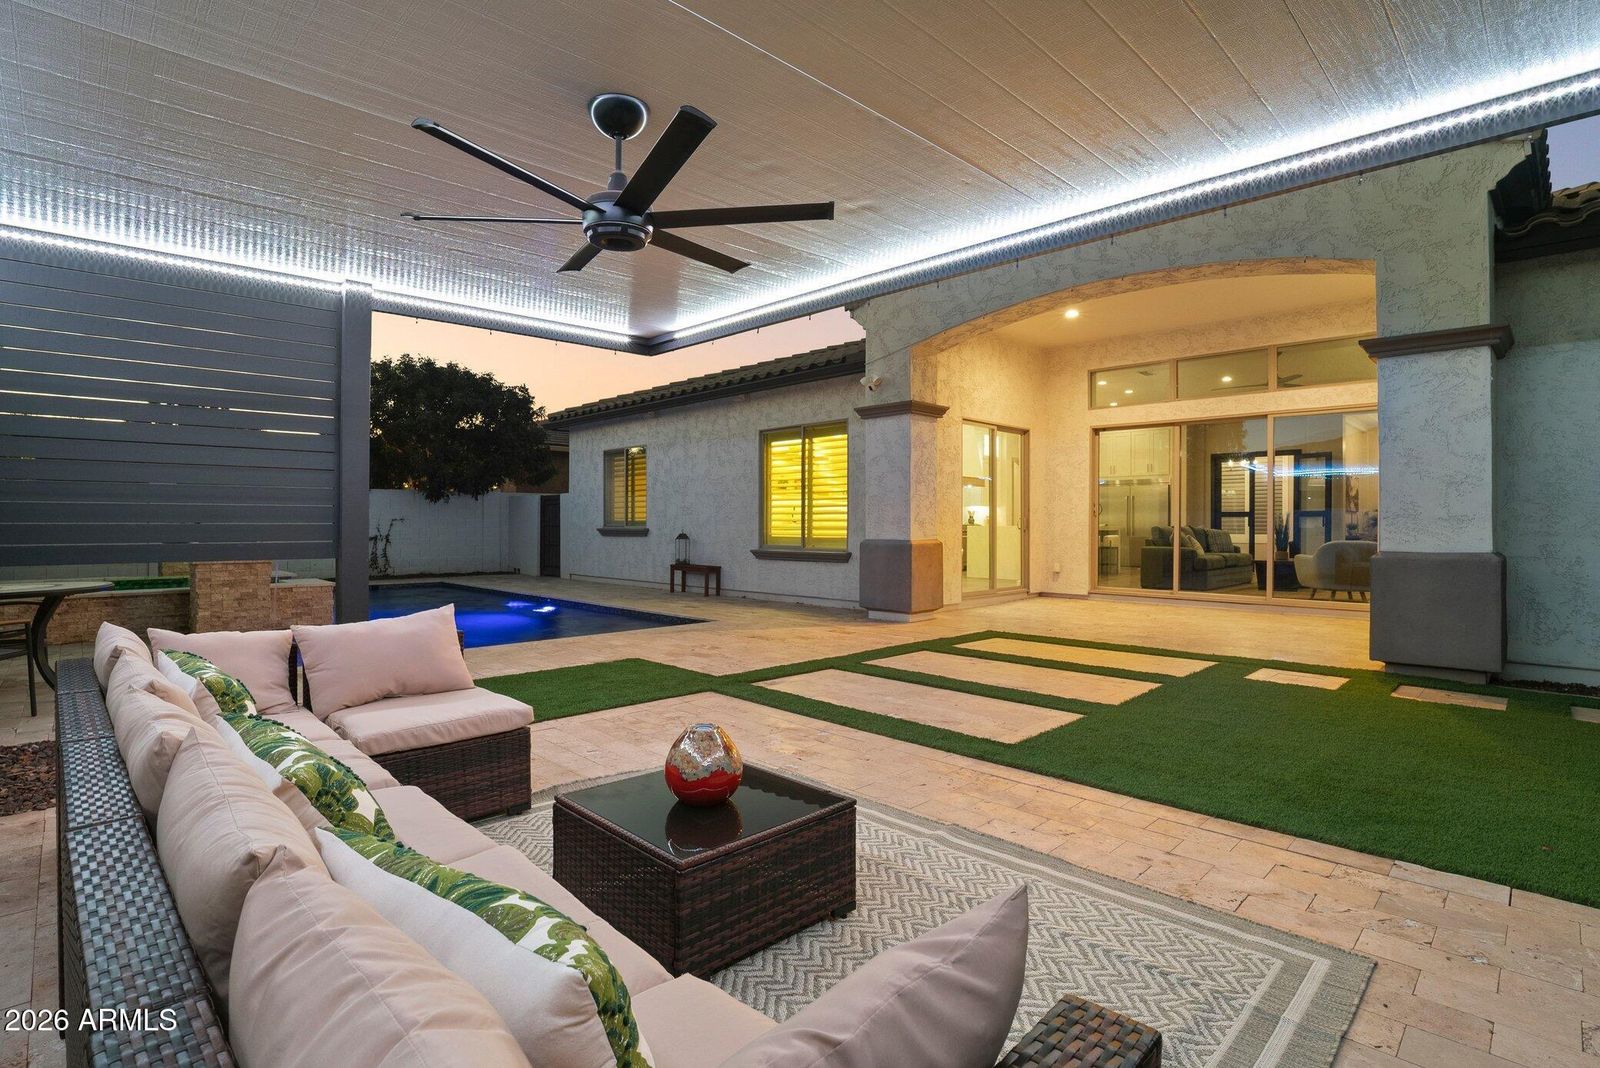
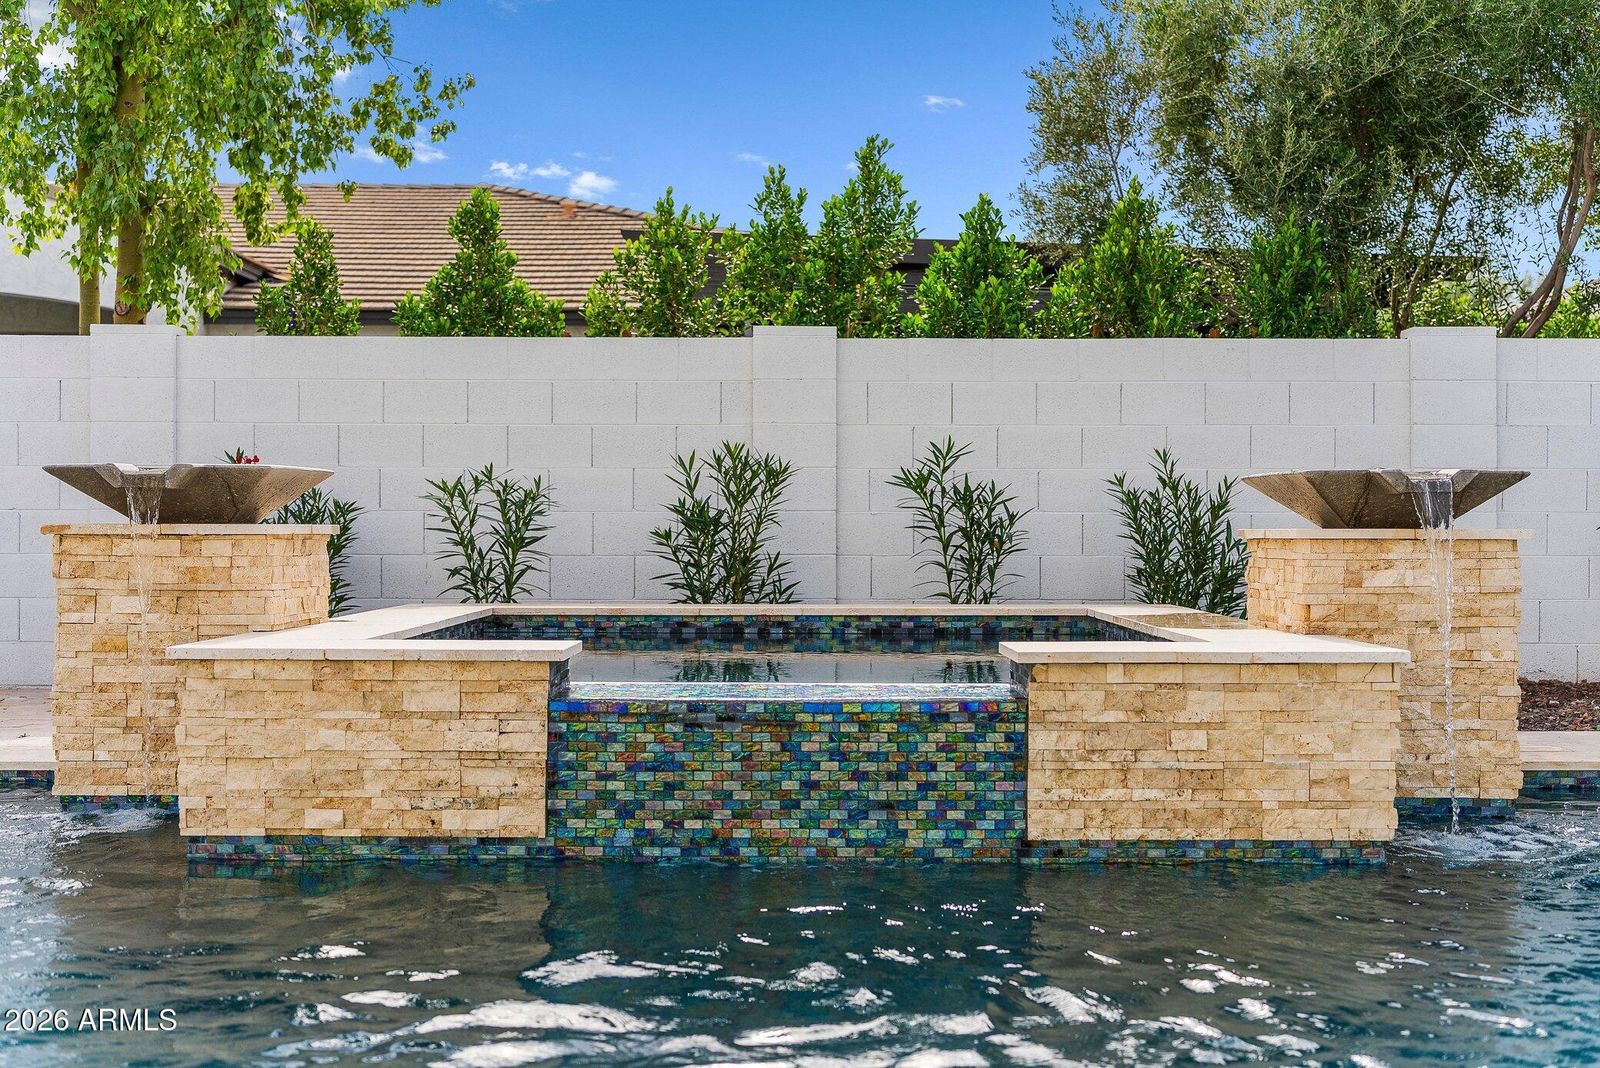
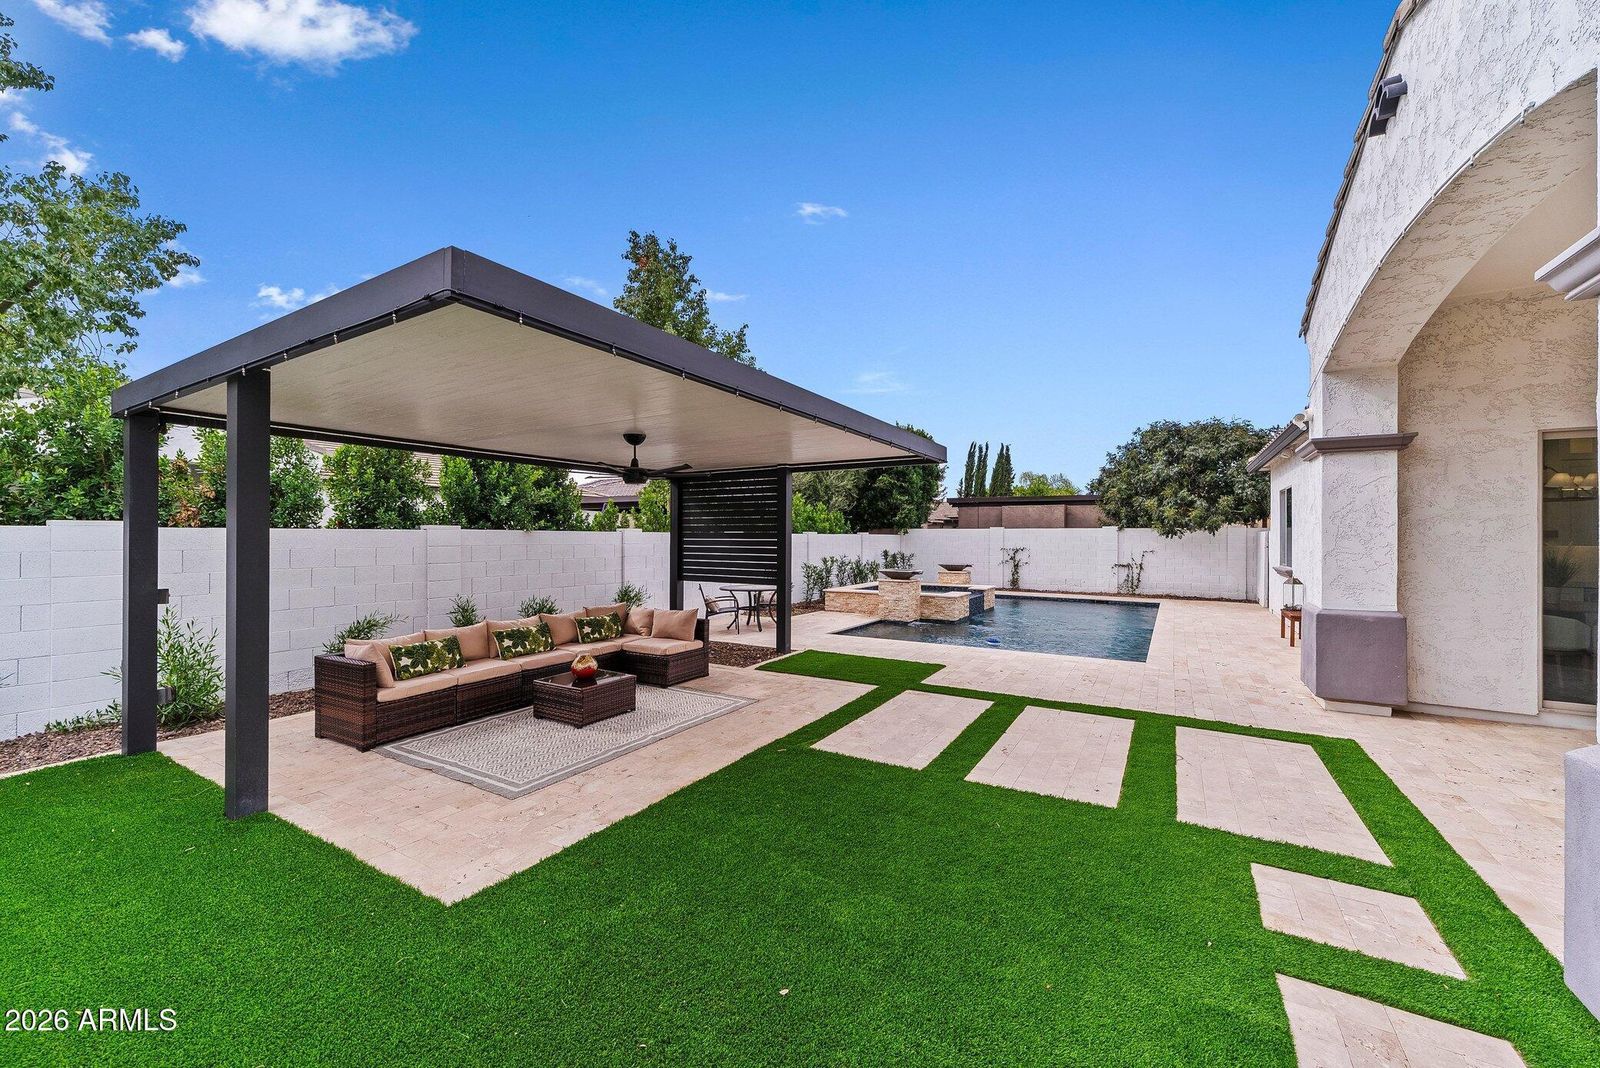
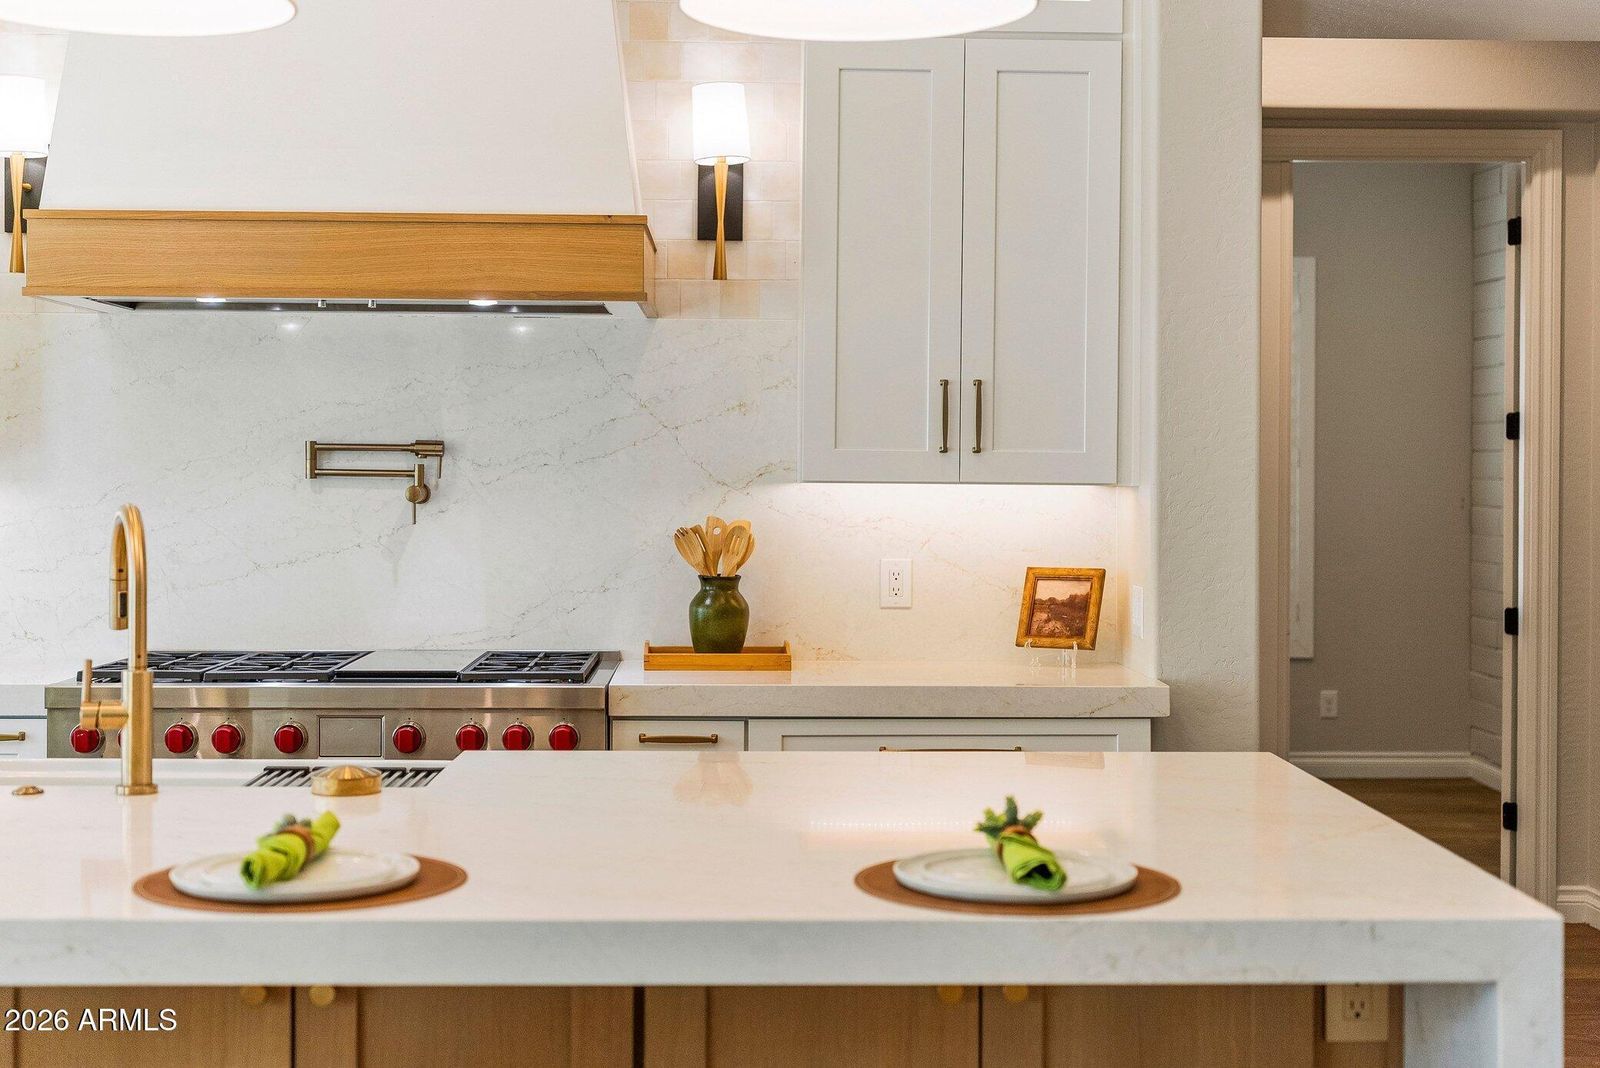
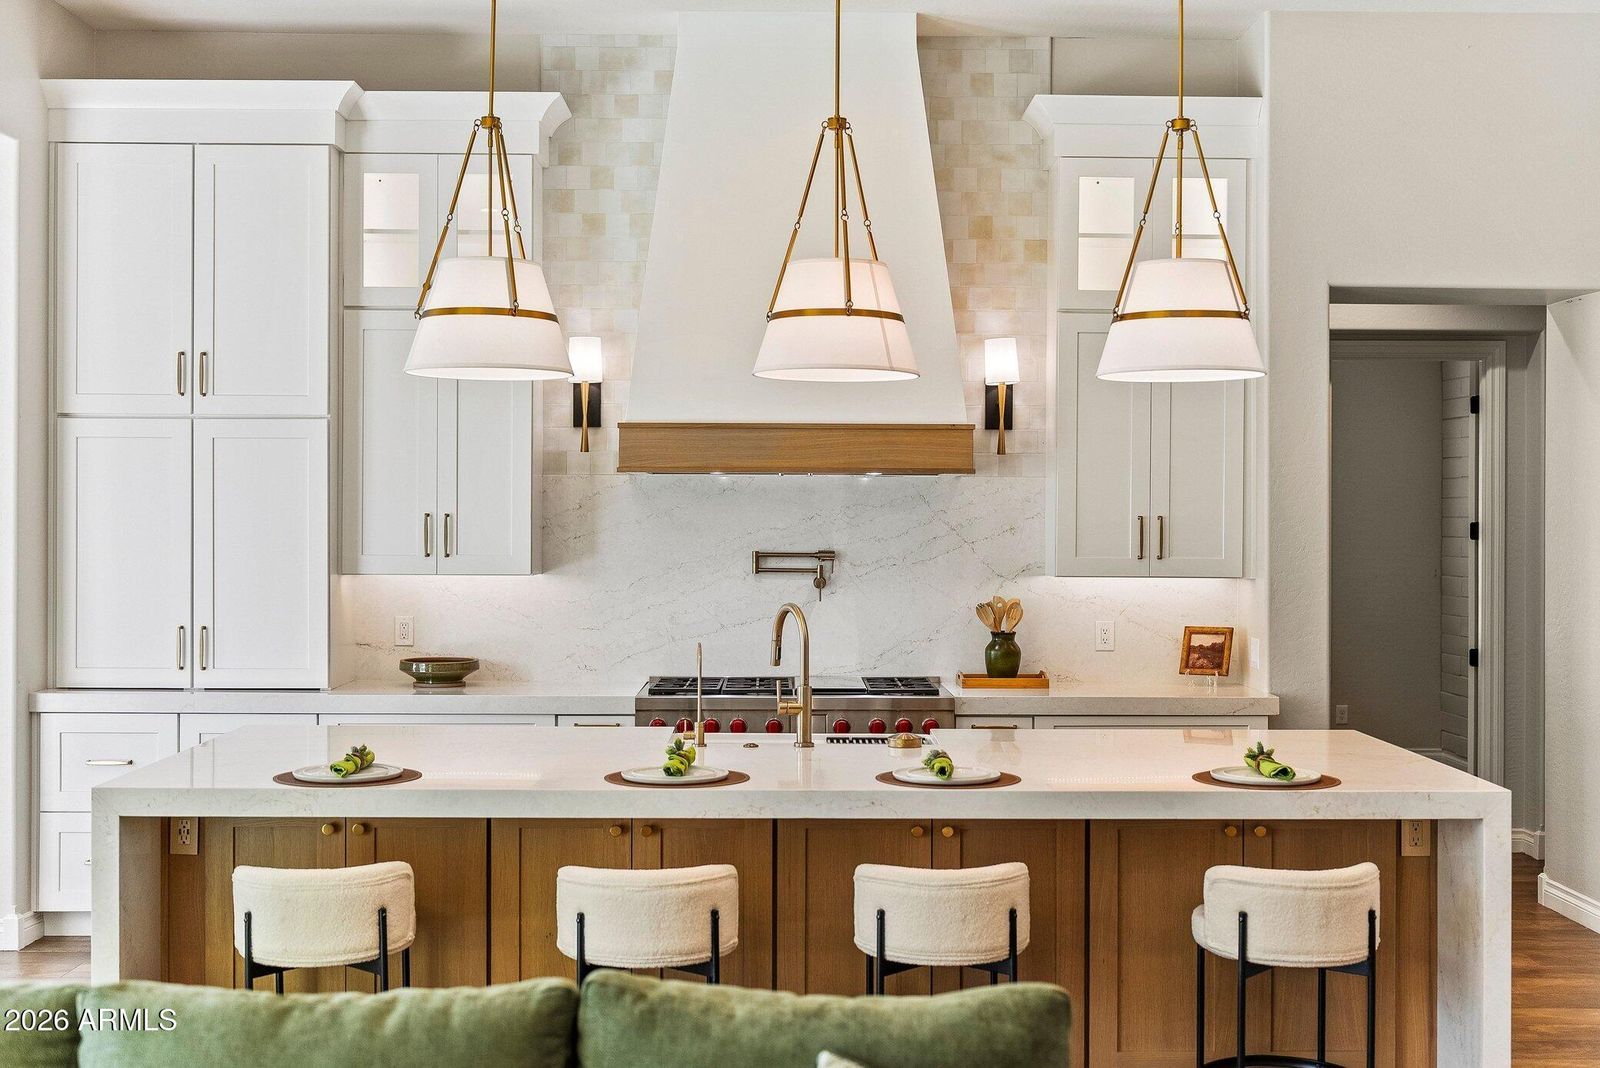
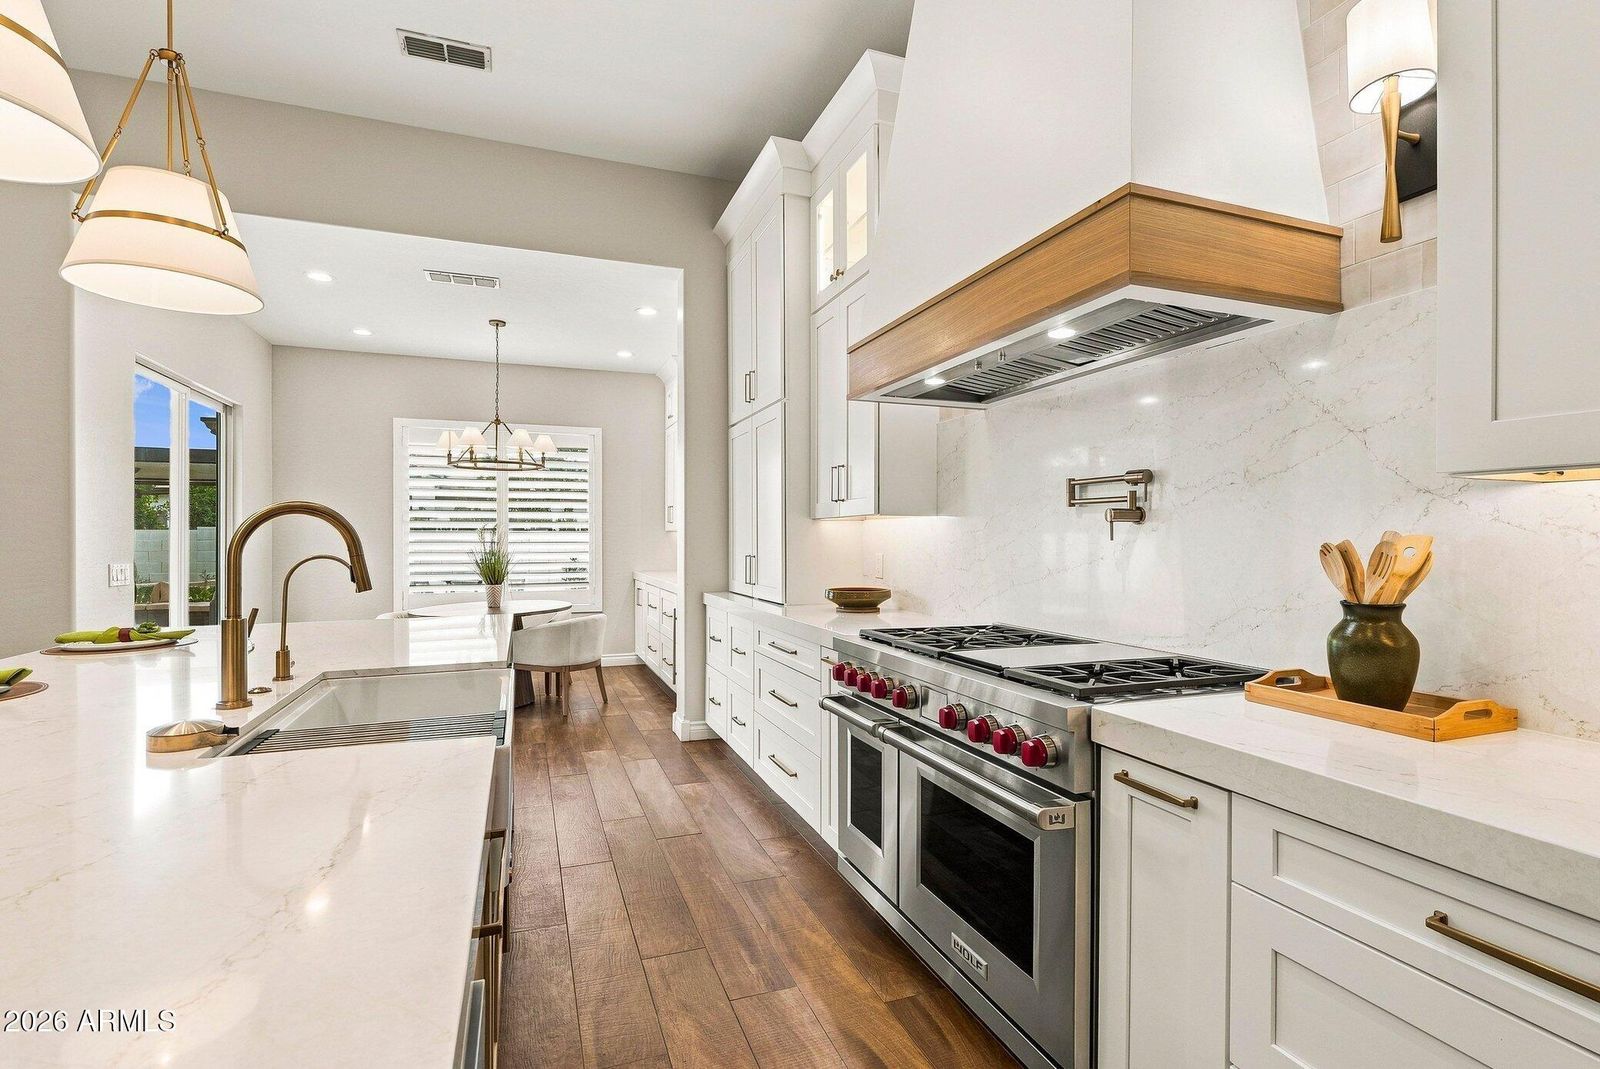
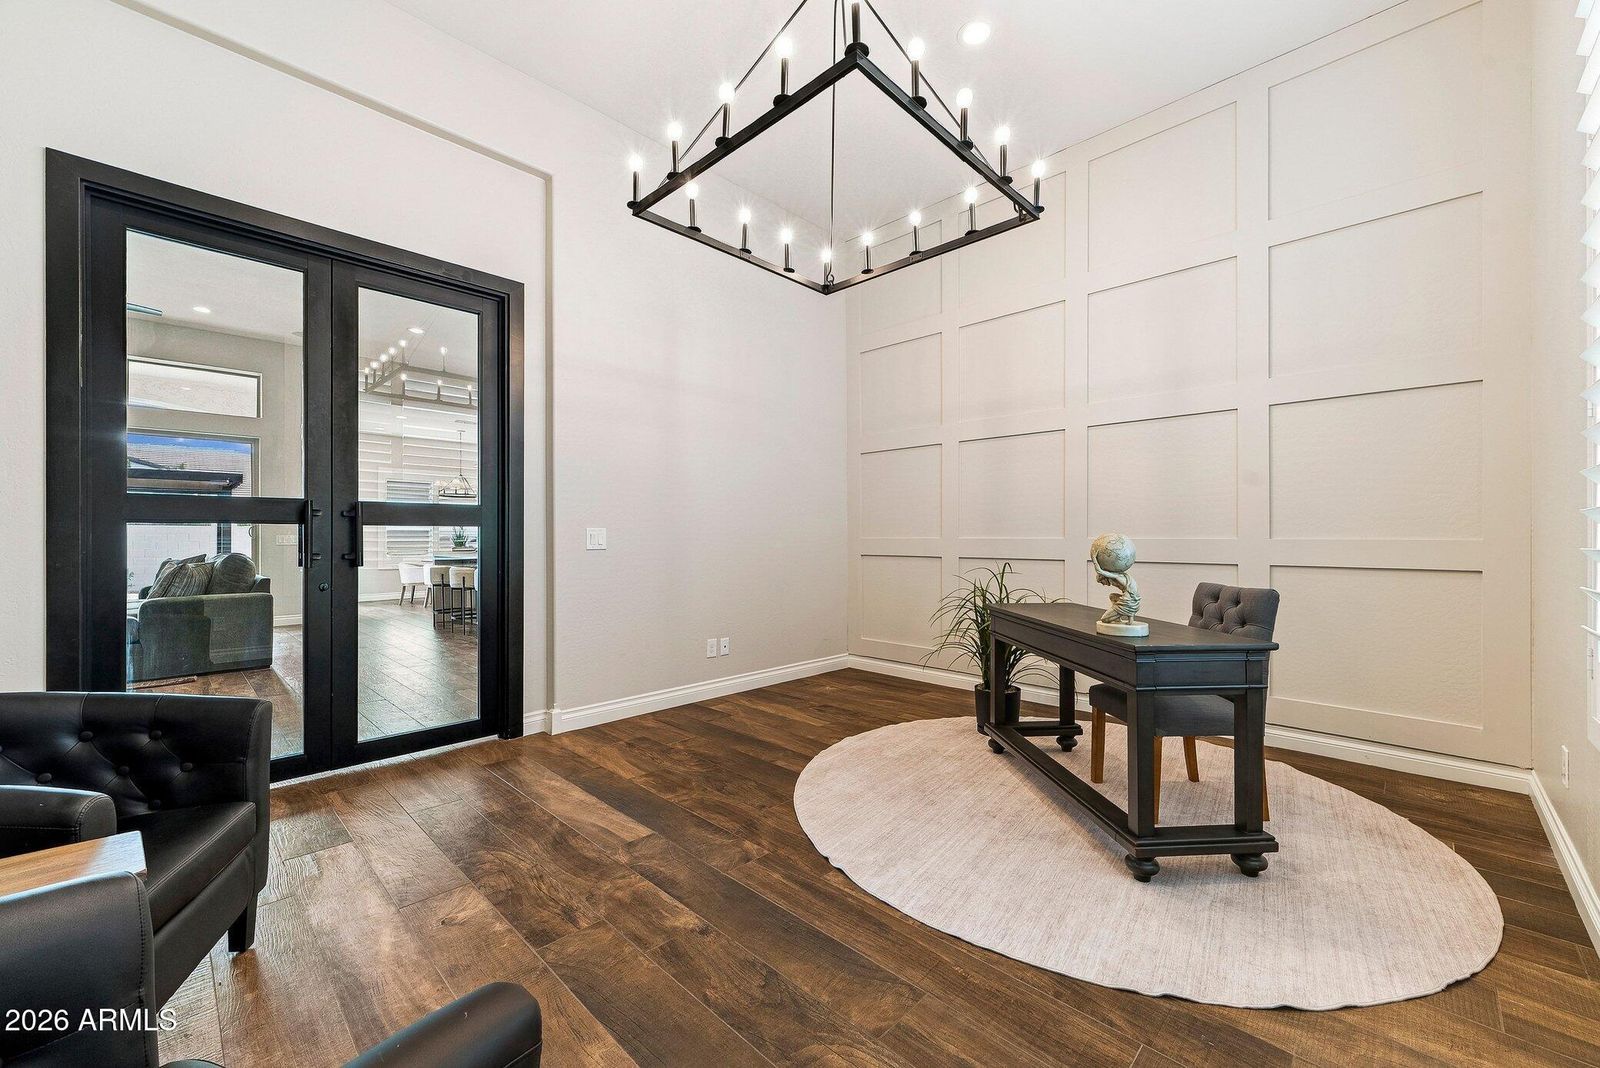
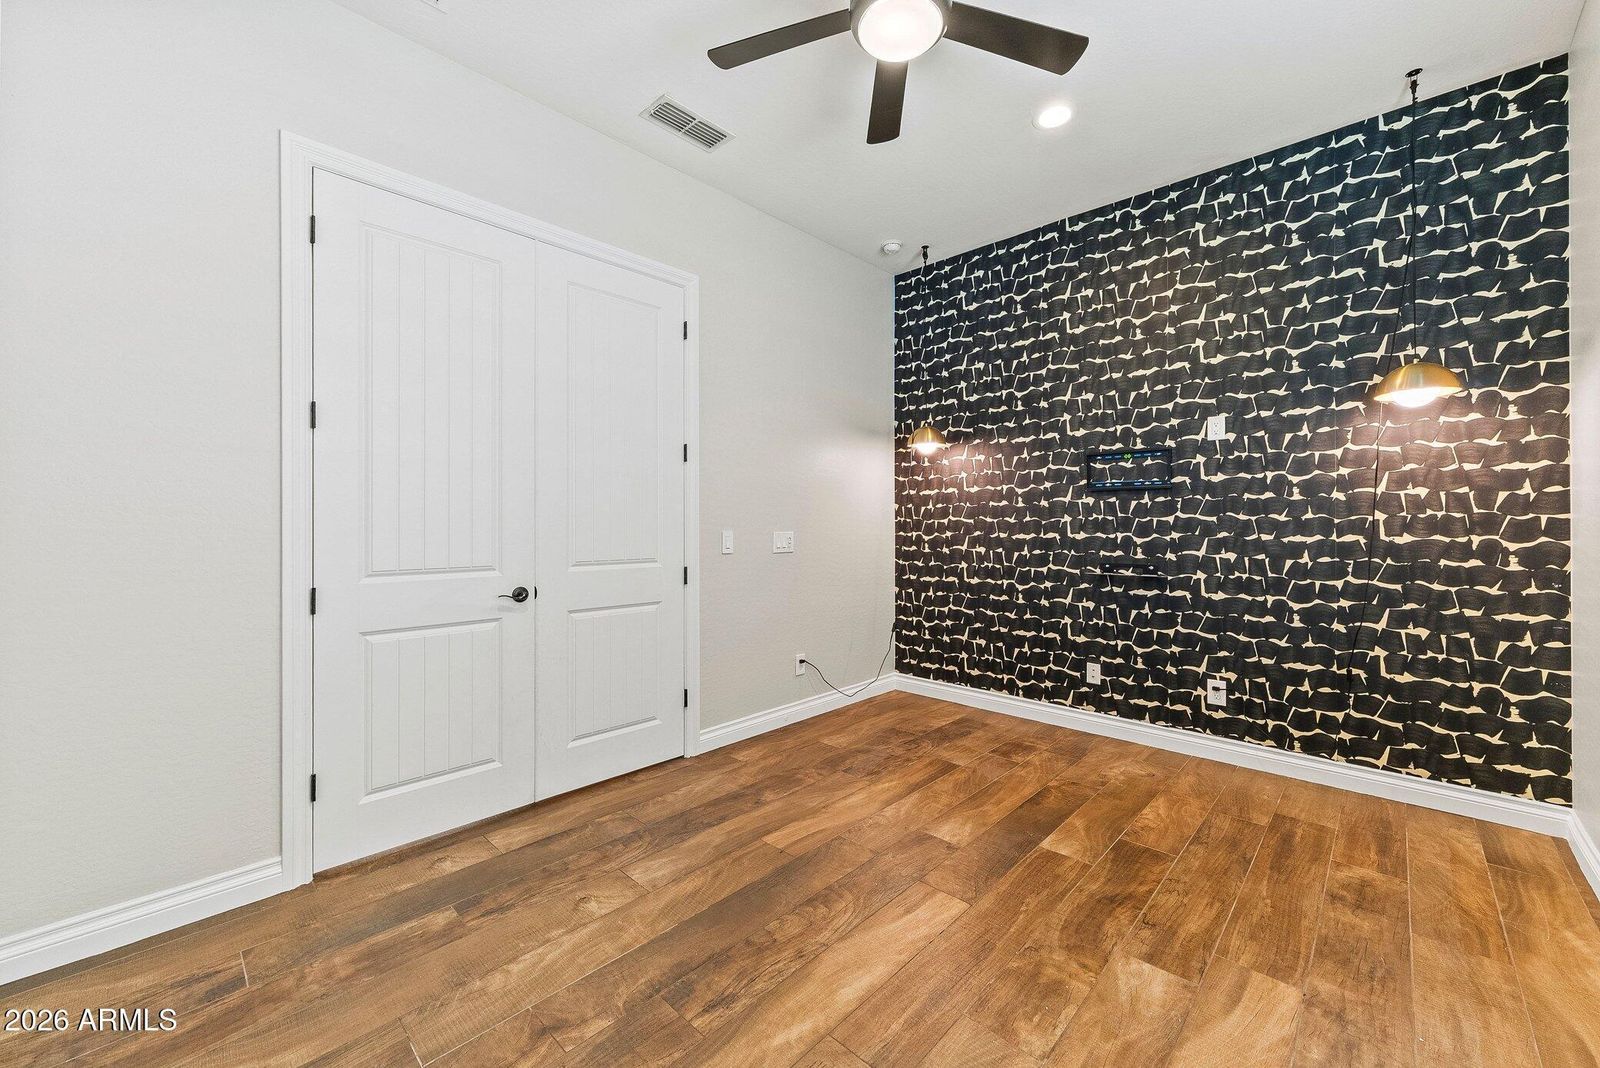
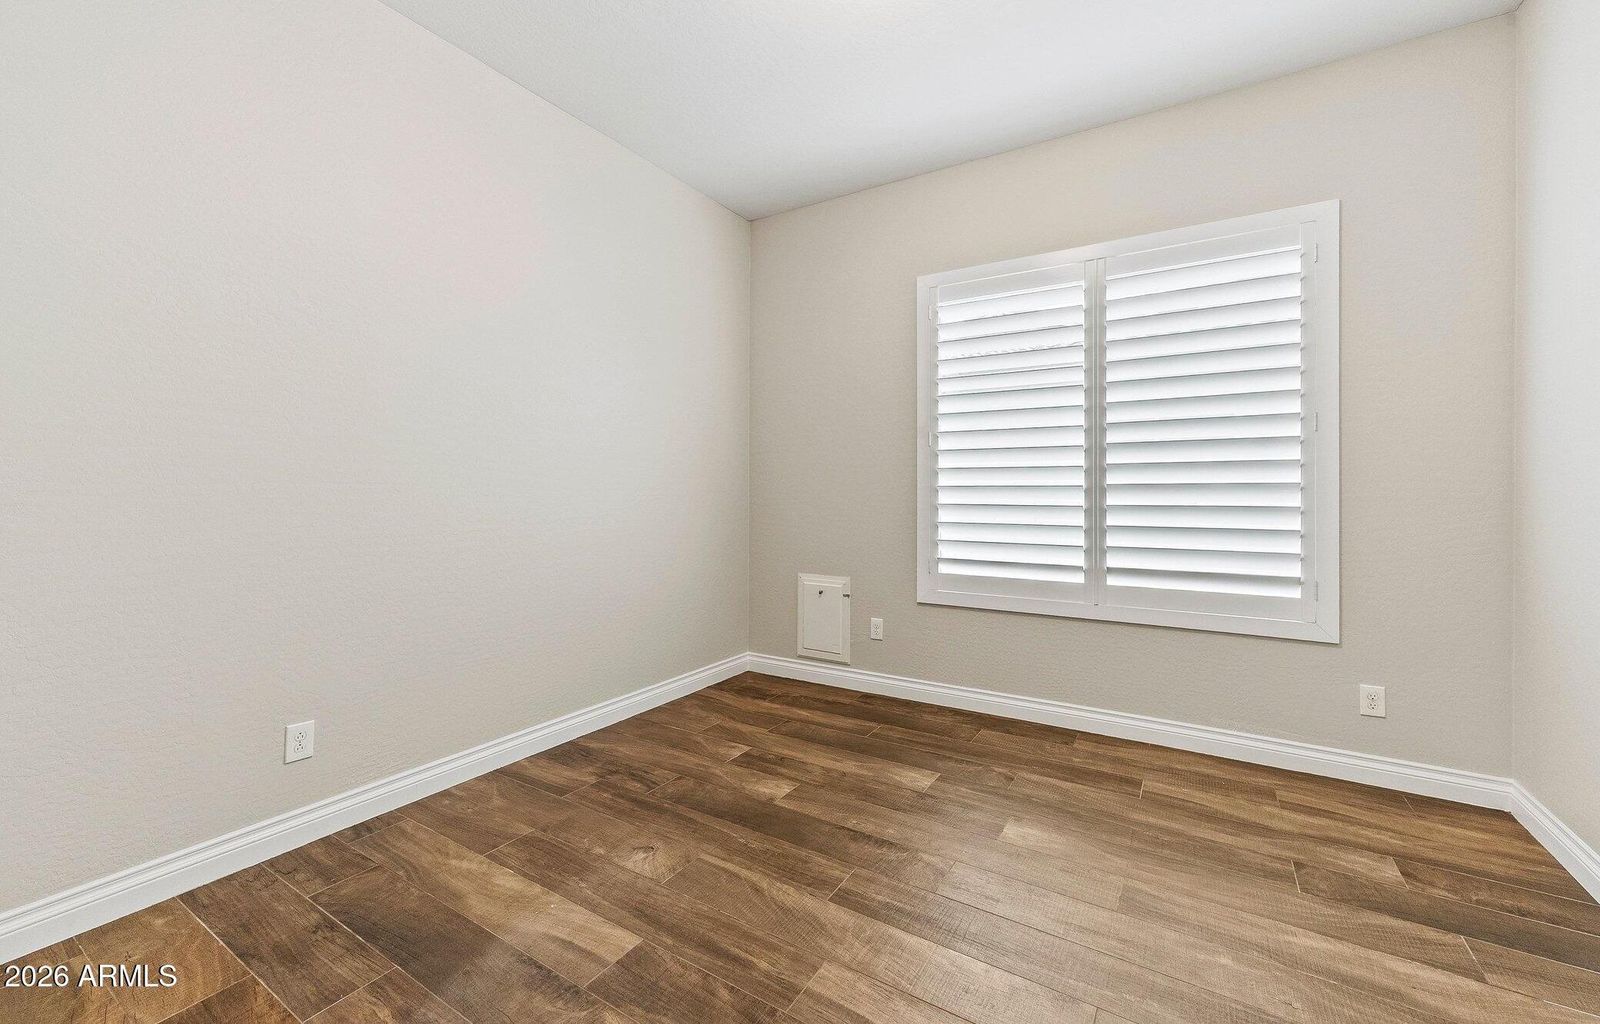
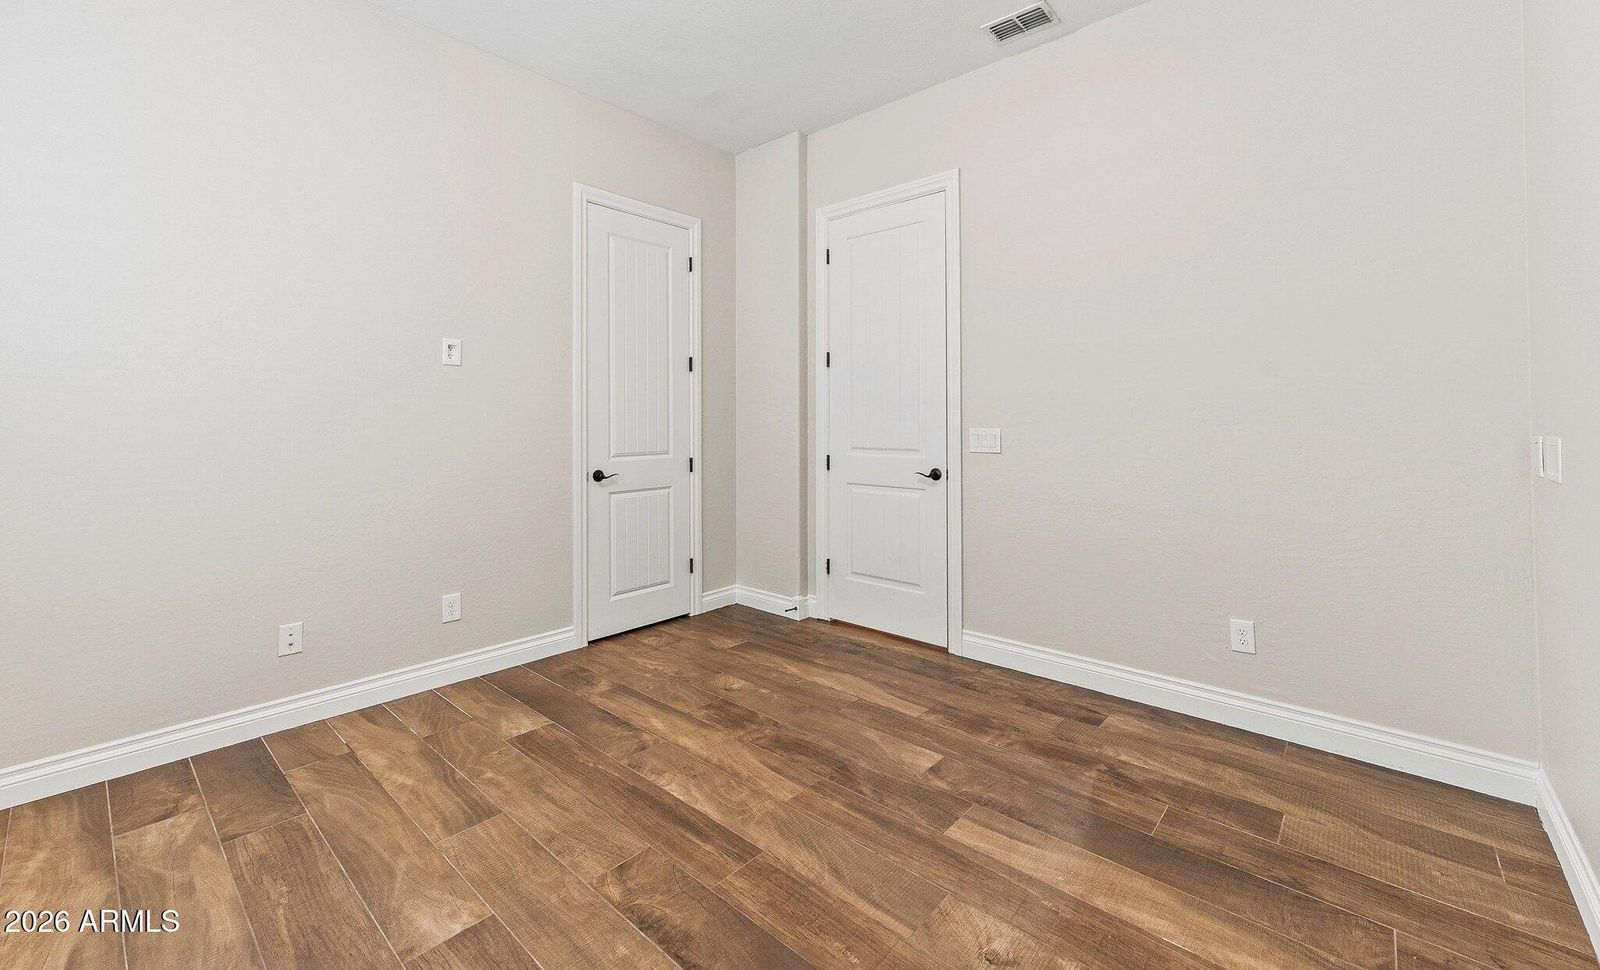
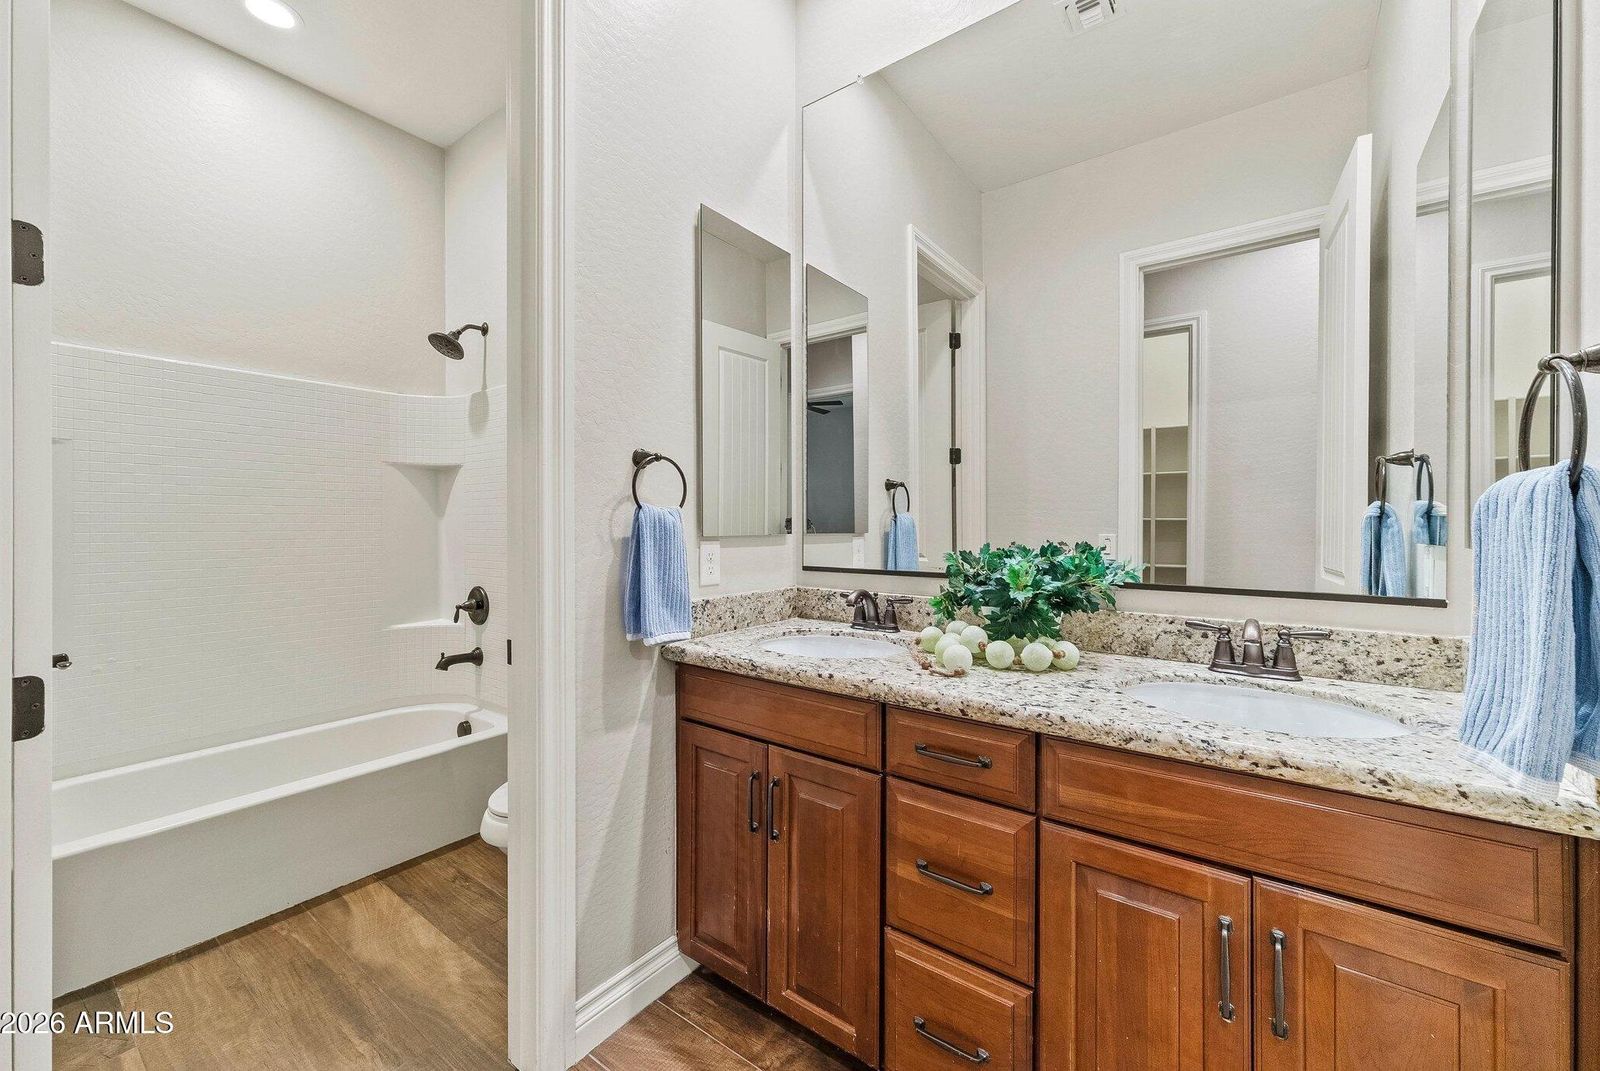
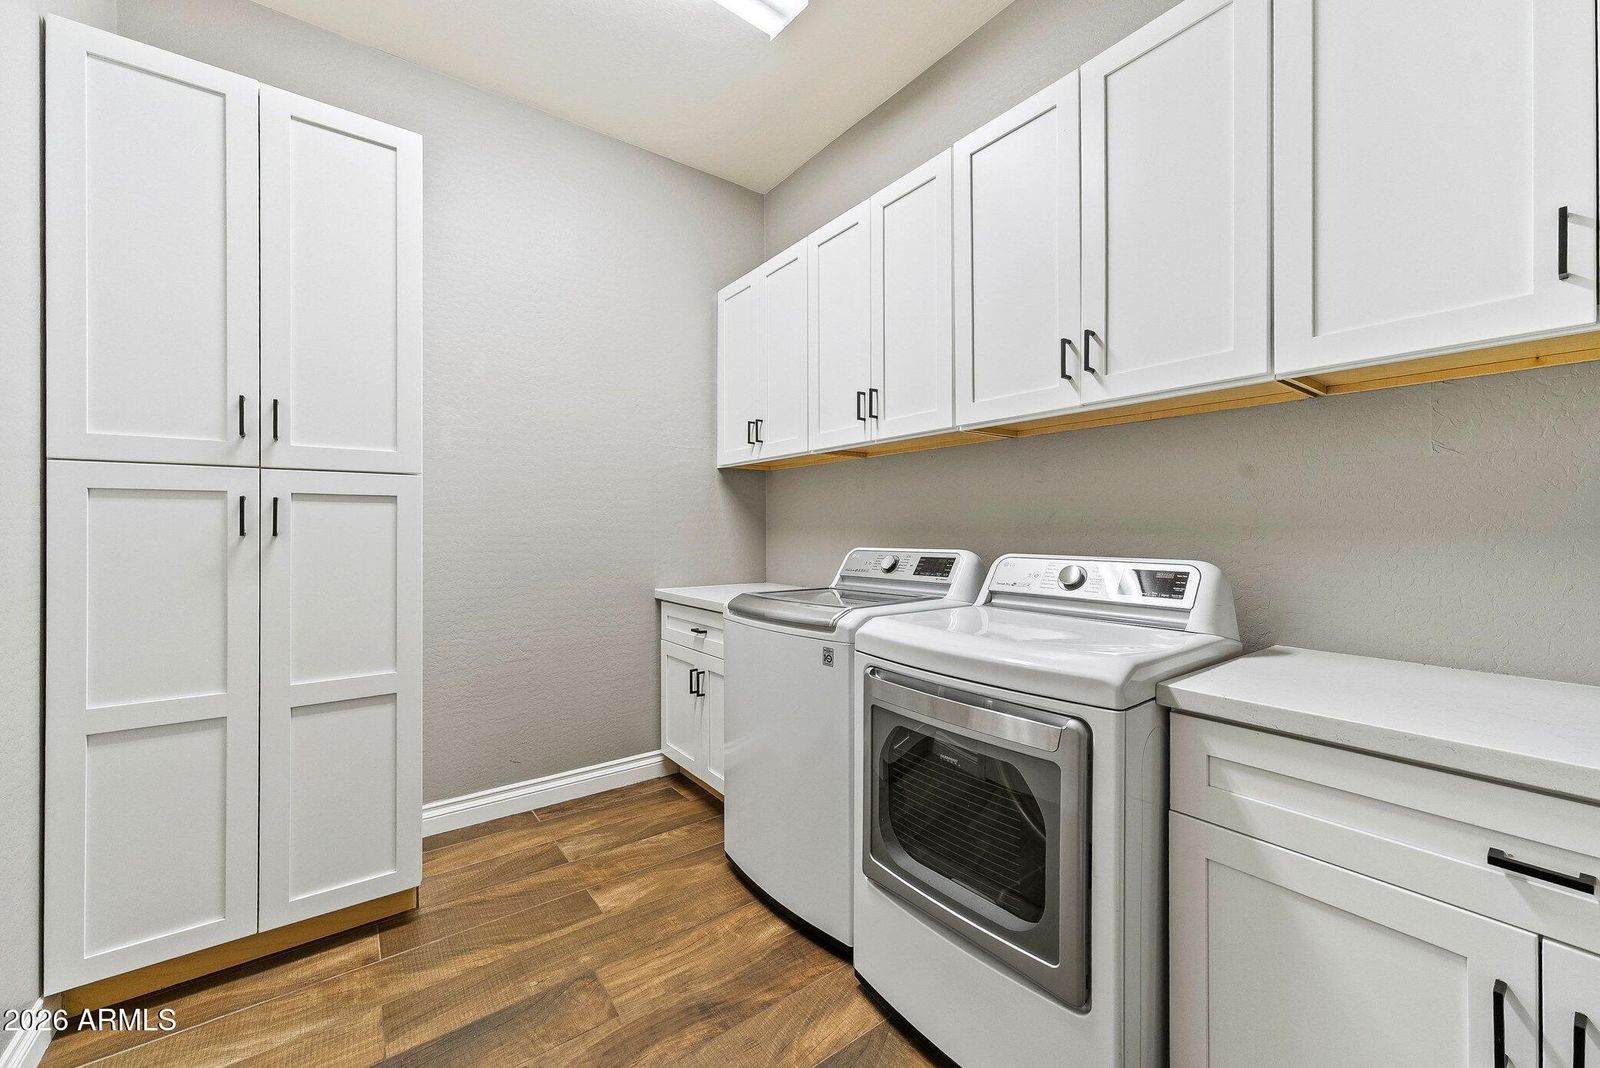
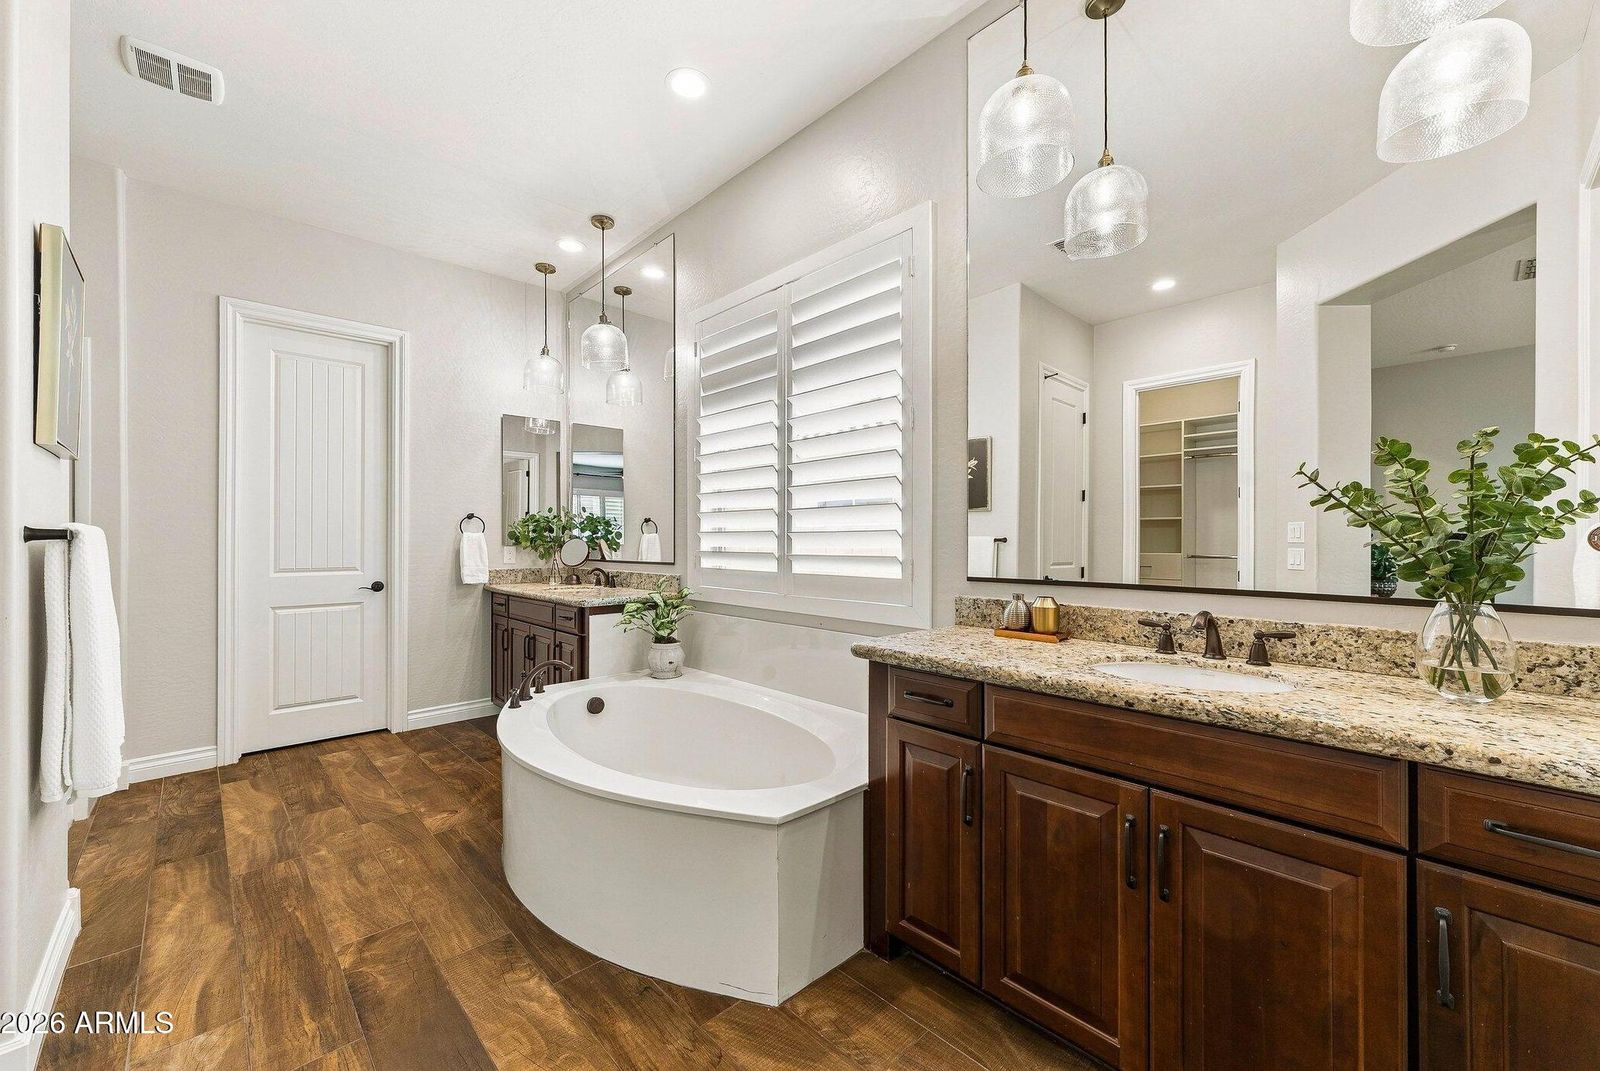
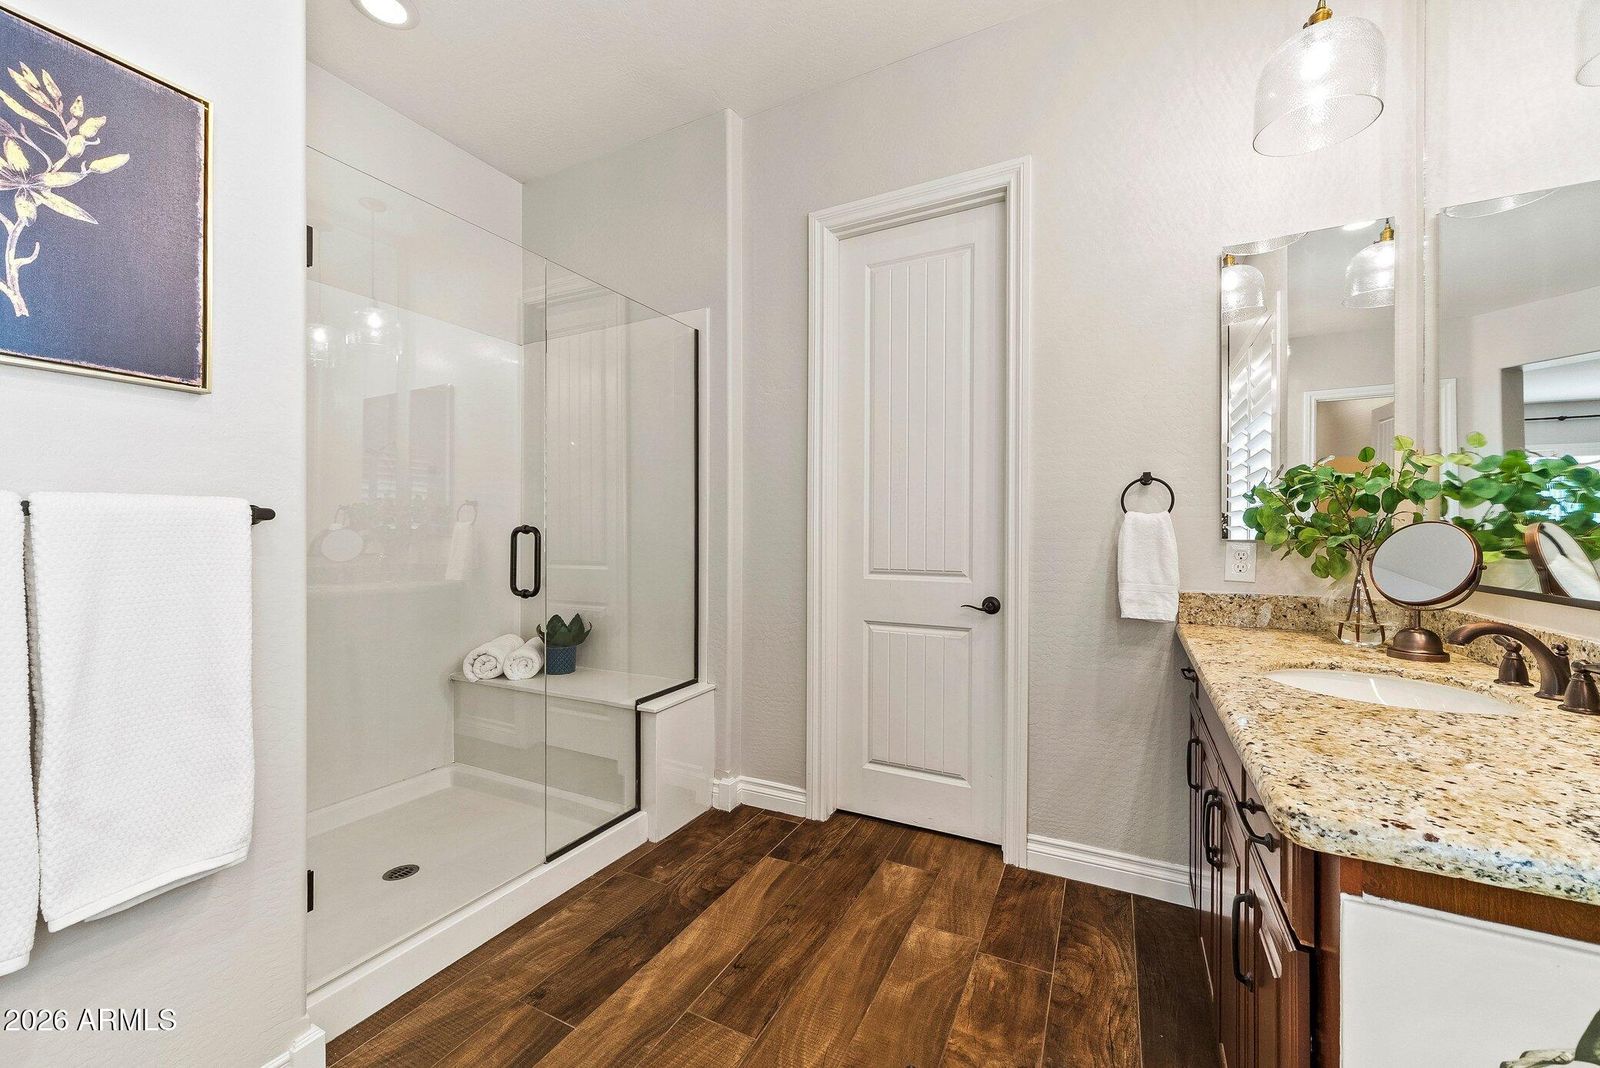
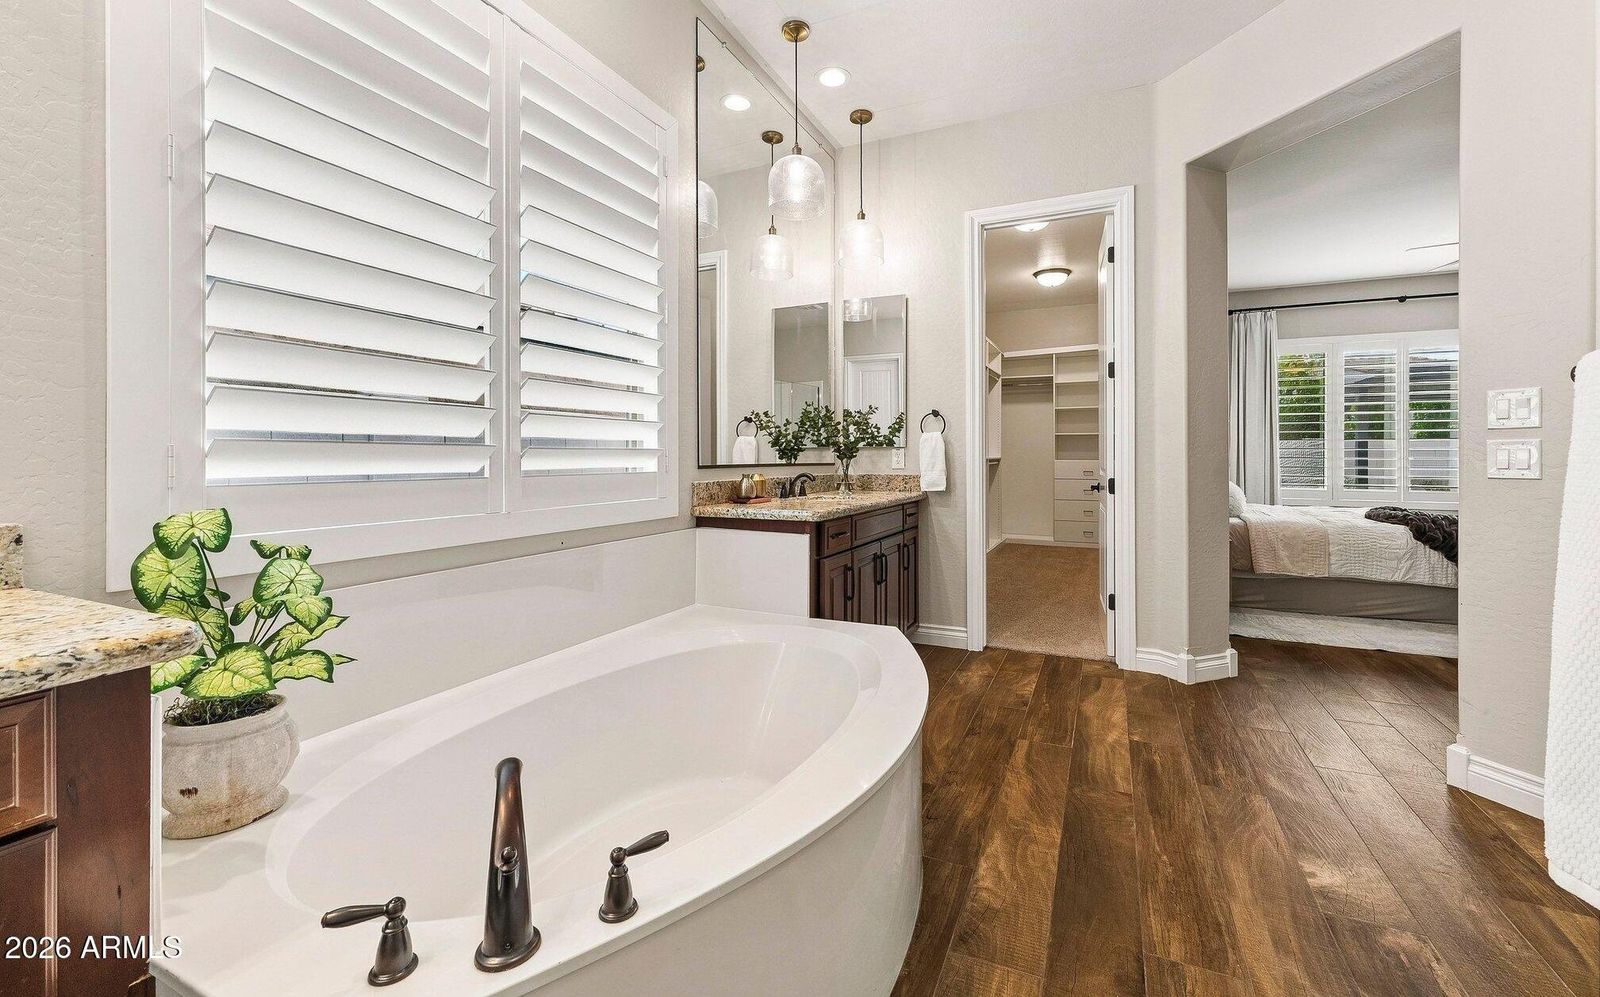
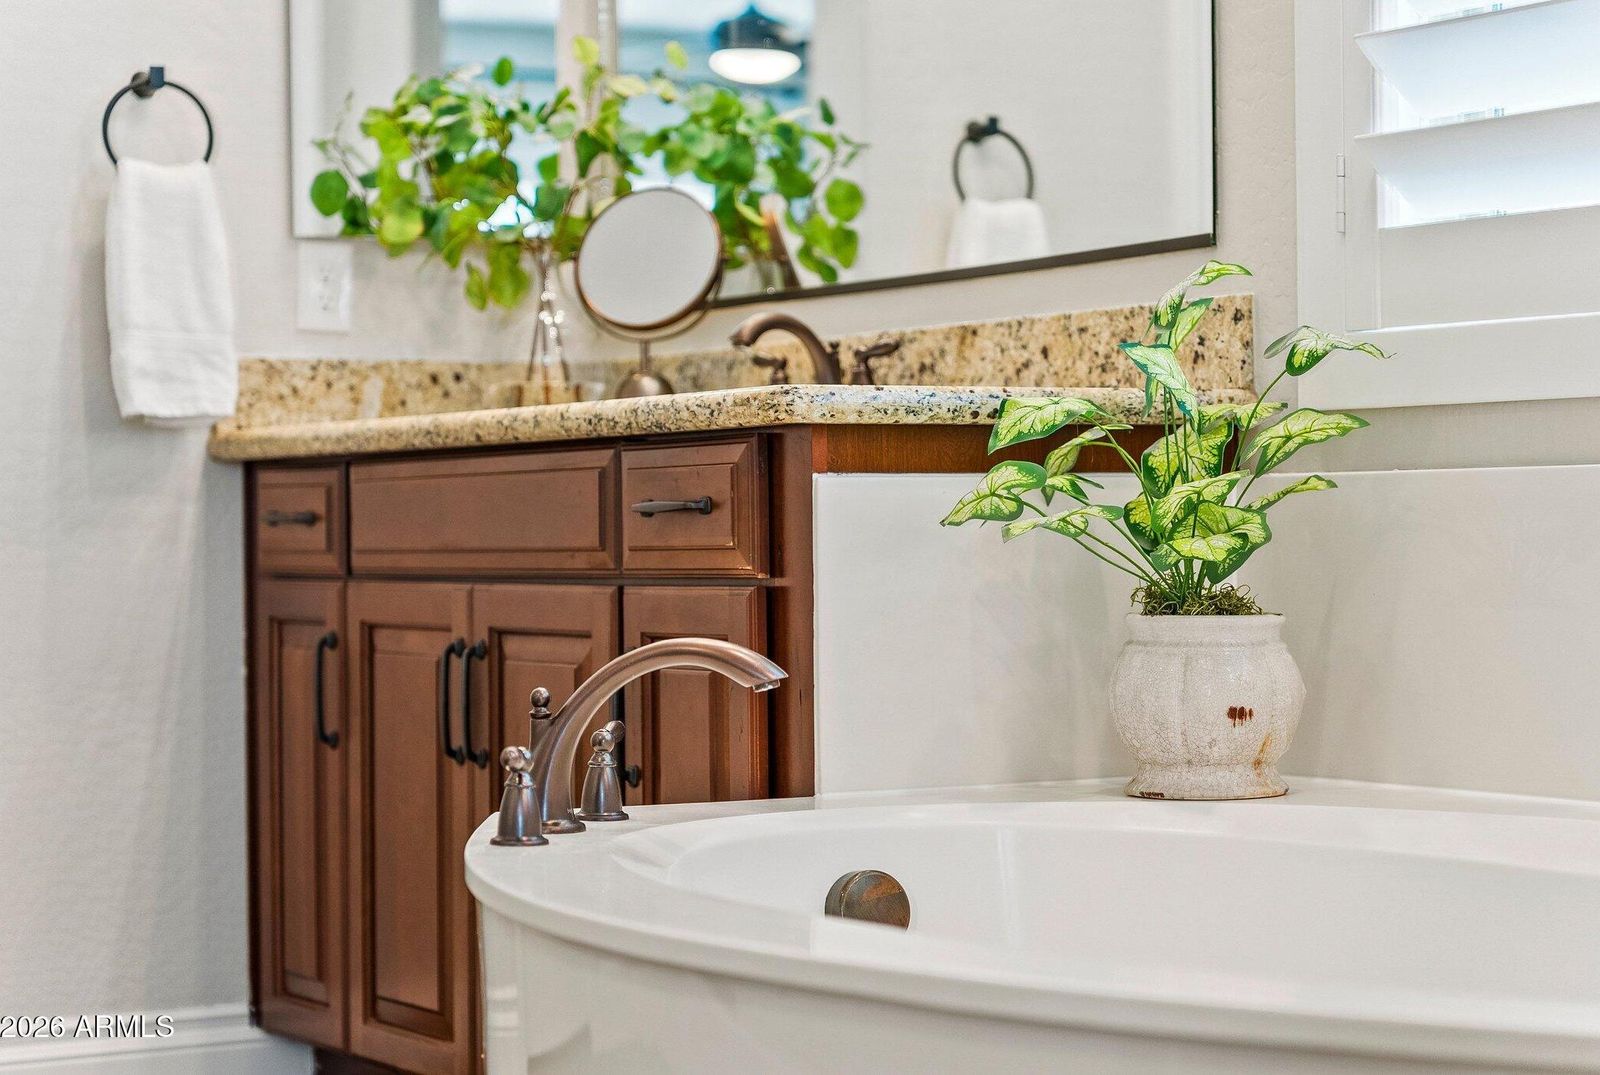
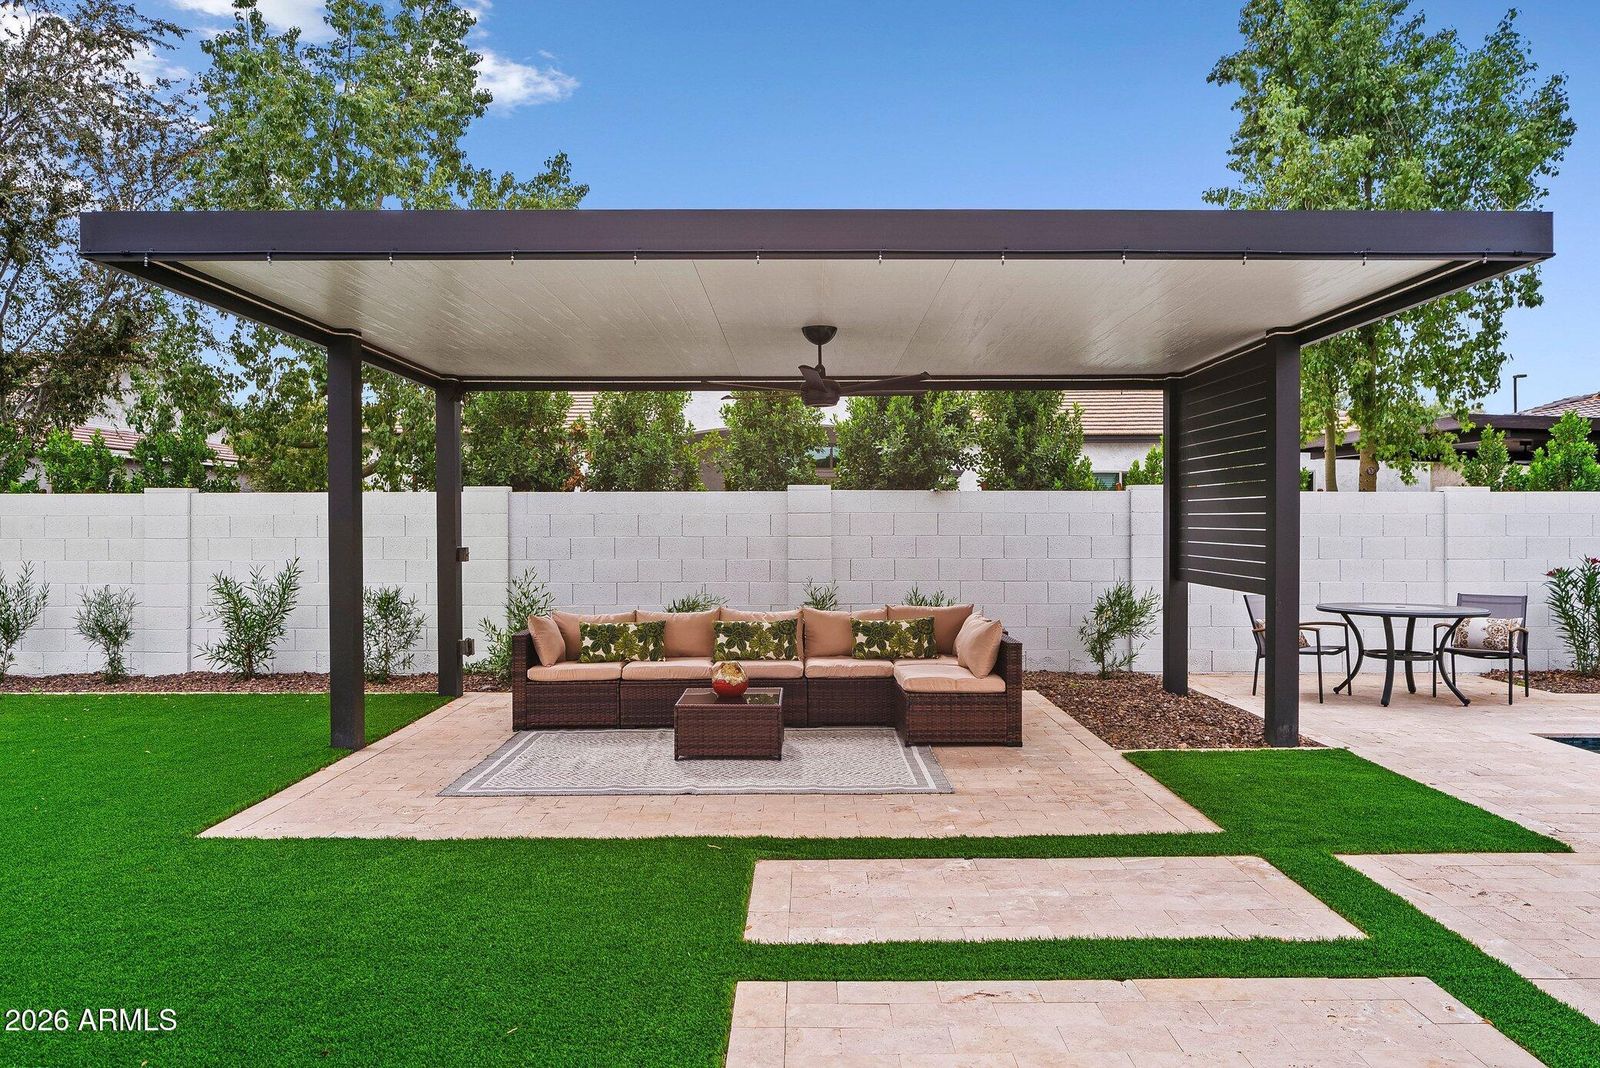
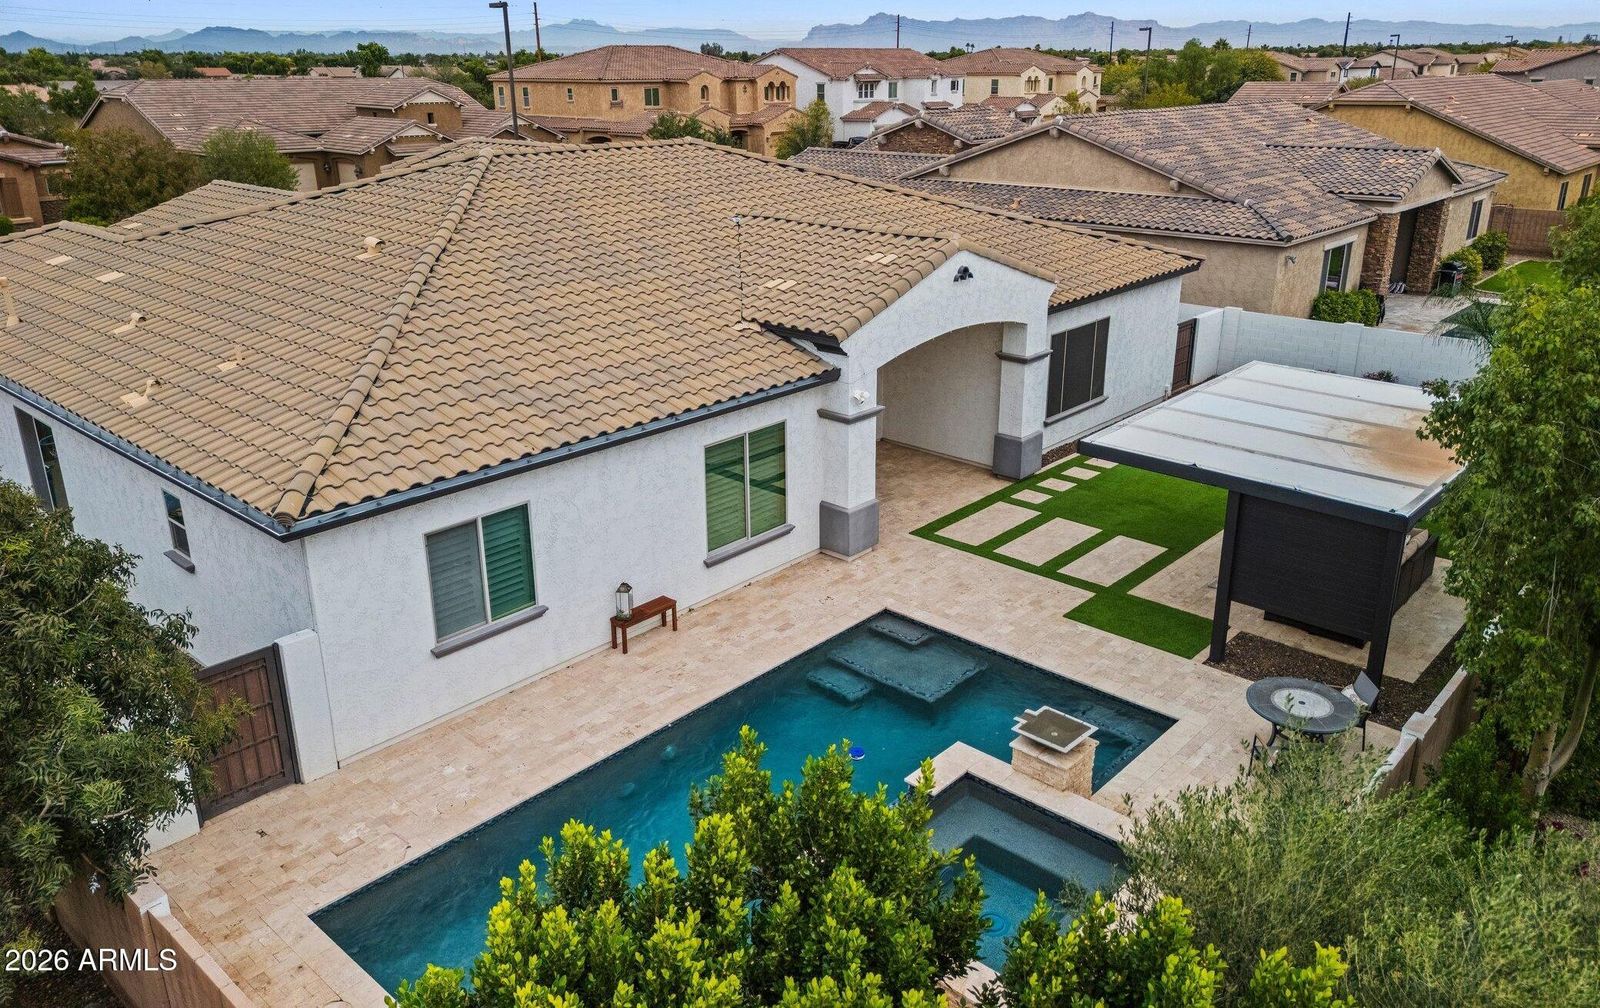
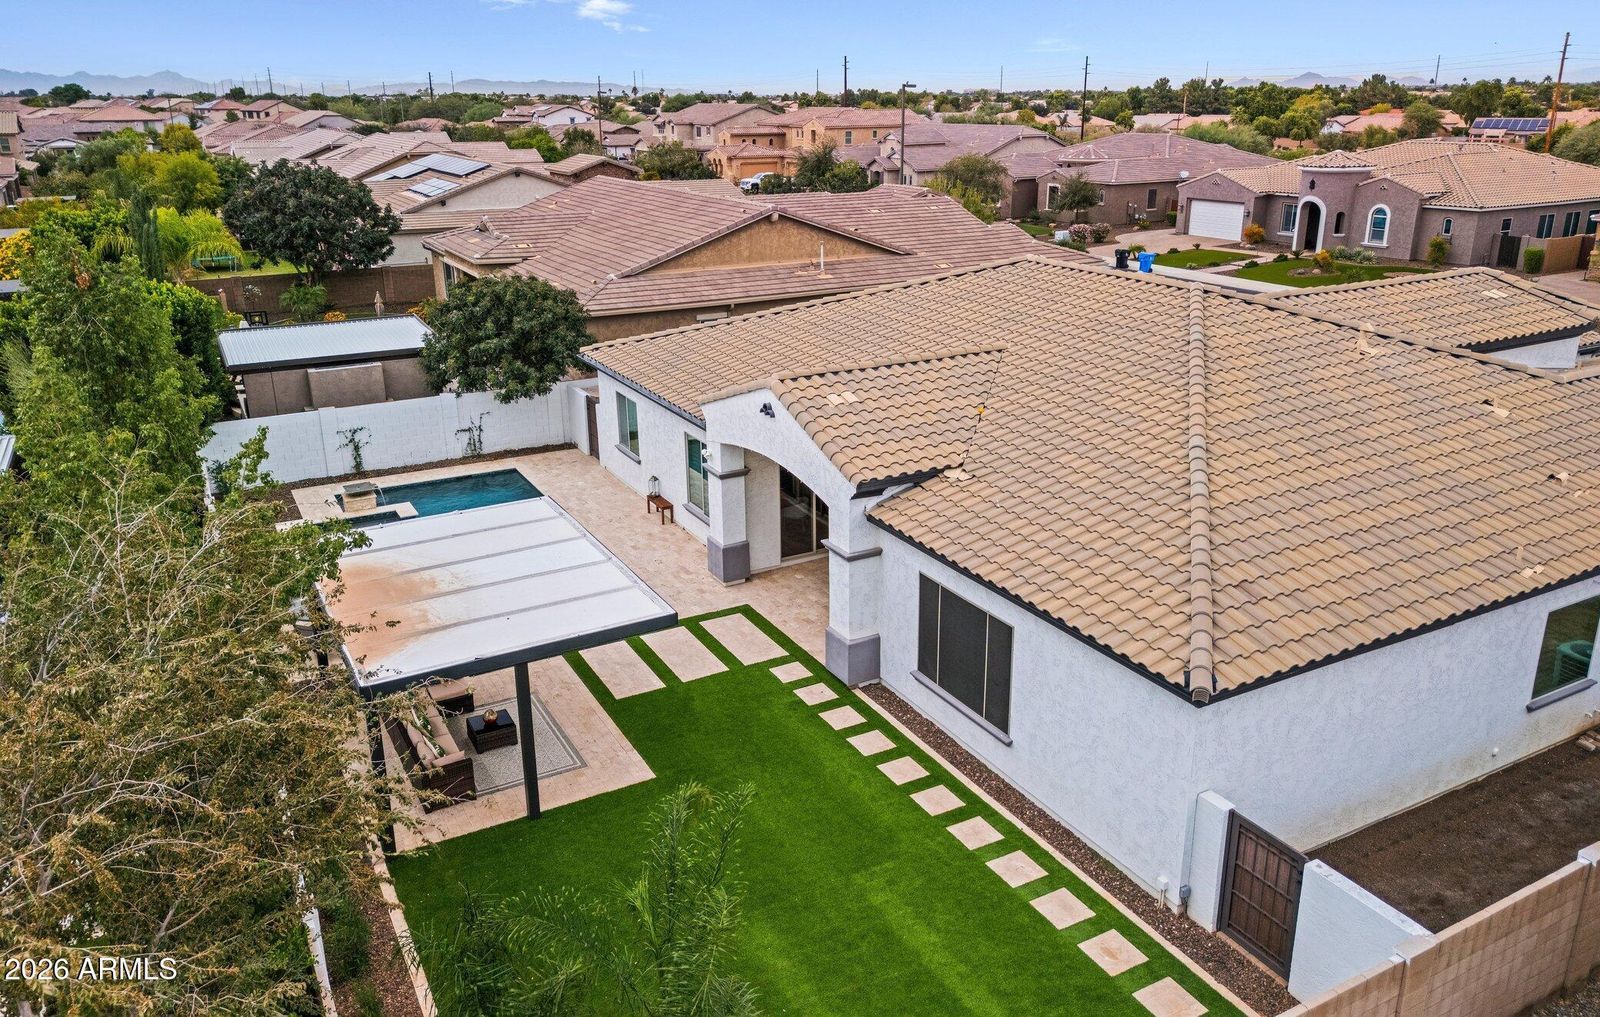
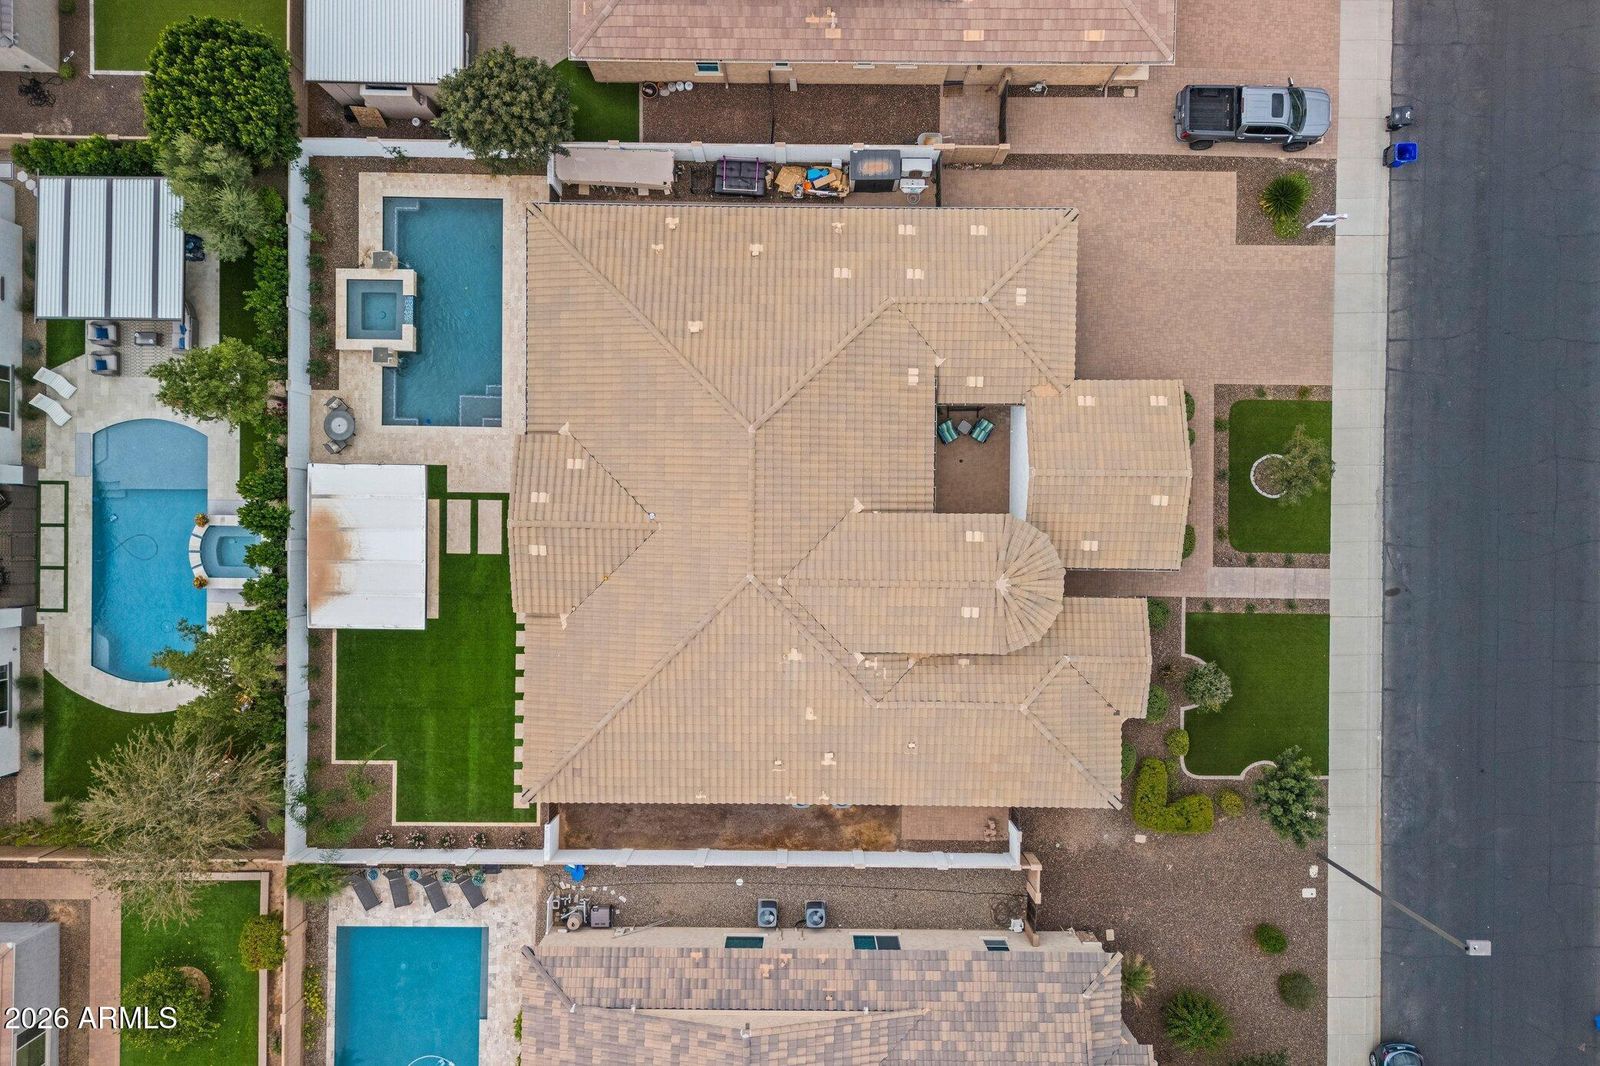
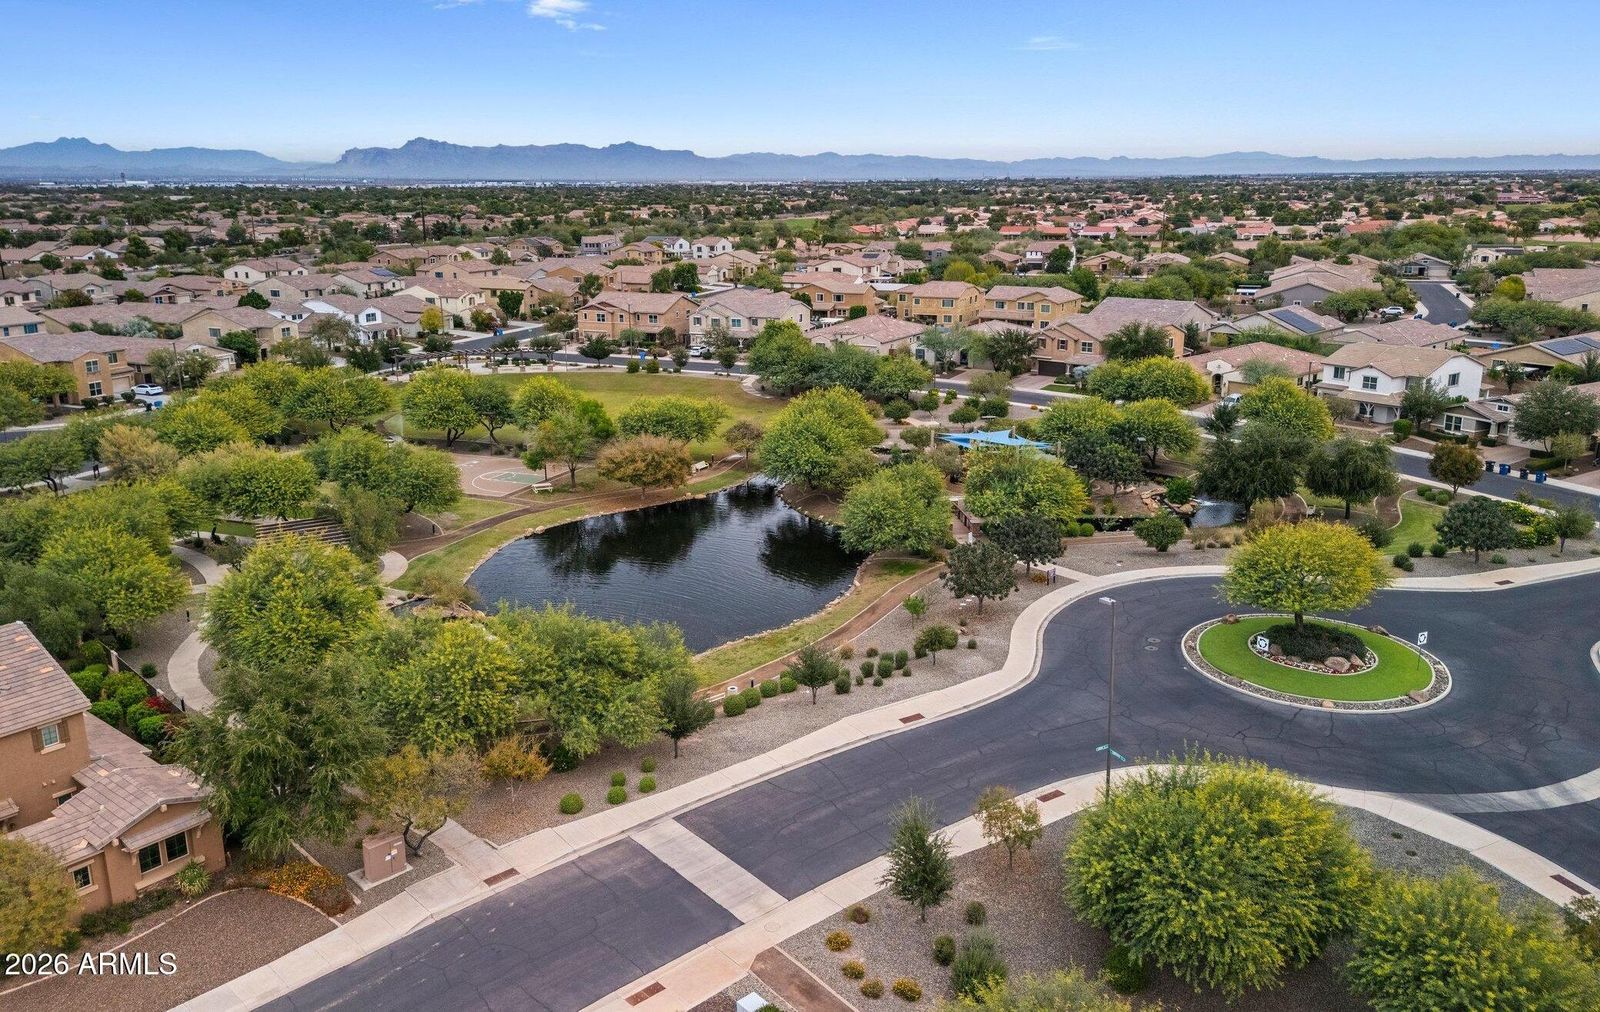
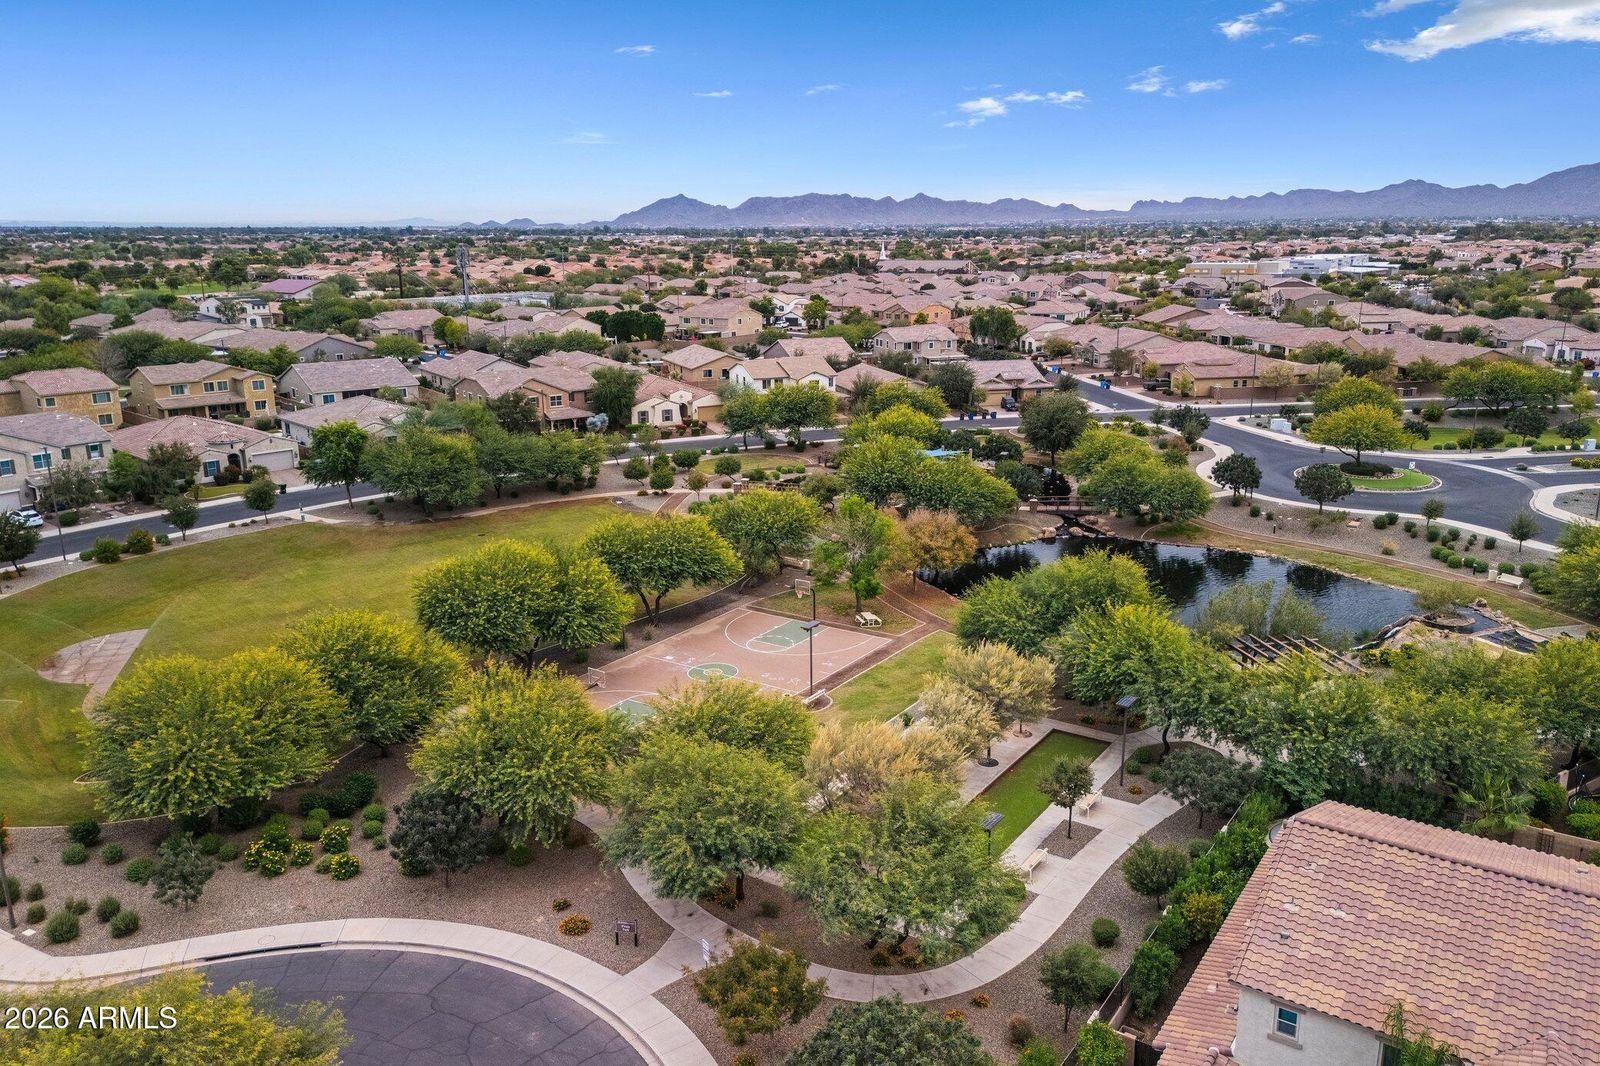
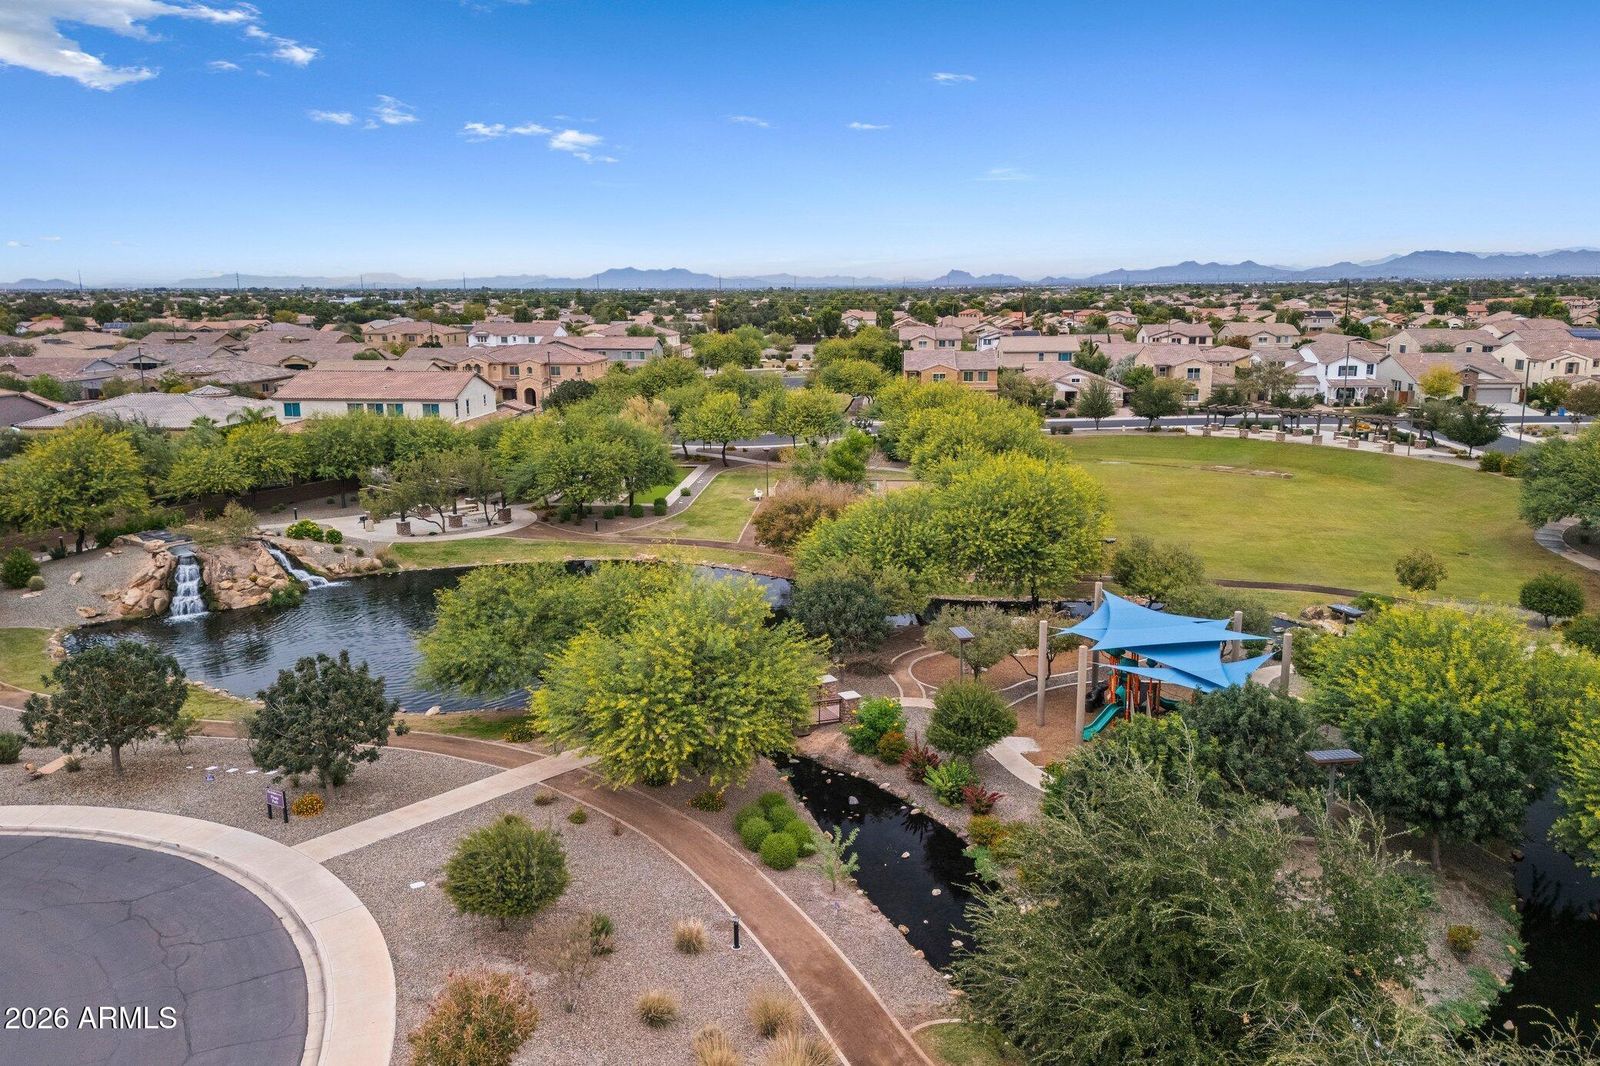
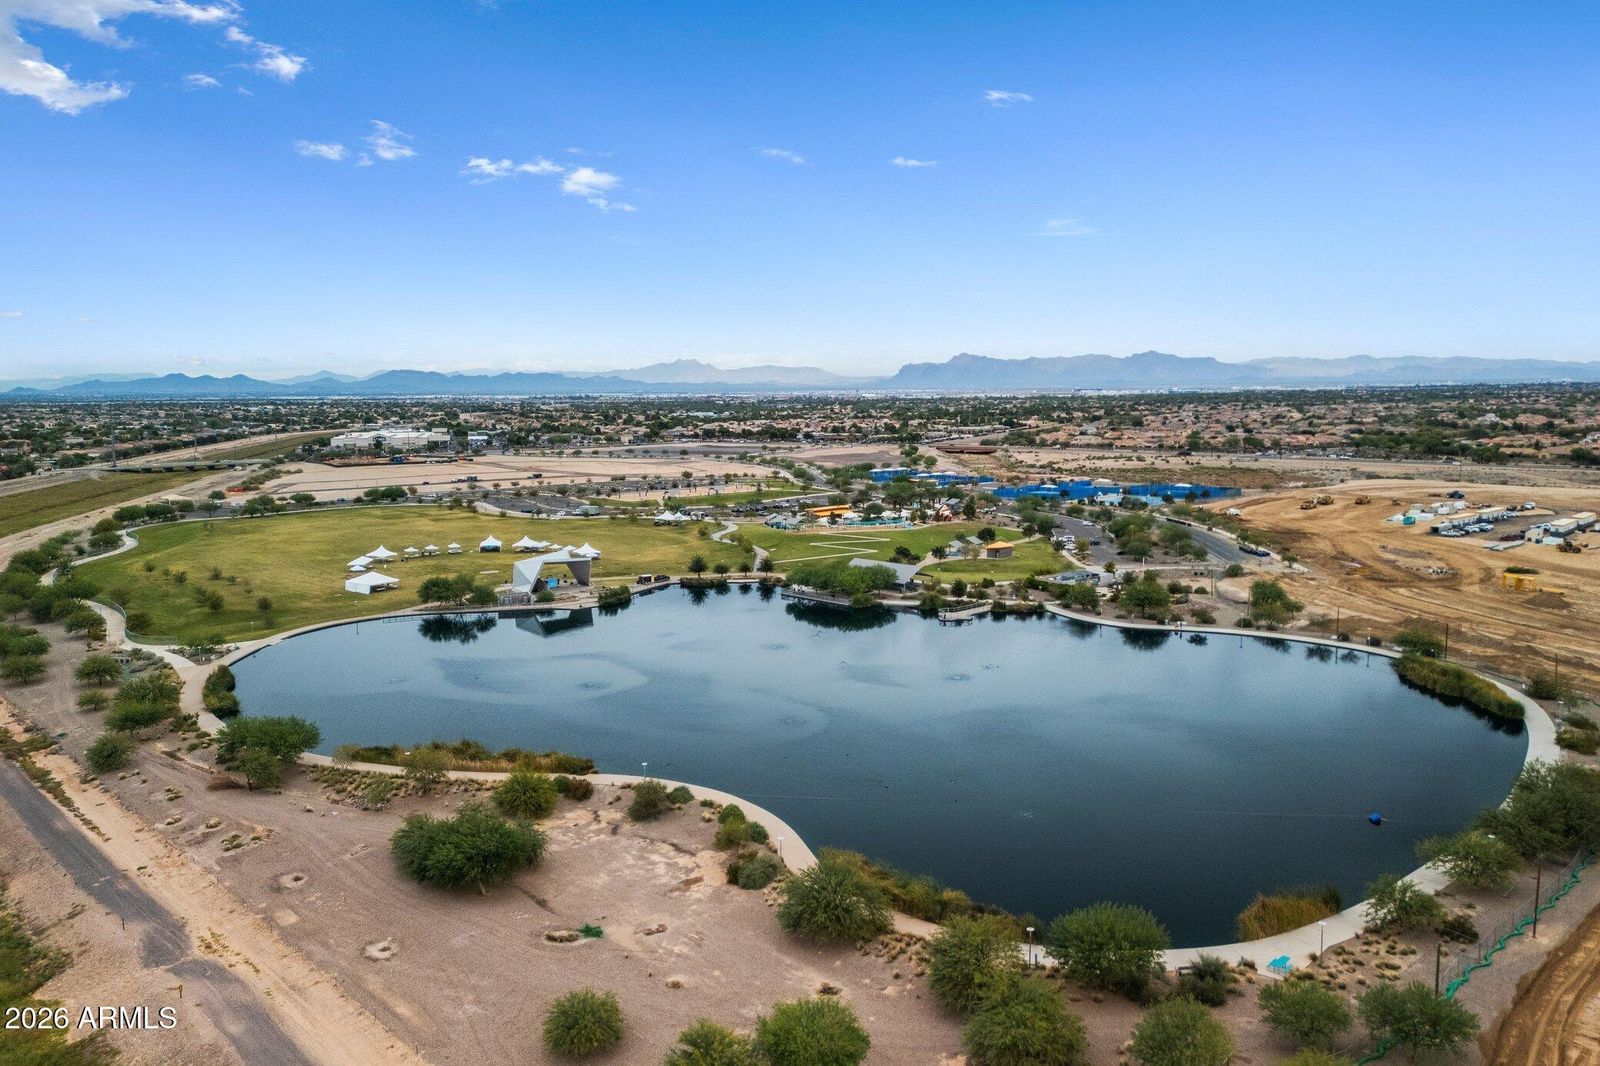
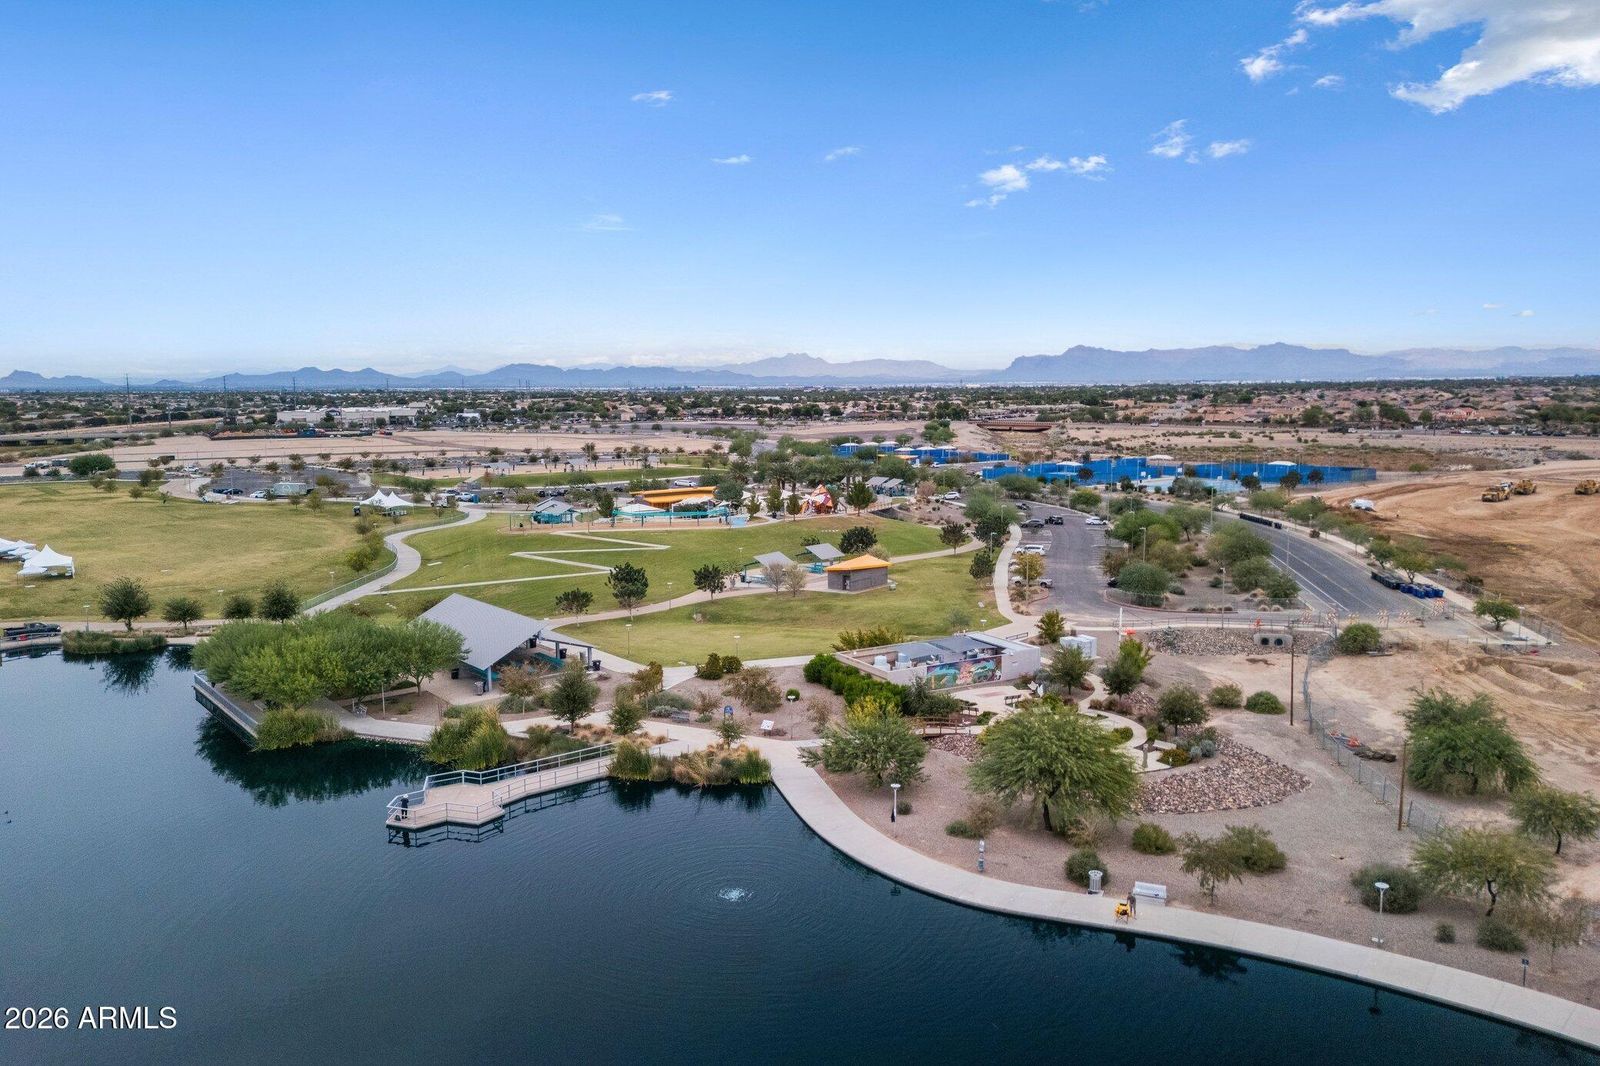
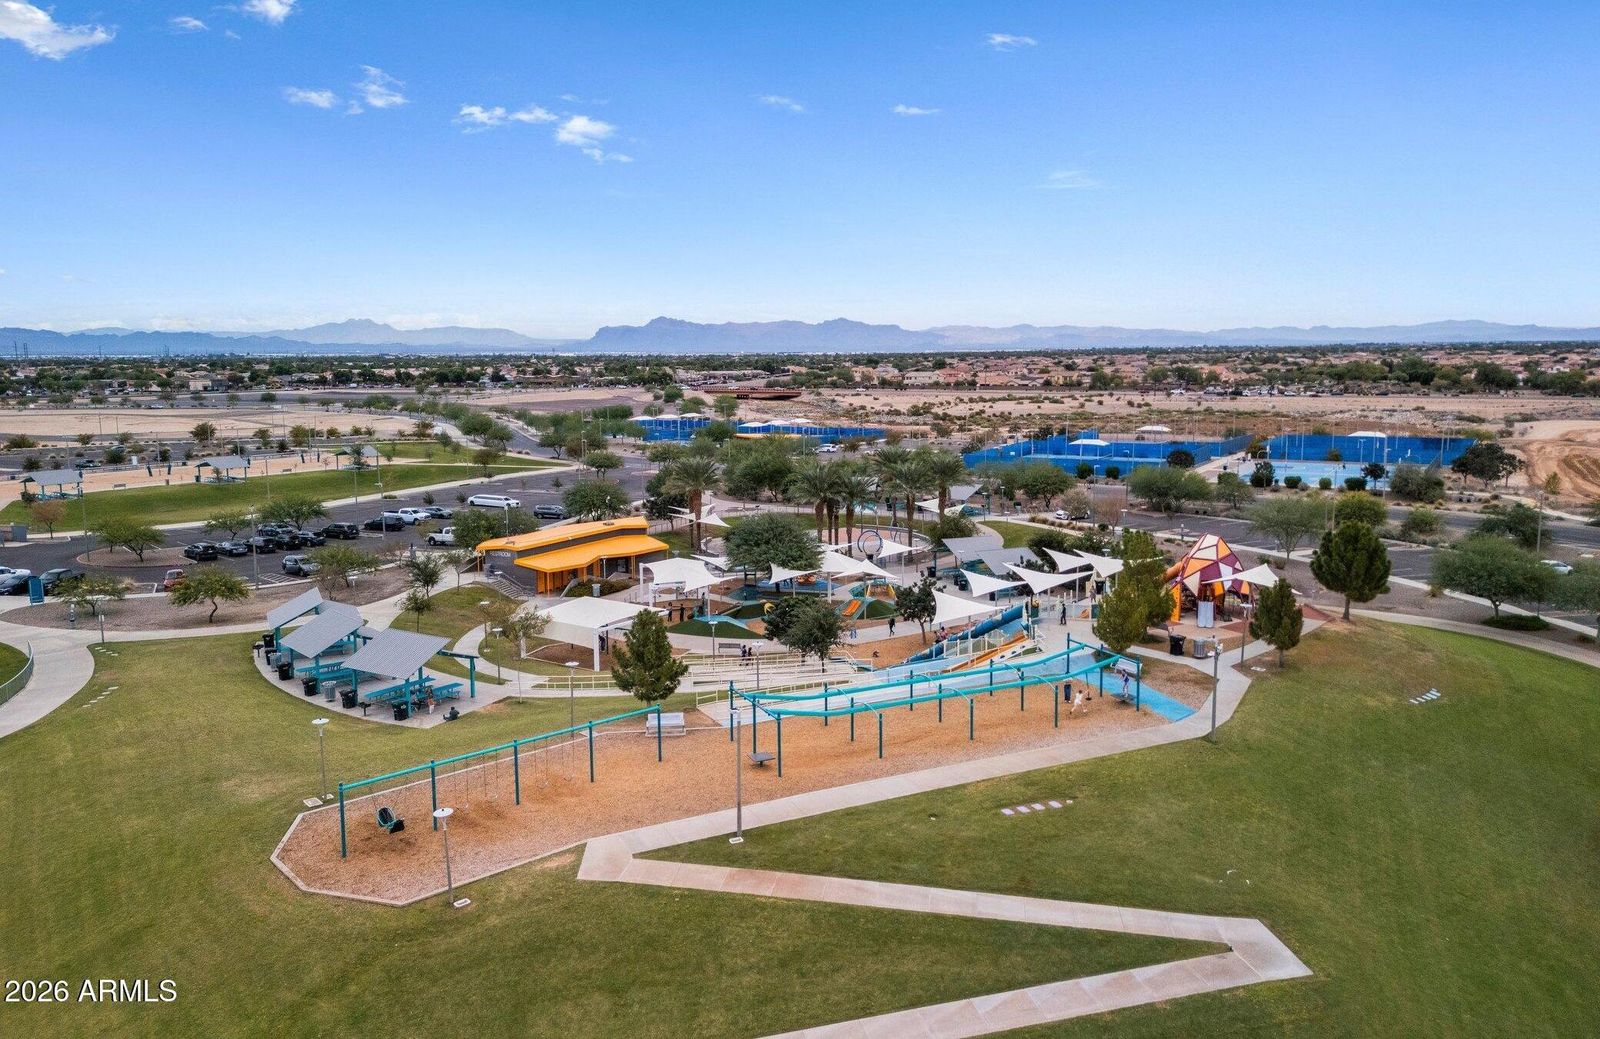
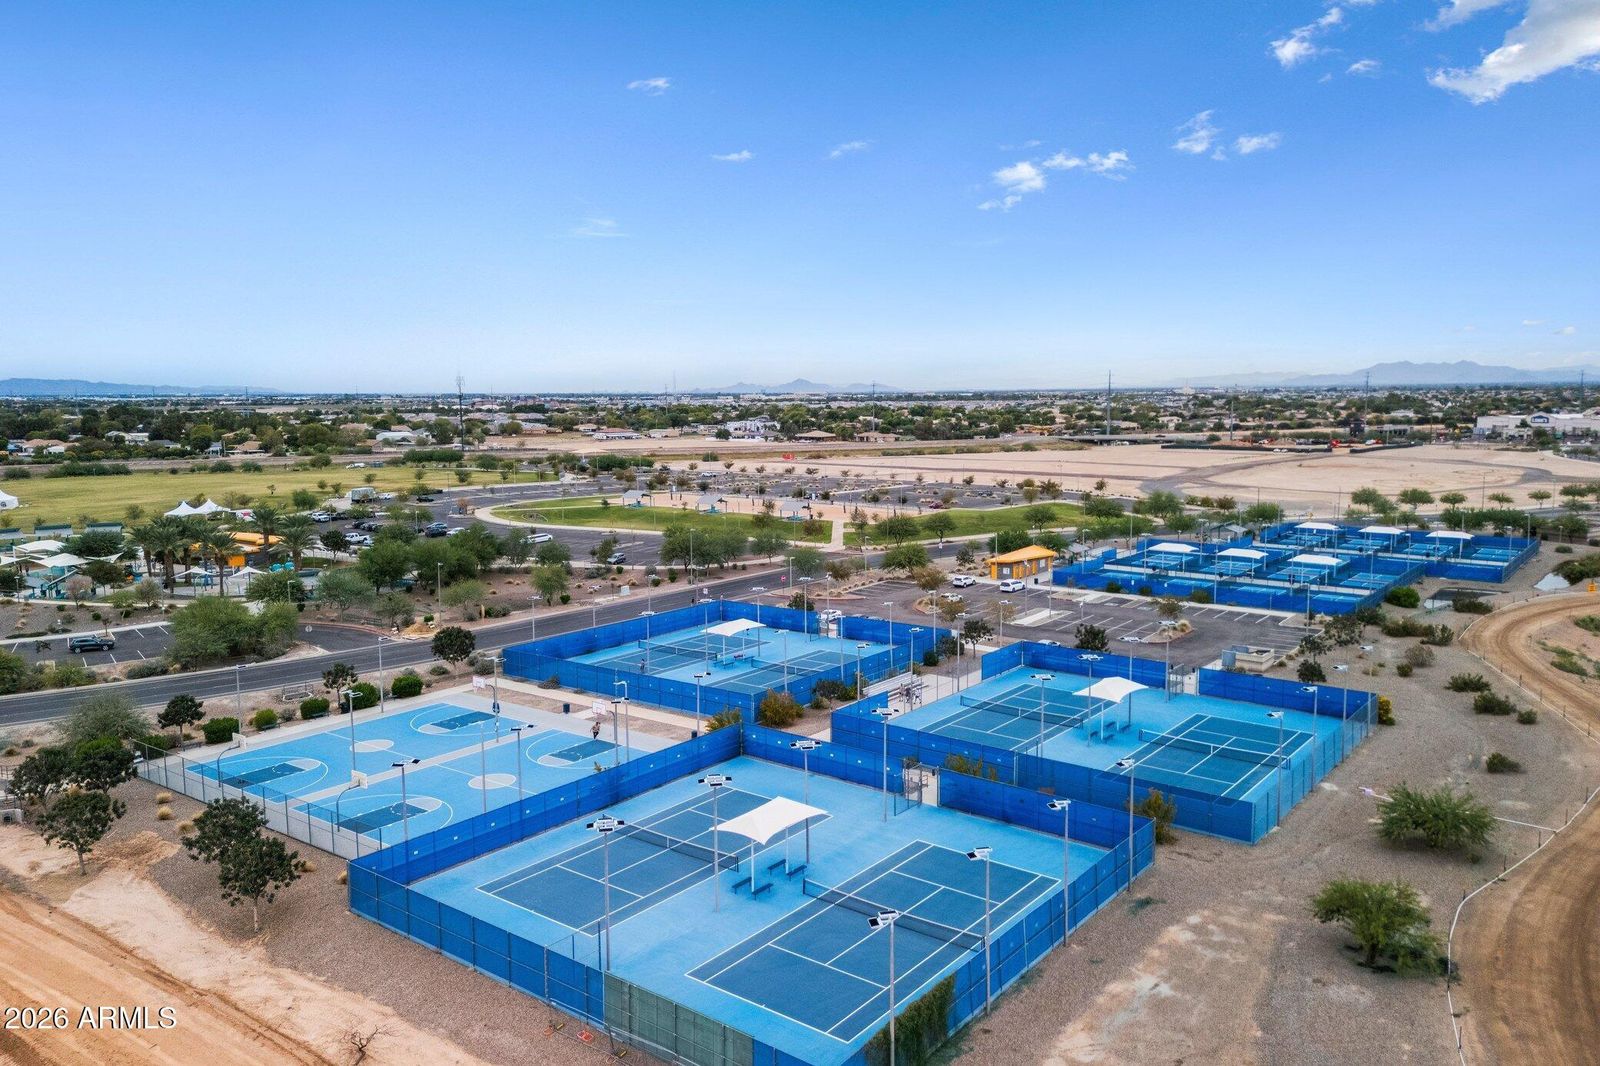
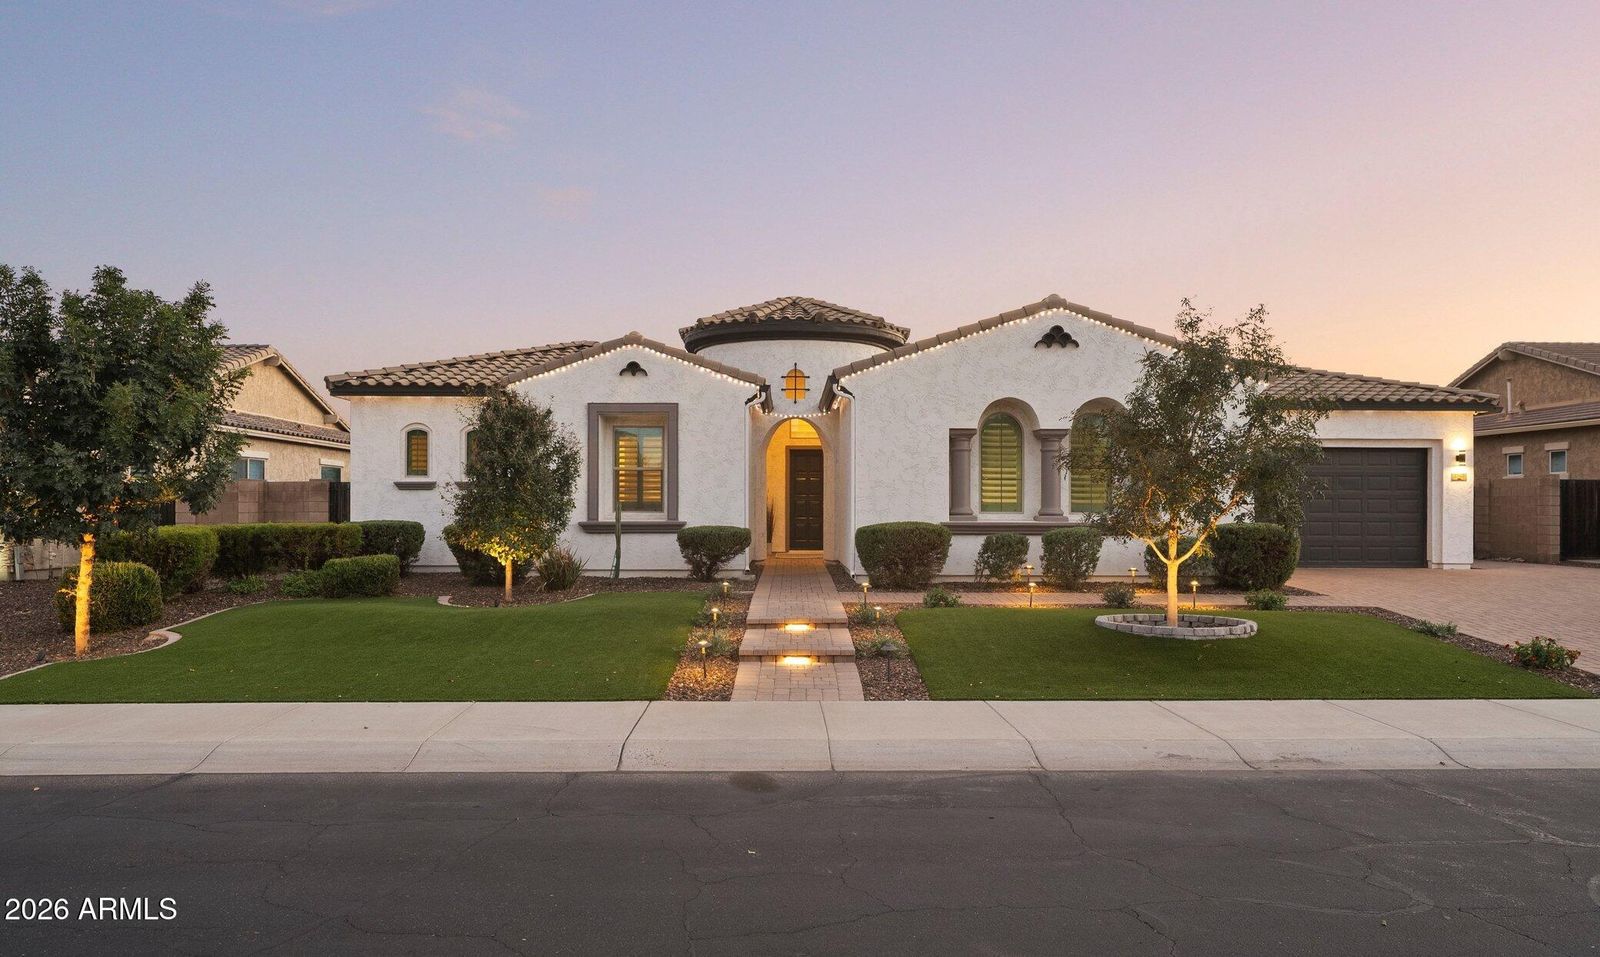
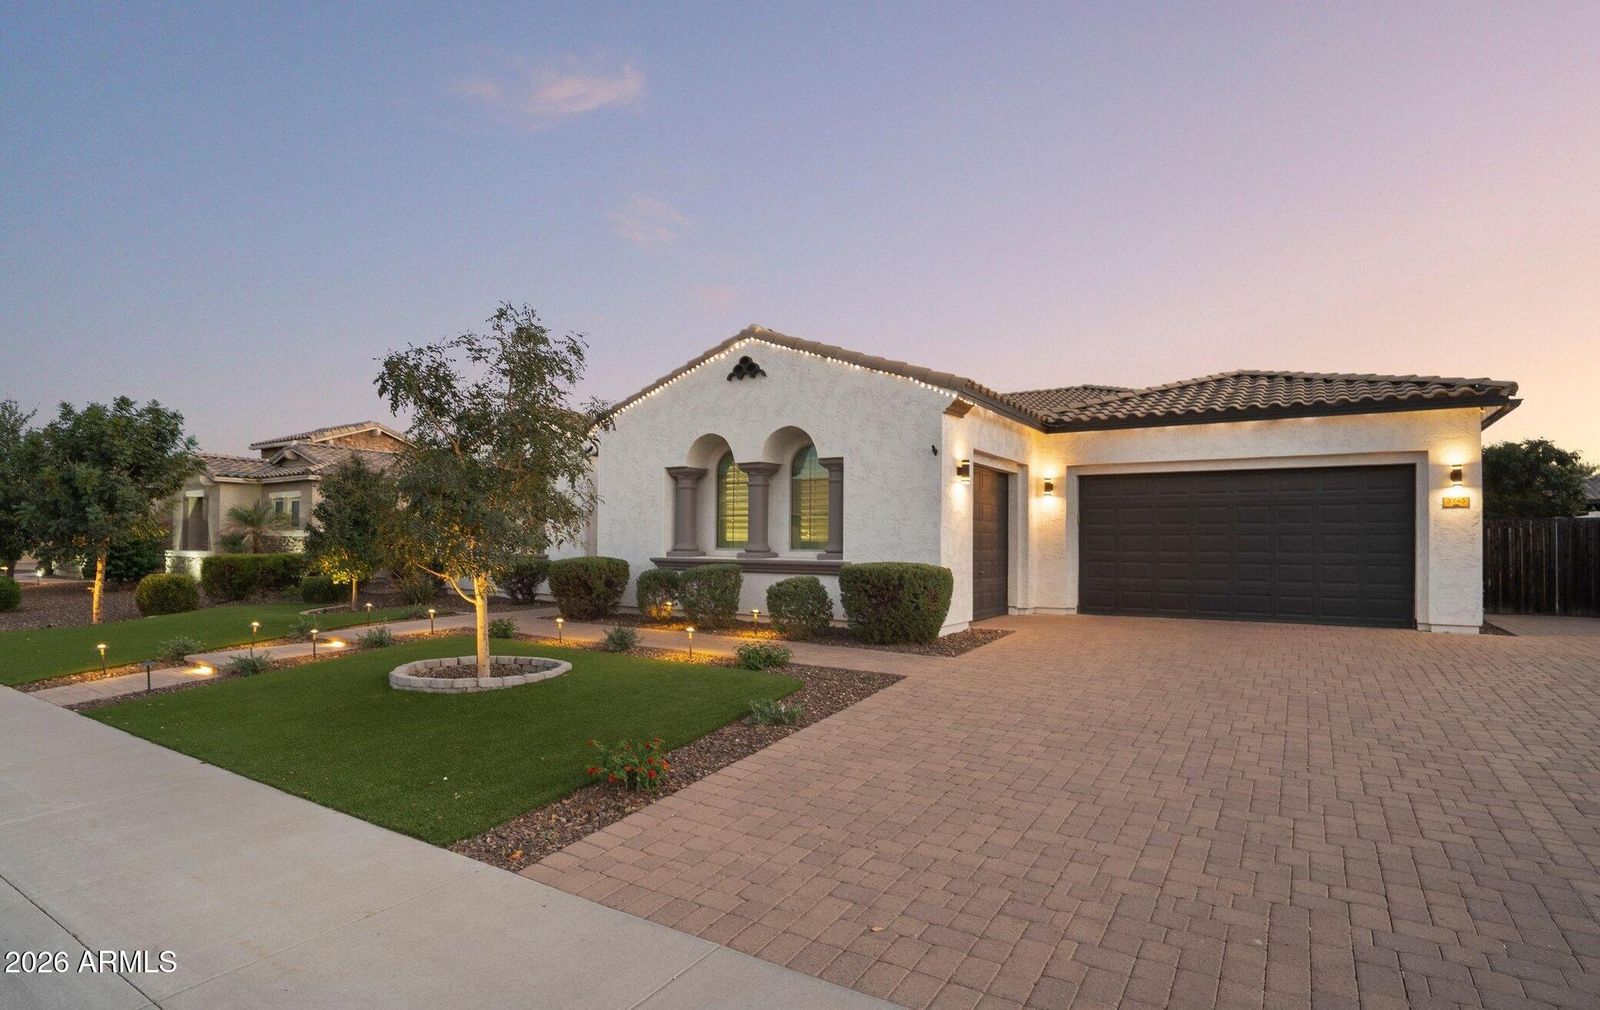
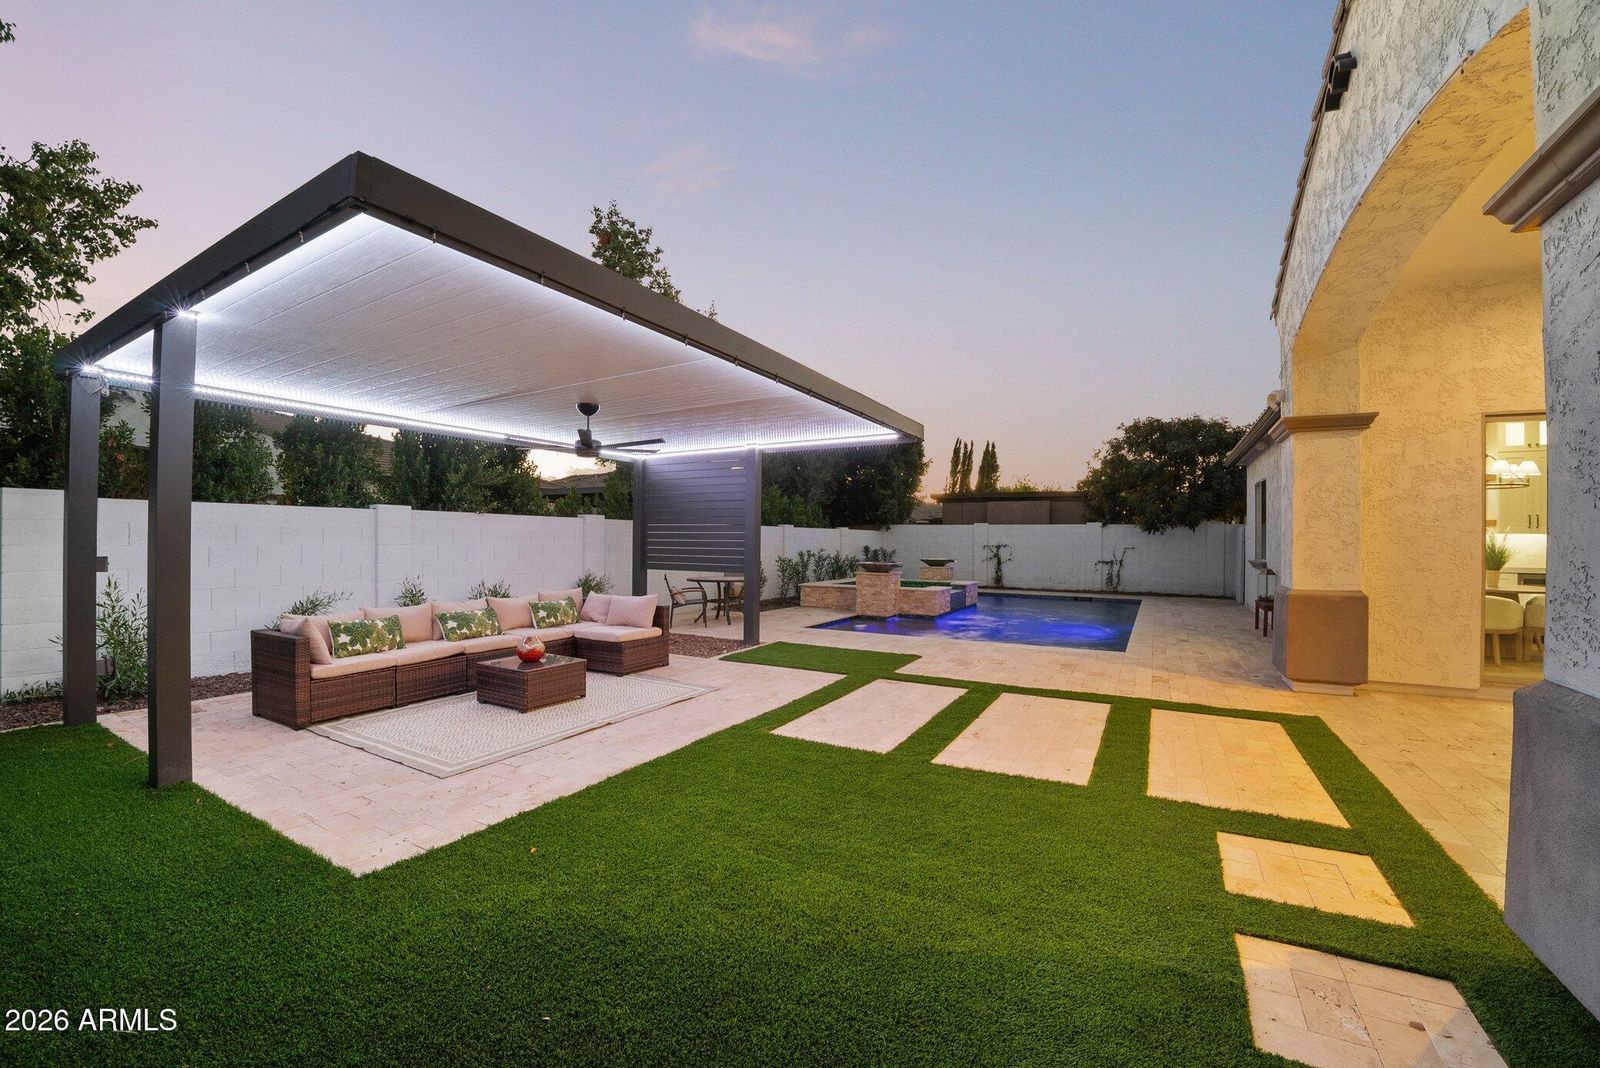
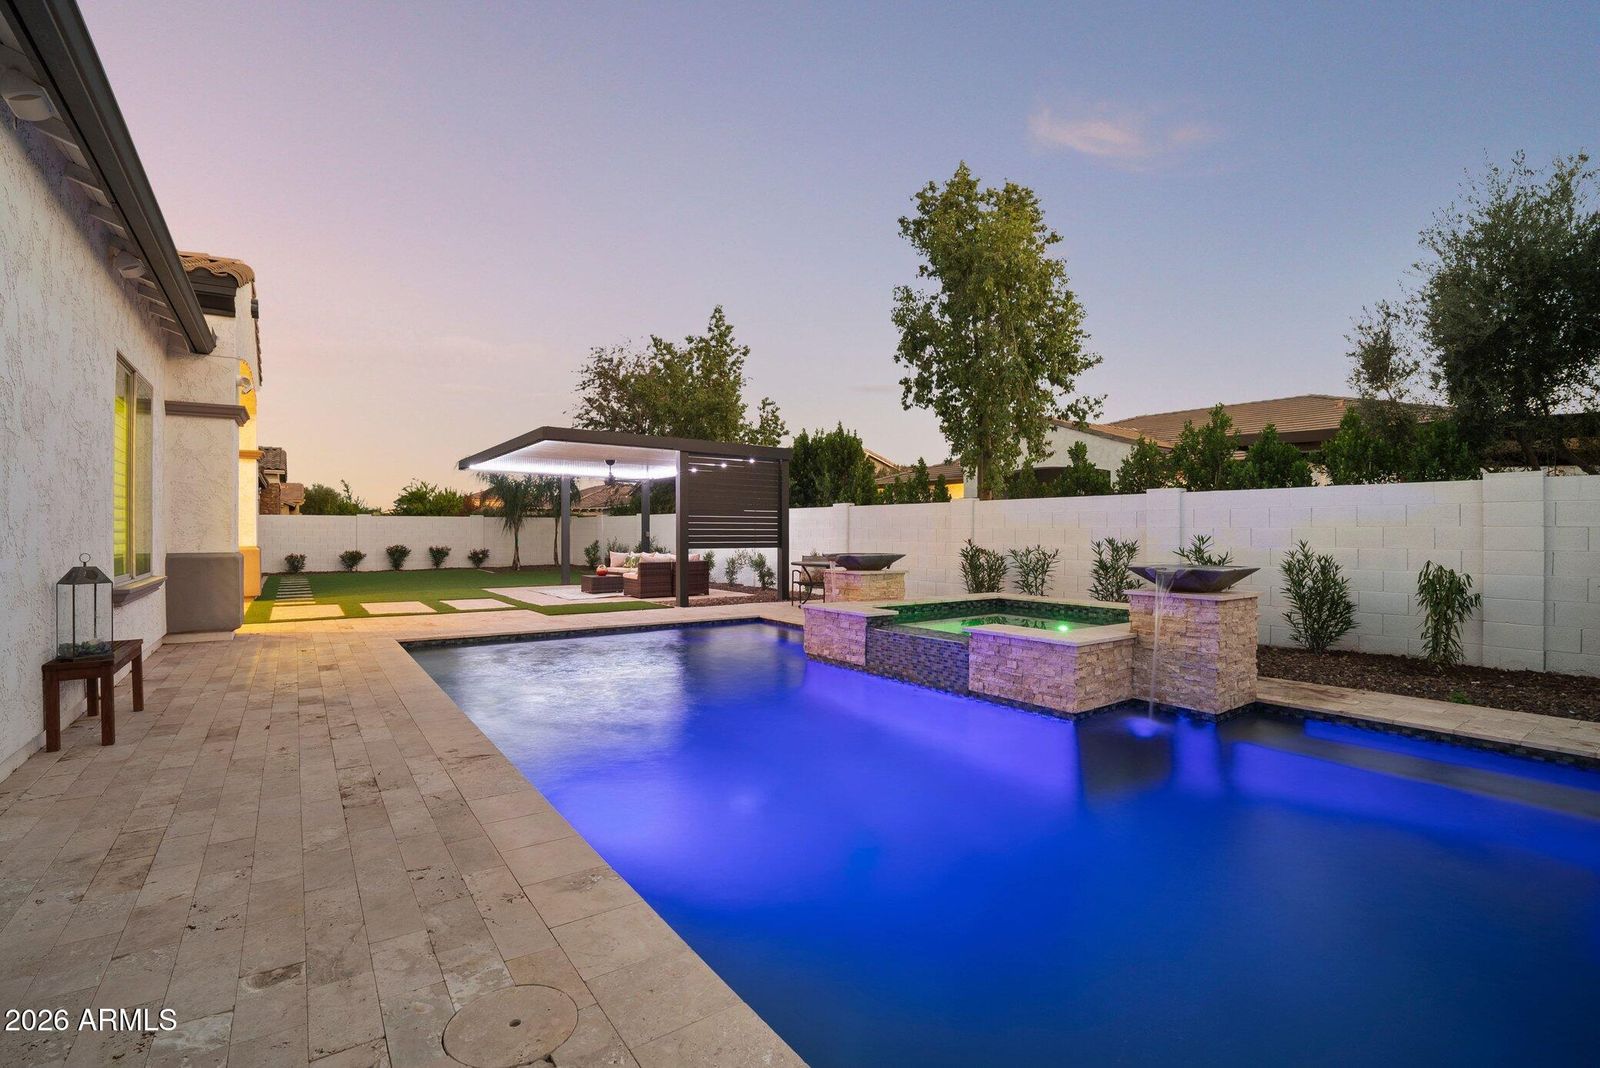
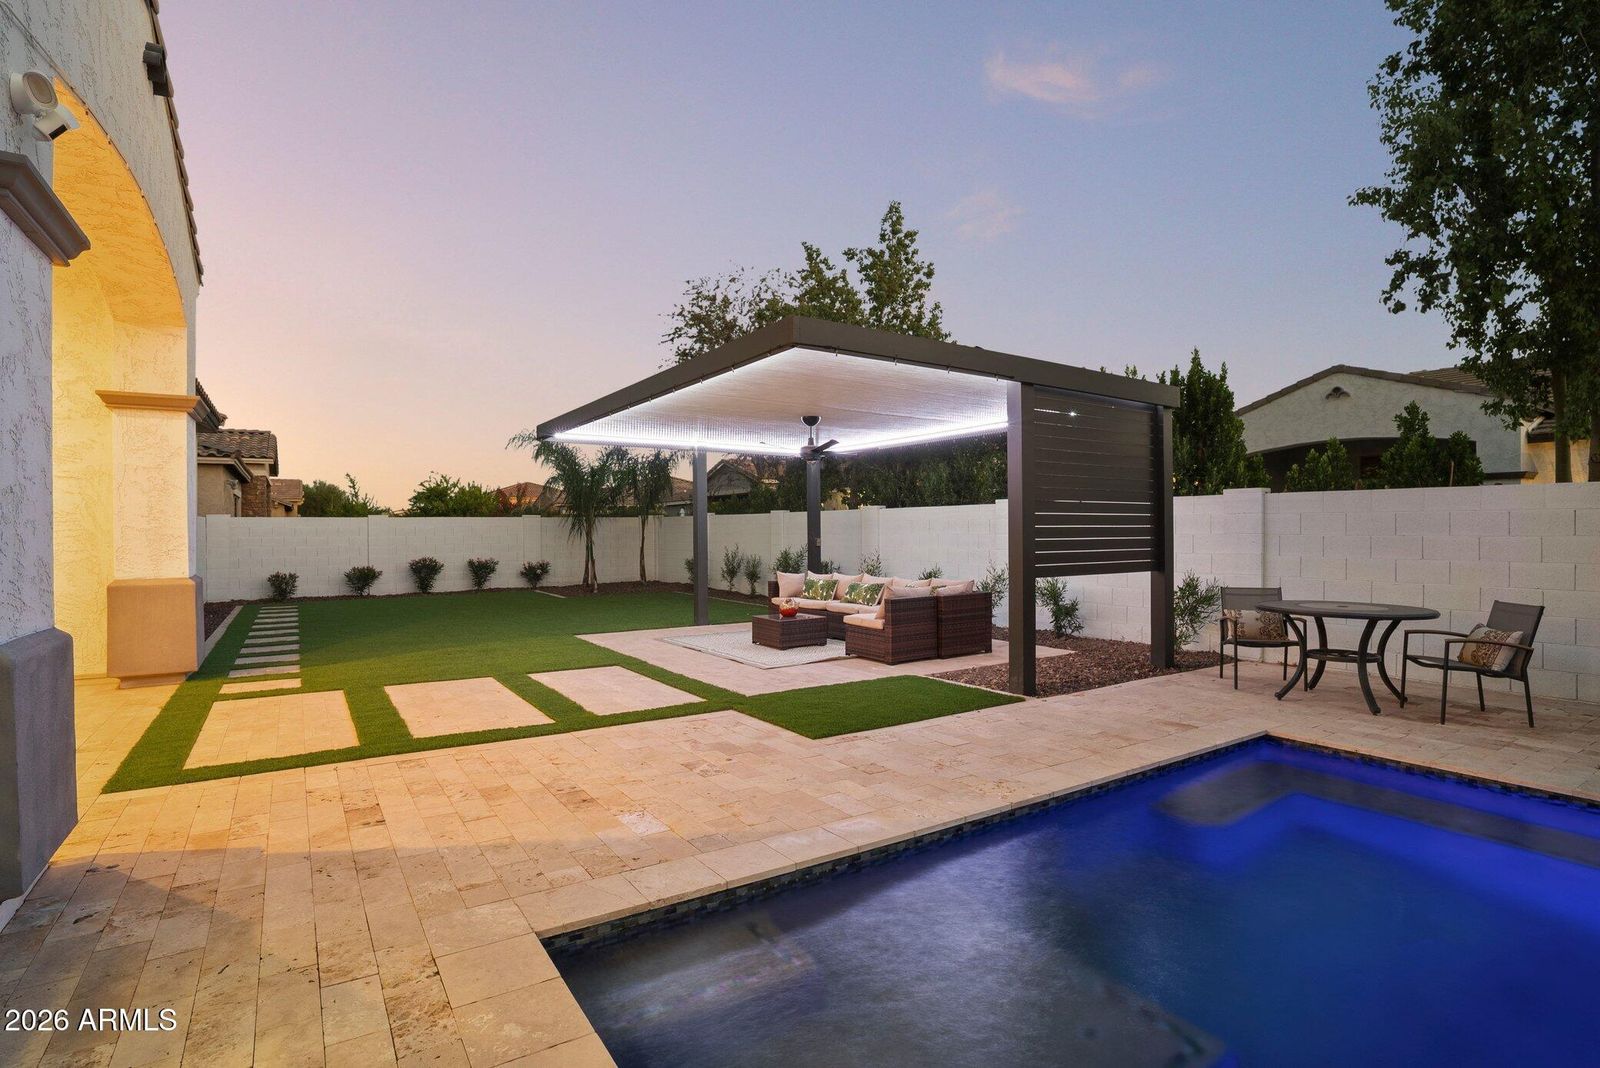
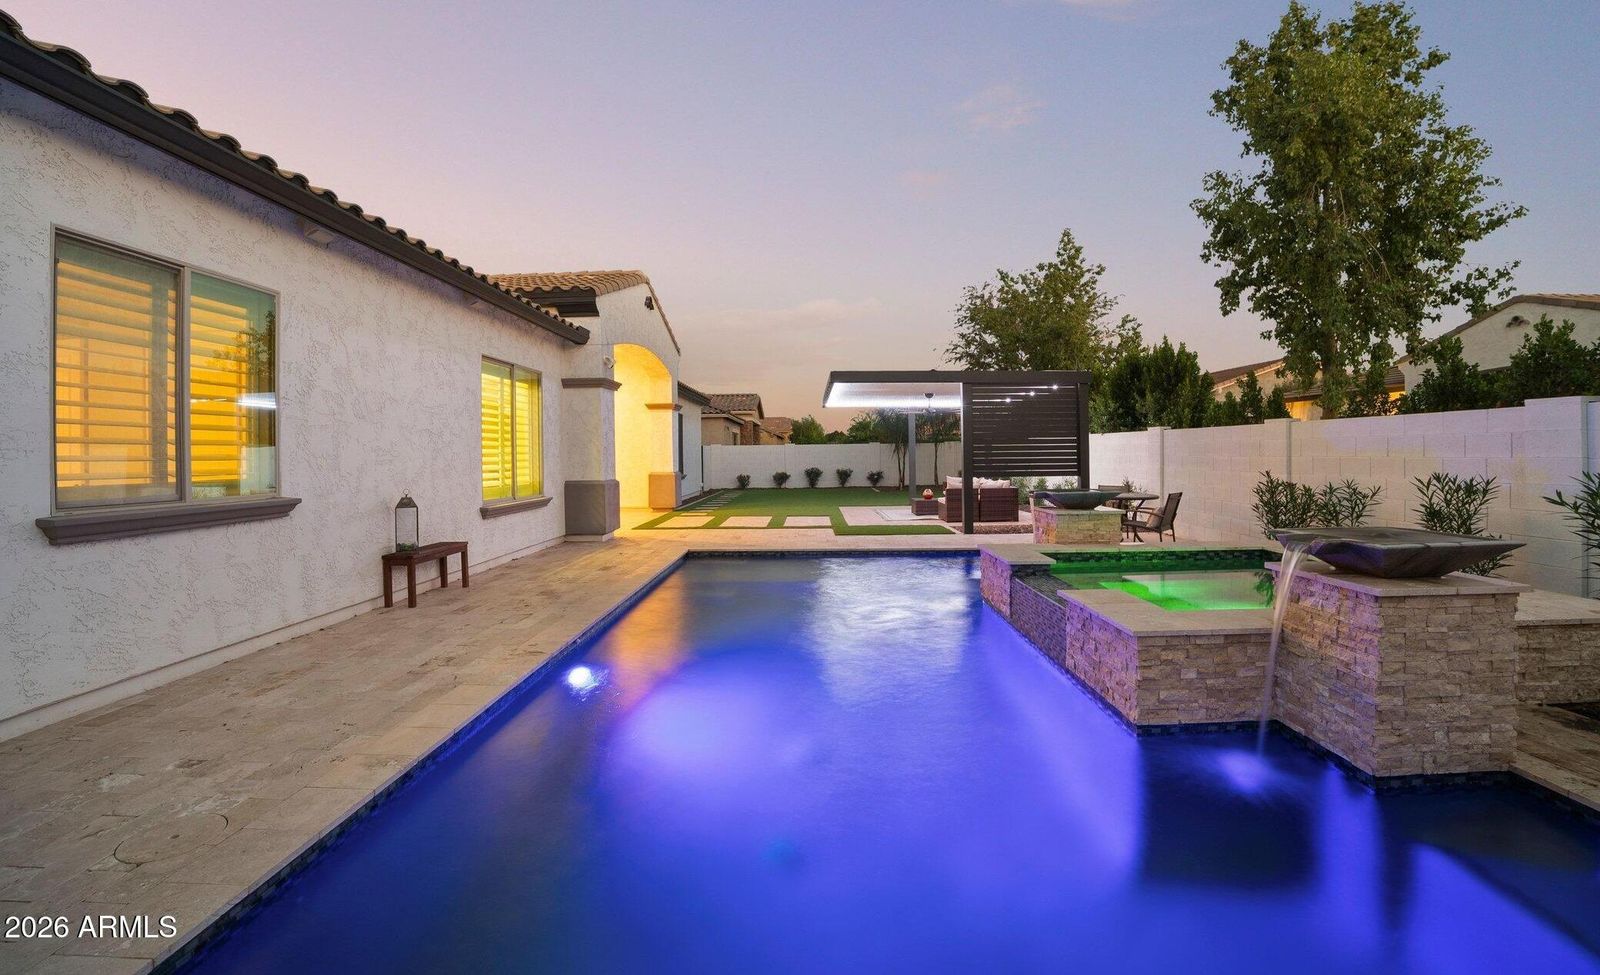
The full listing photo set for 3743 E Strawberry Dr, all 74 photos. The remodeled kitchen and great room, the primary suite, the heated pool and spa with its covered pergola, and the Bridges lakes and Gilbert Regional Park aerials are all here.
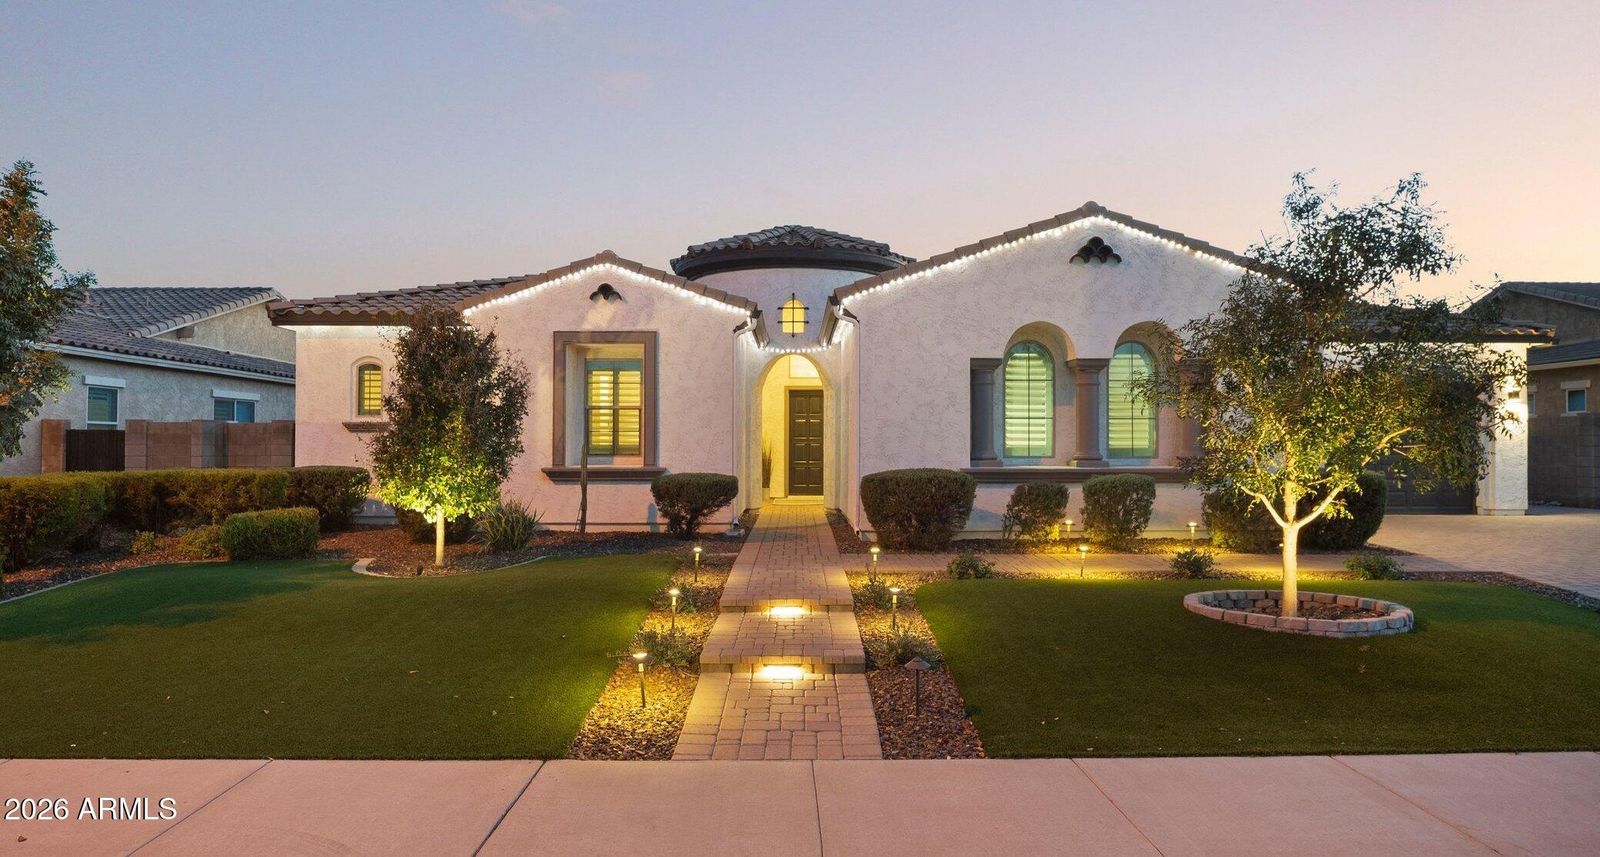
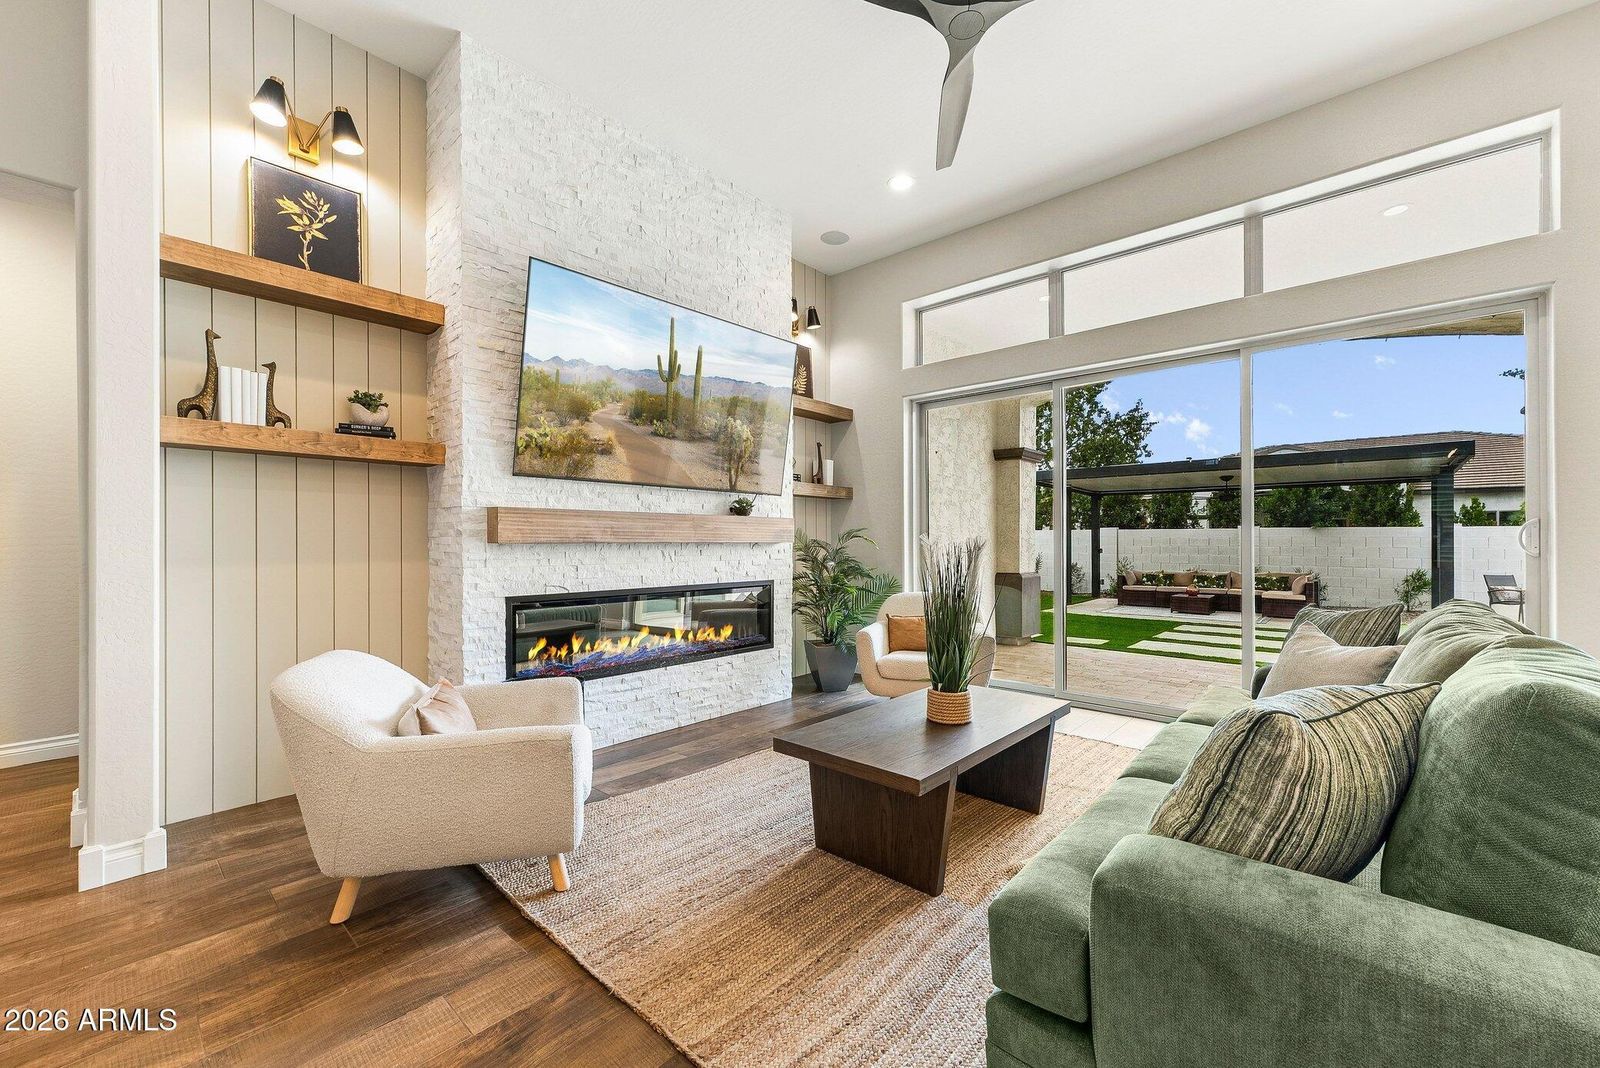
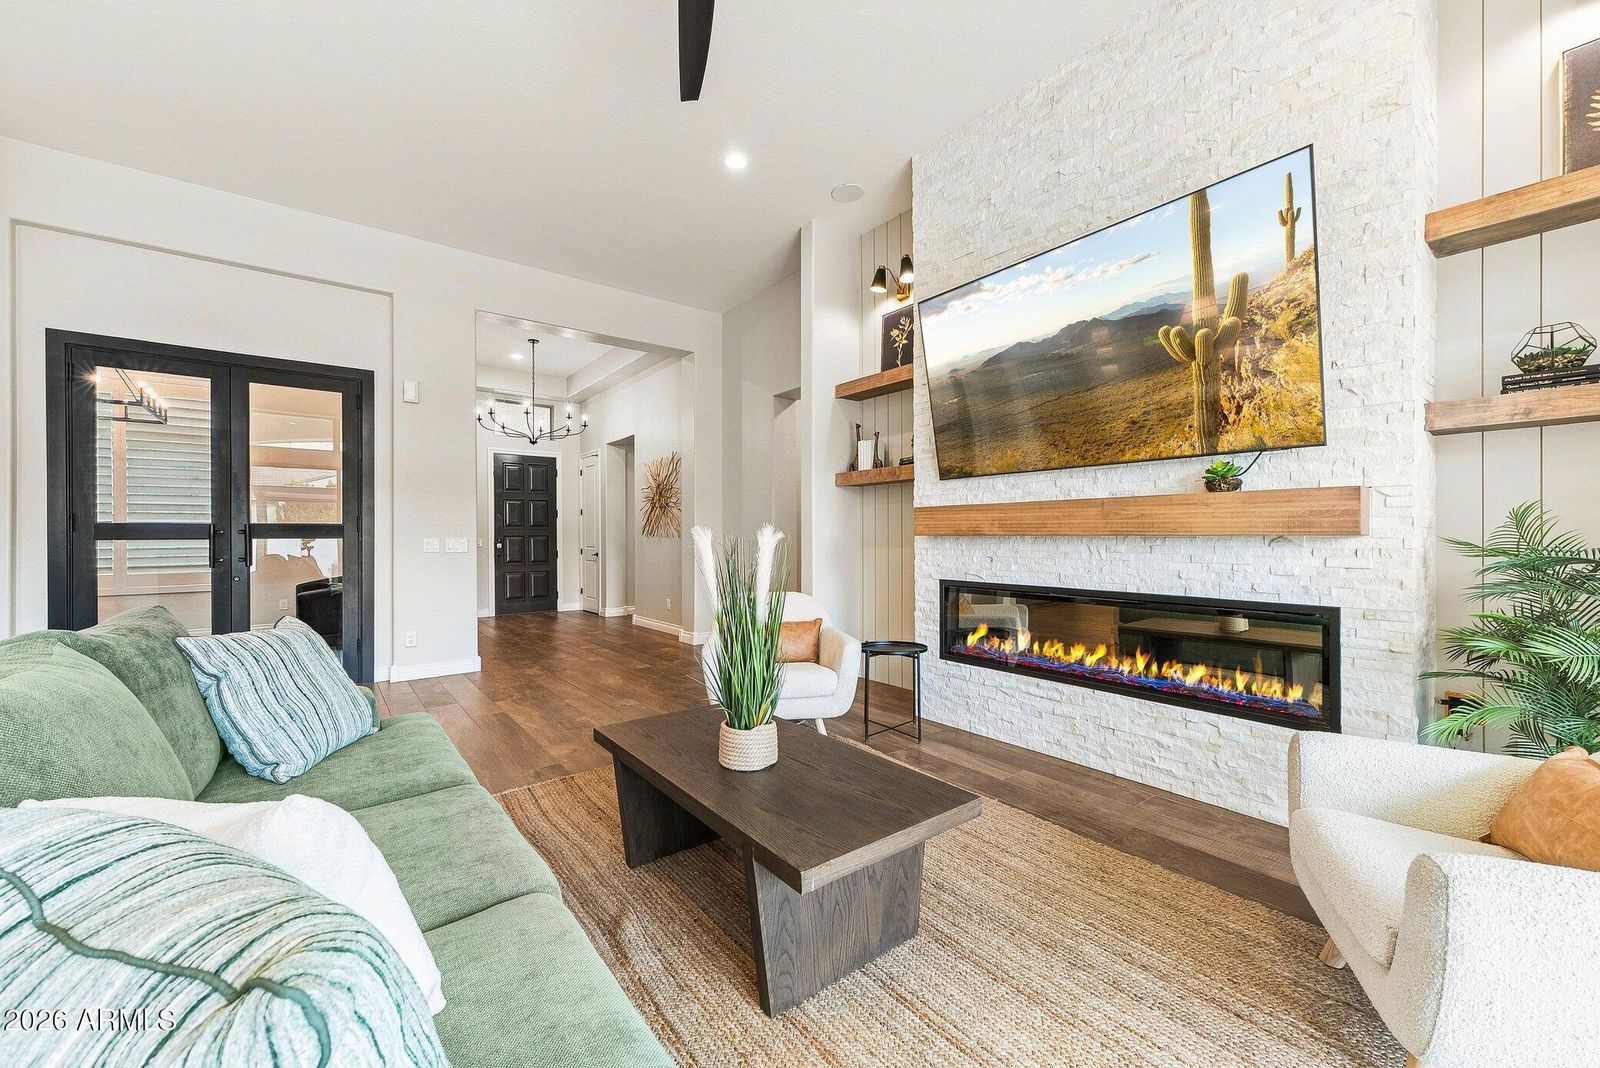
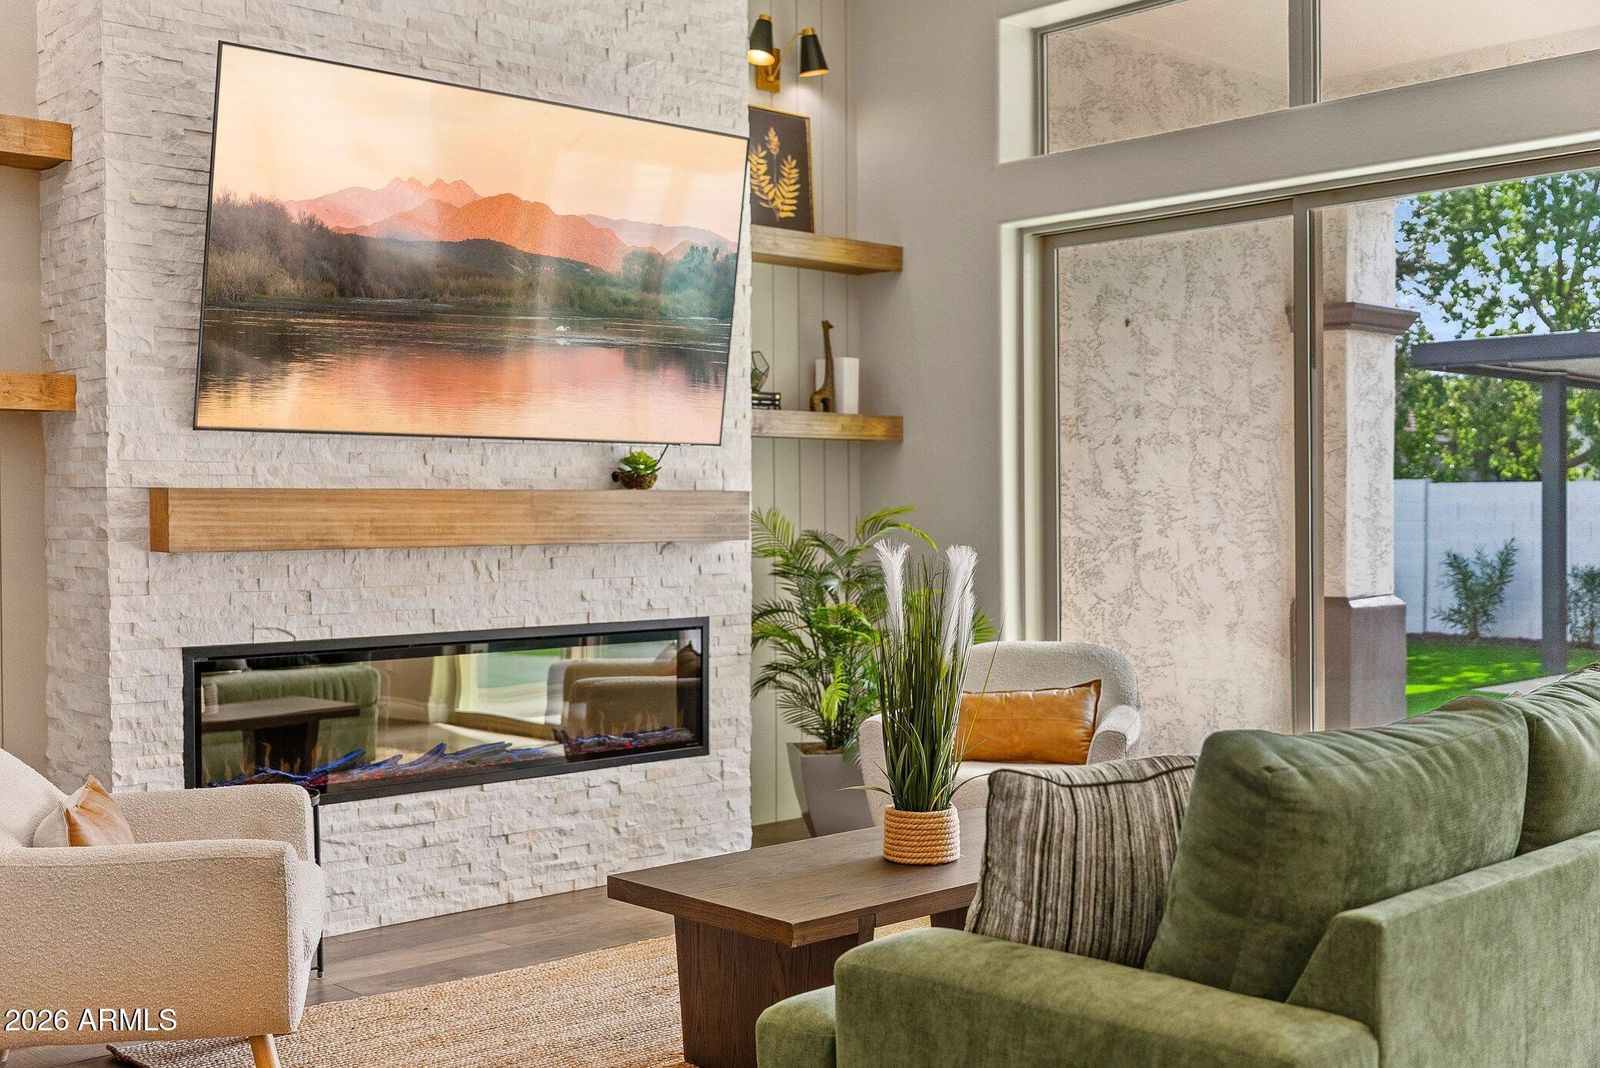
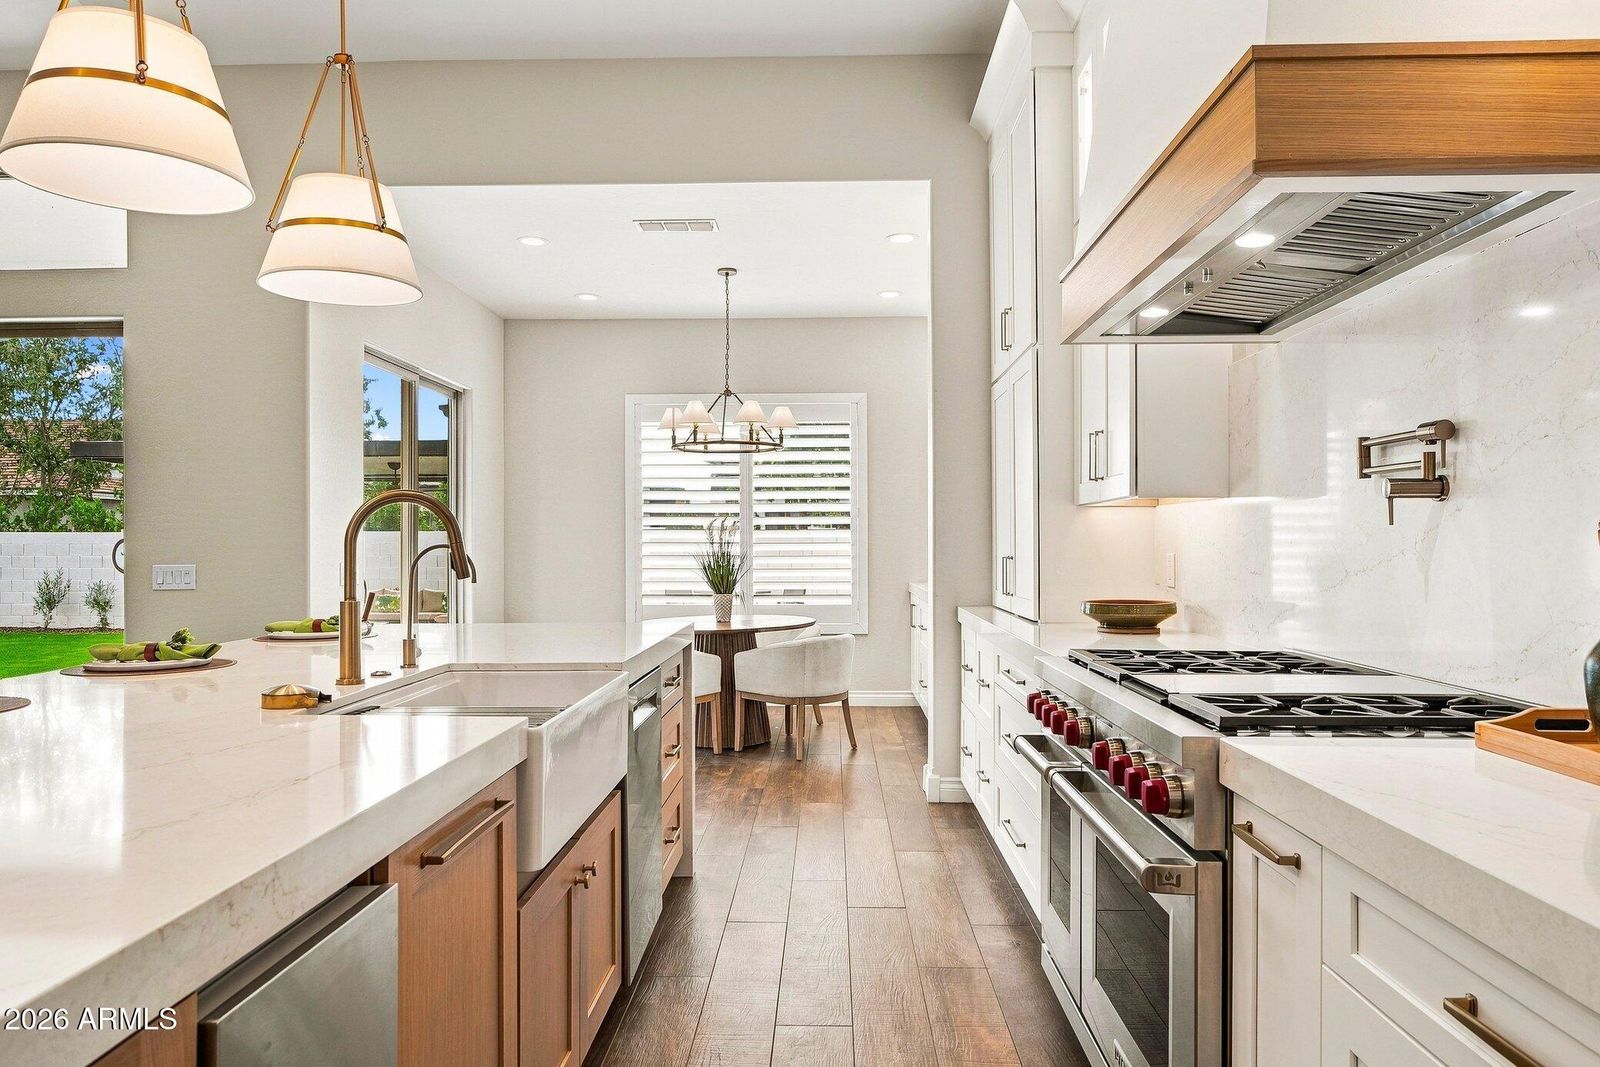
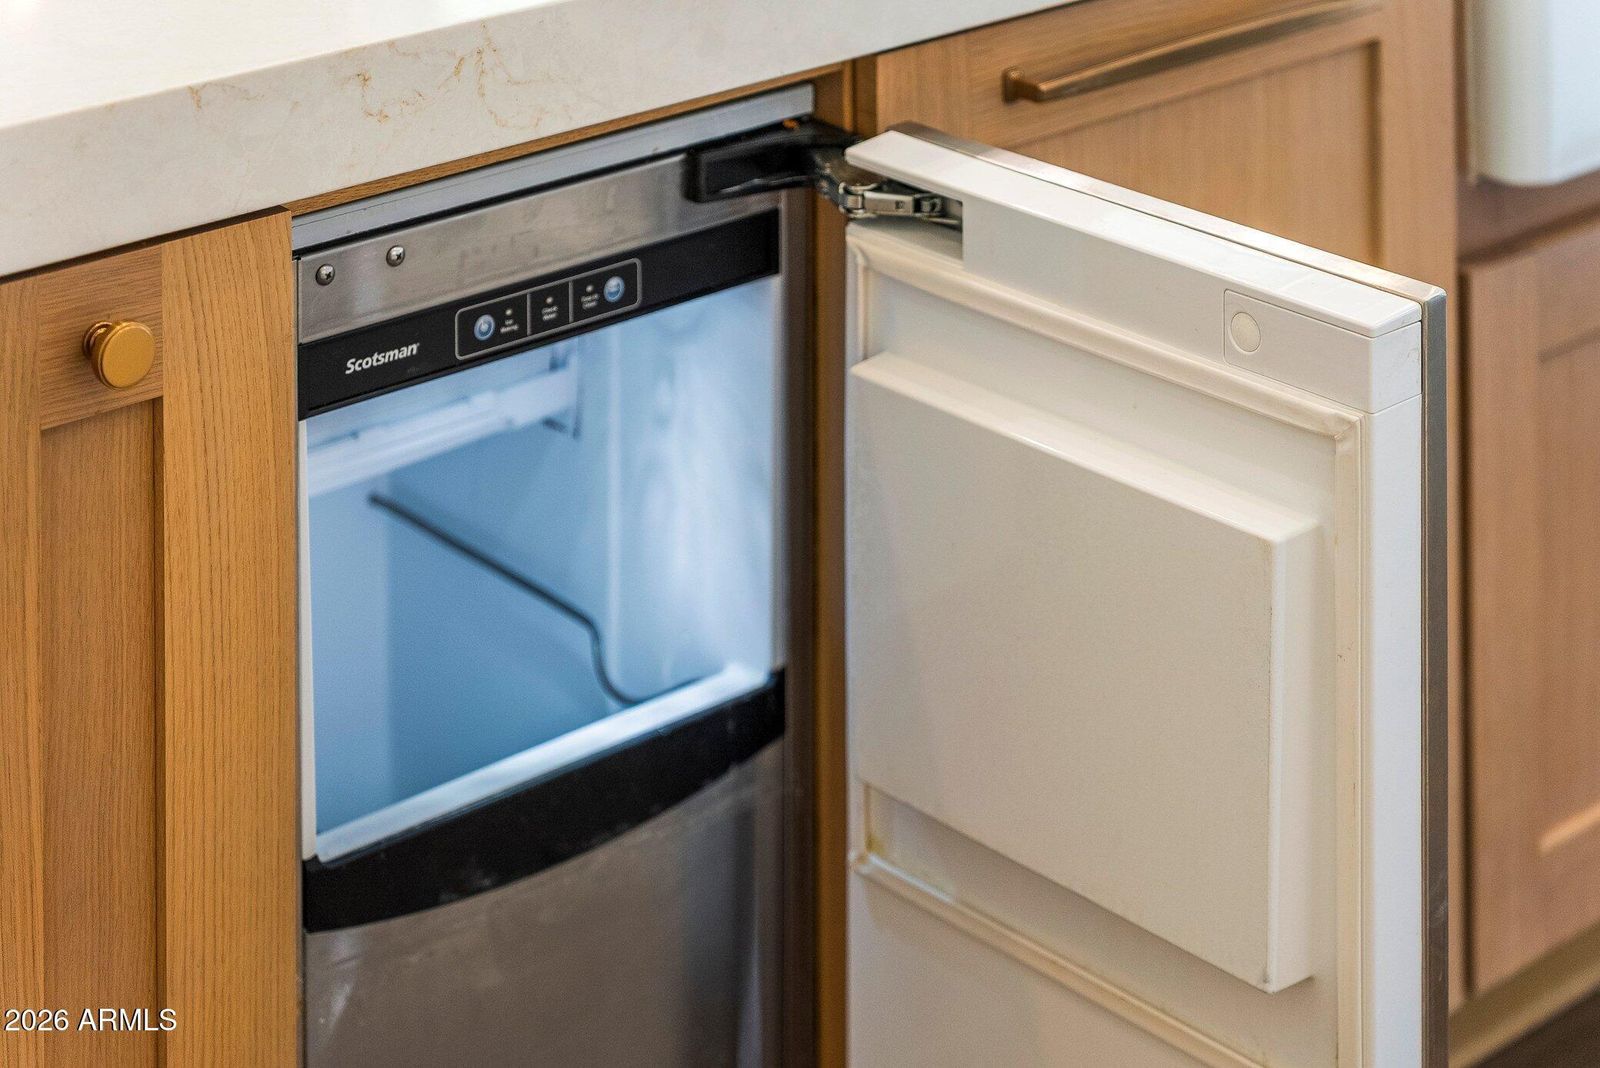
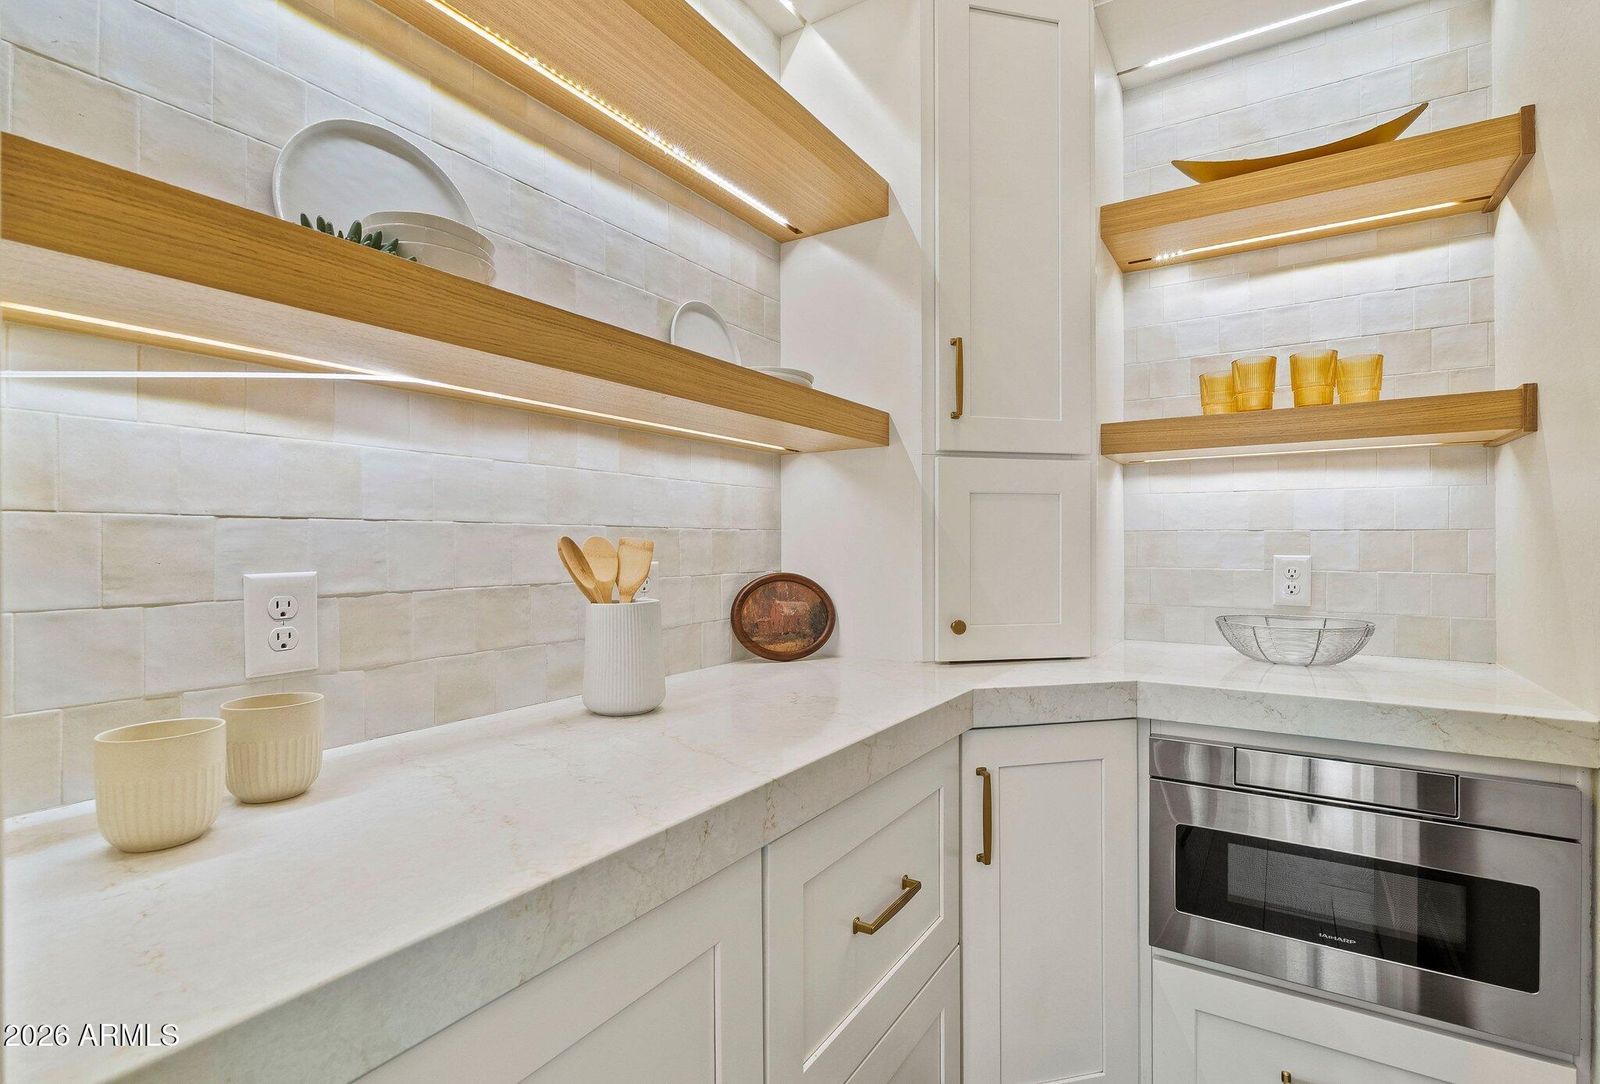
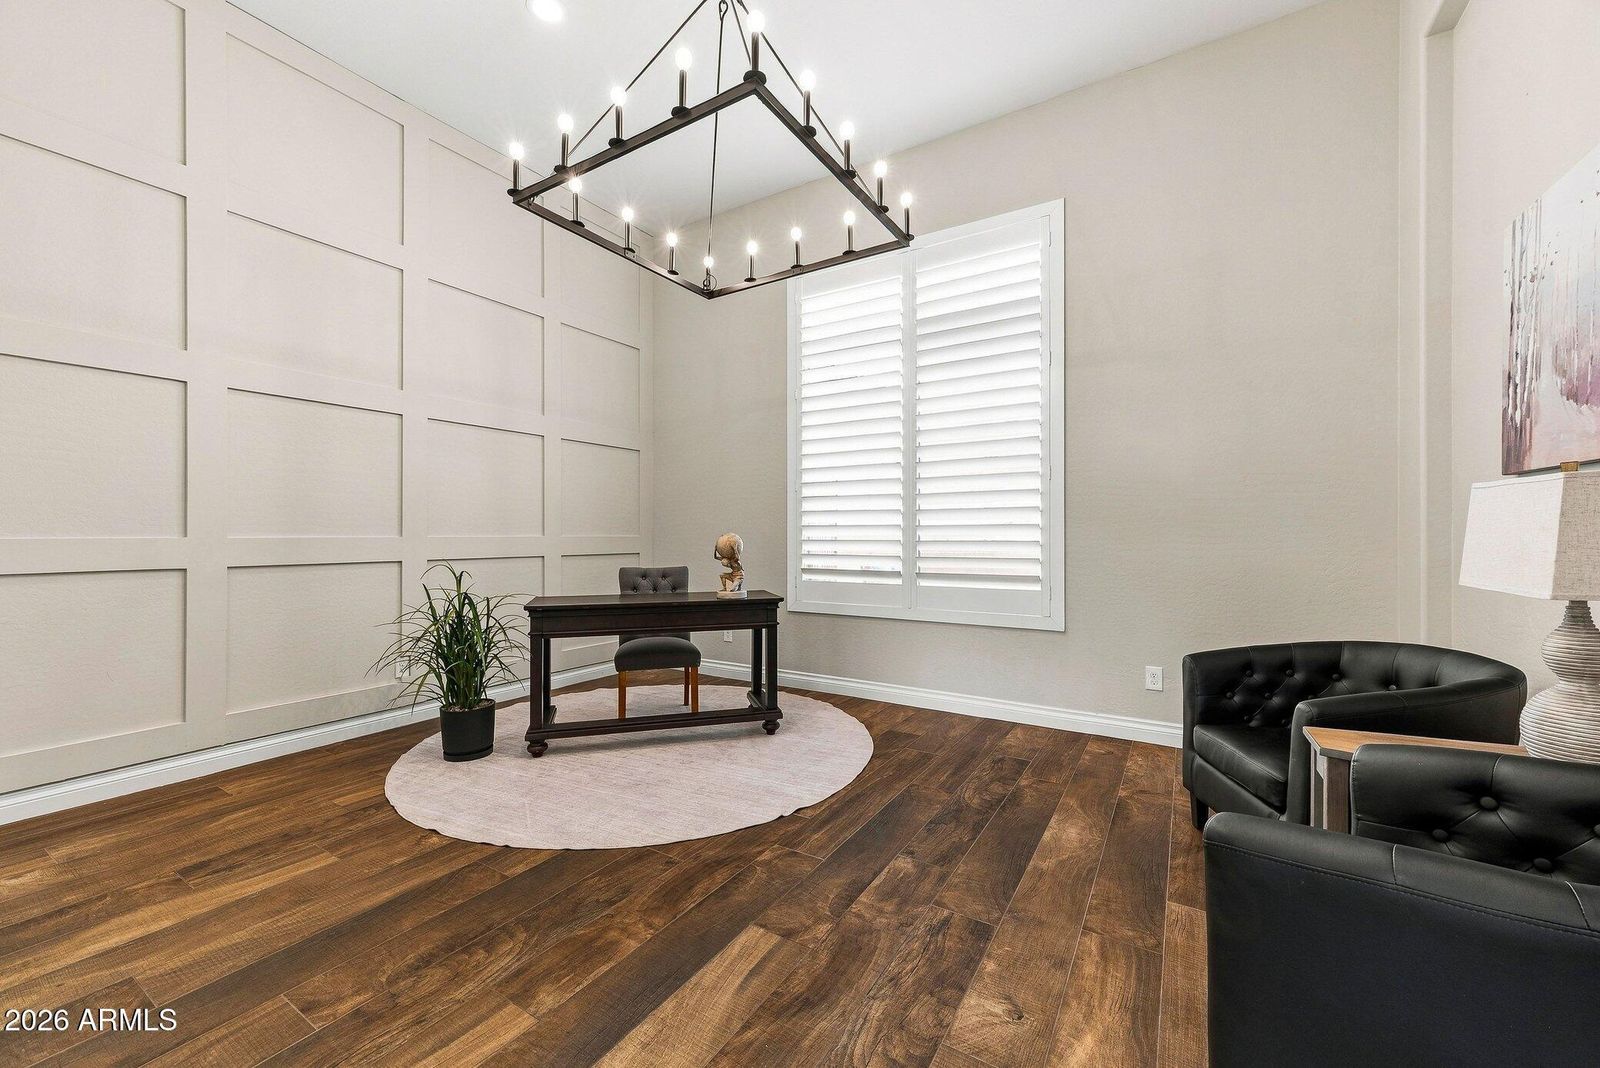
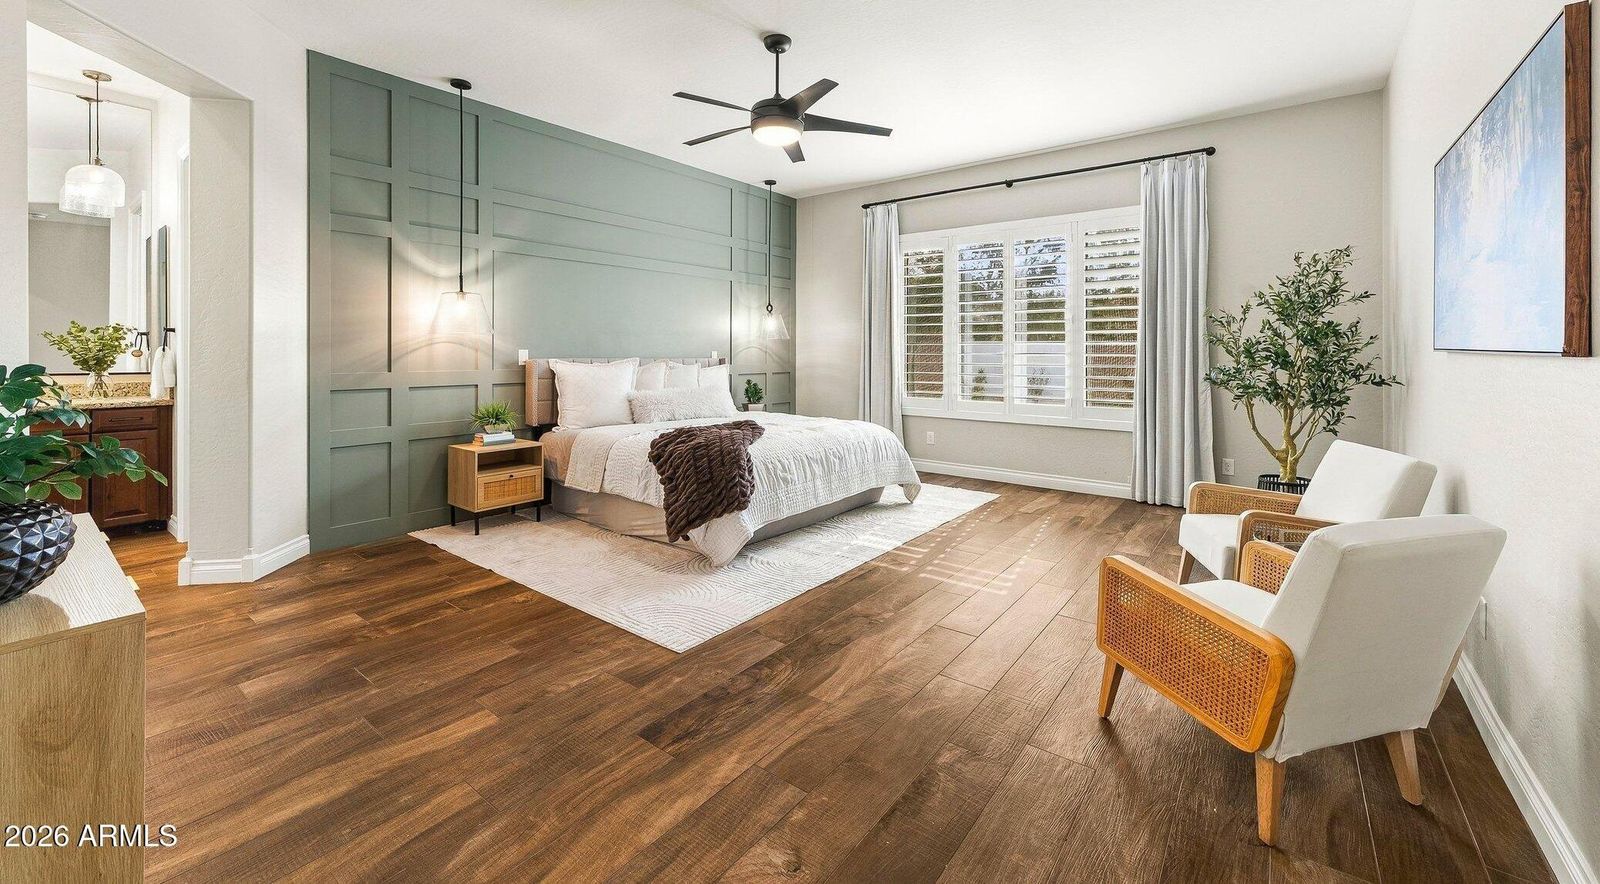
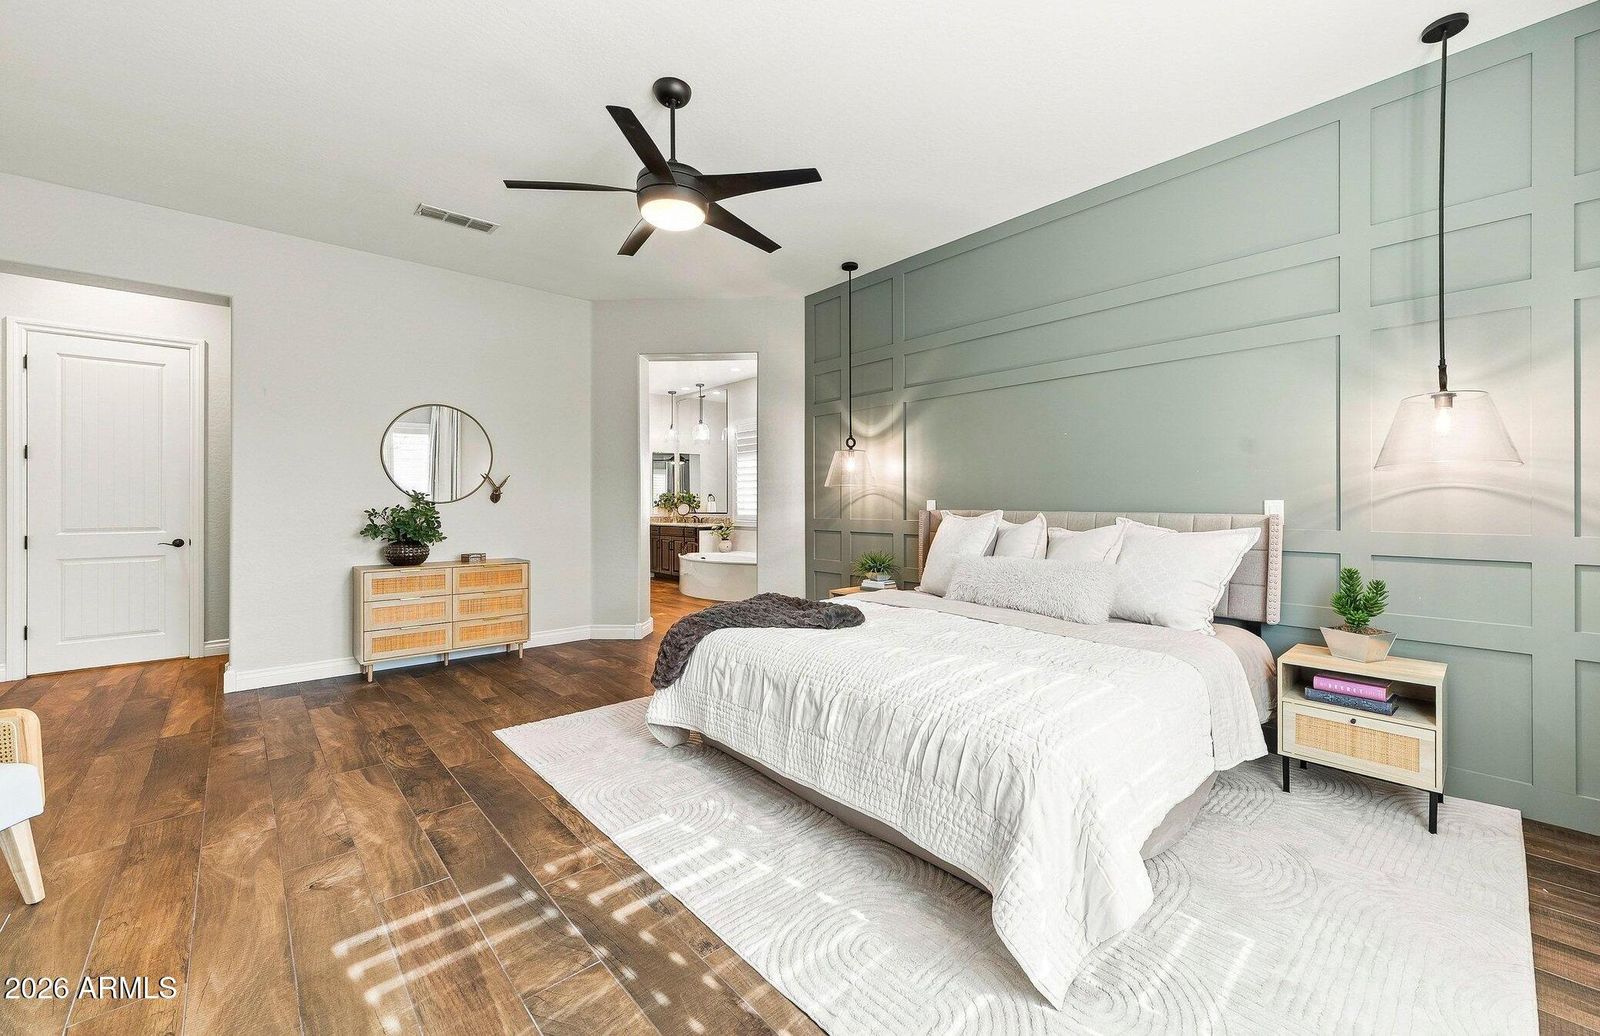
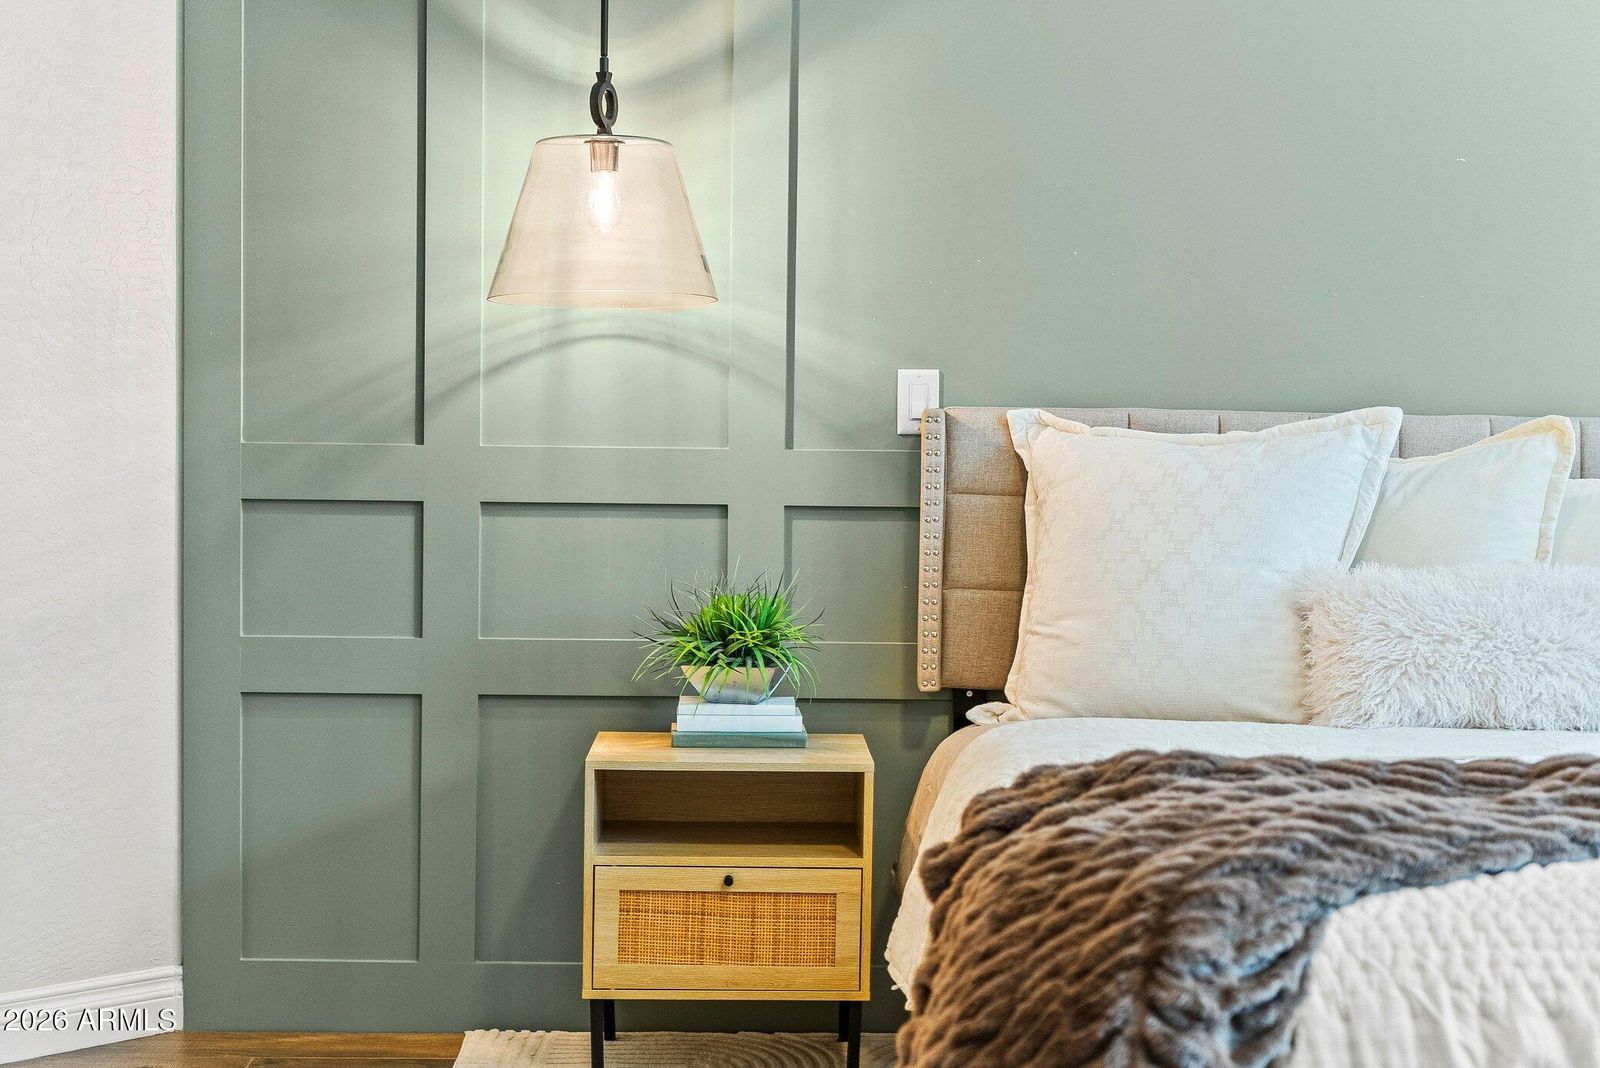
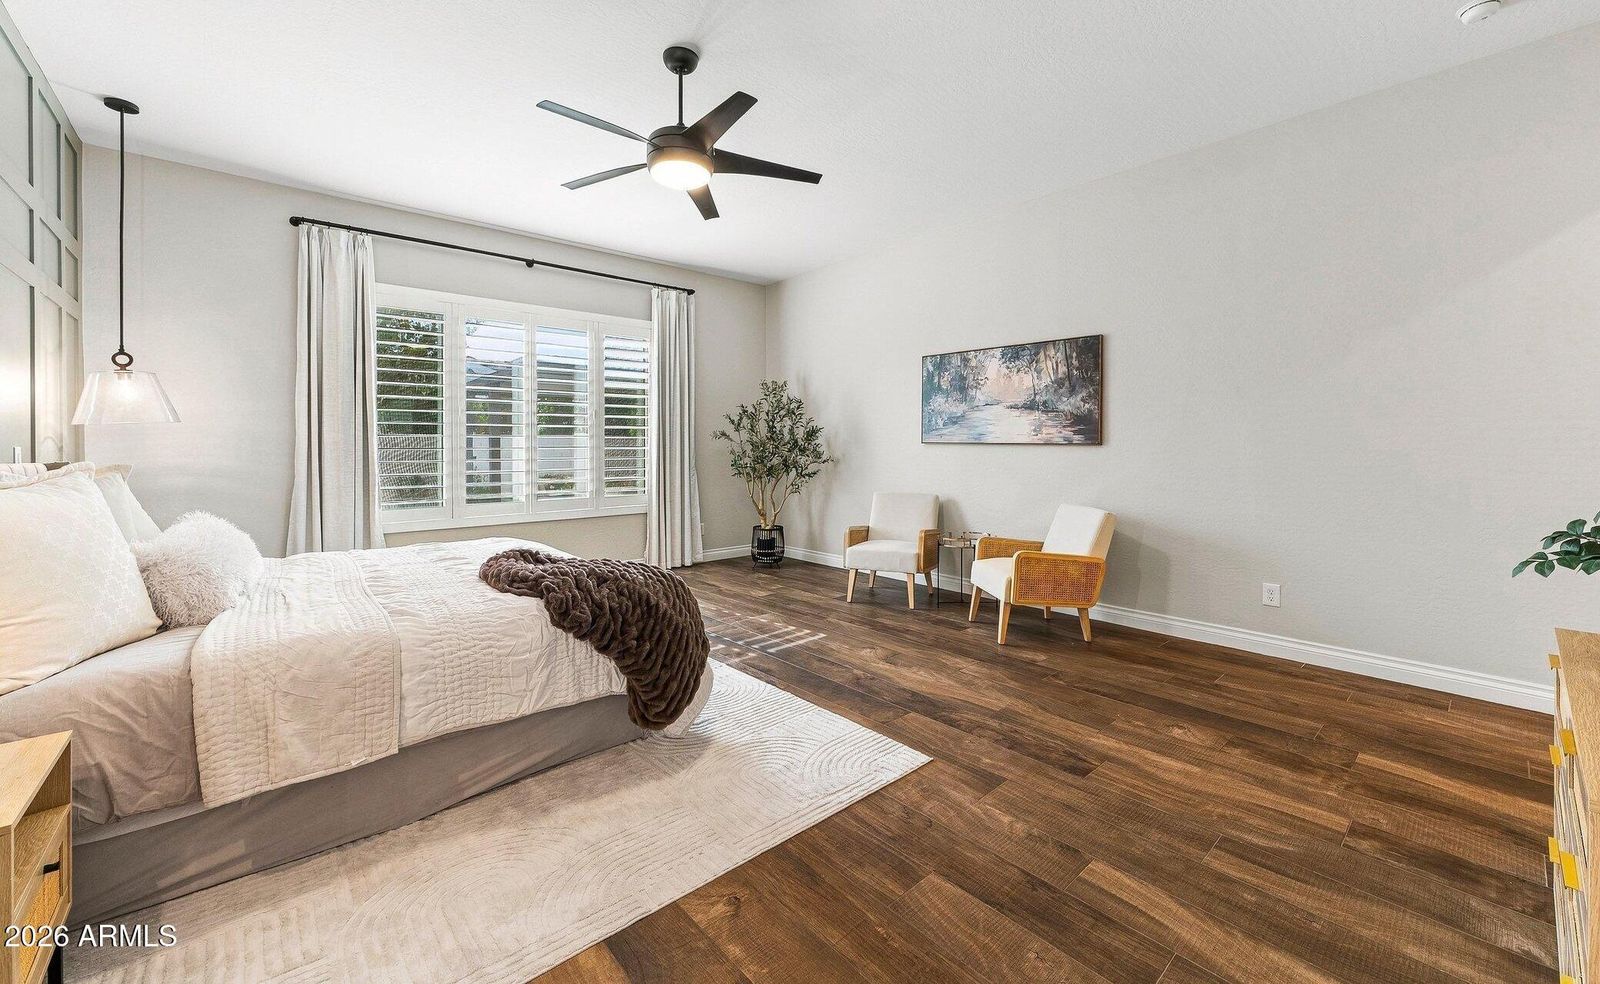
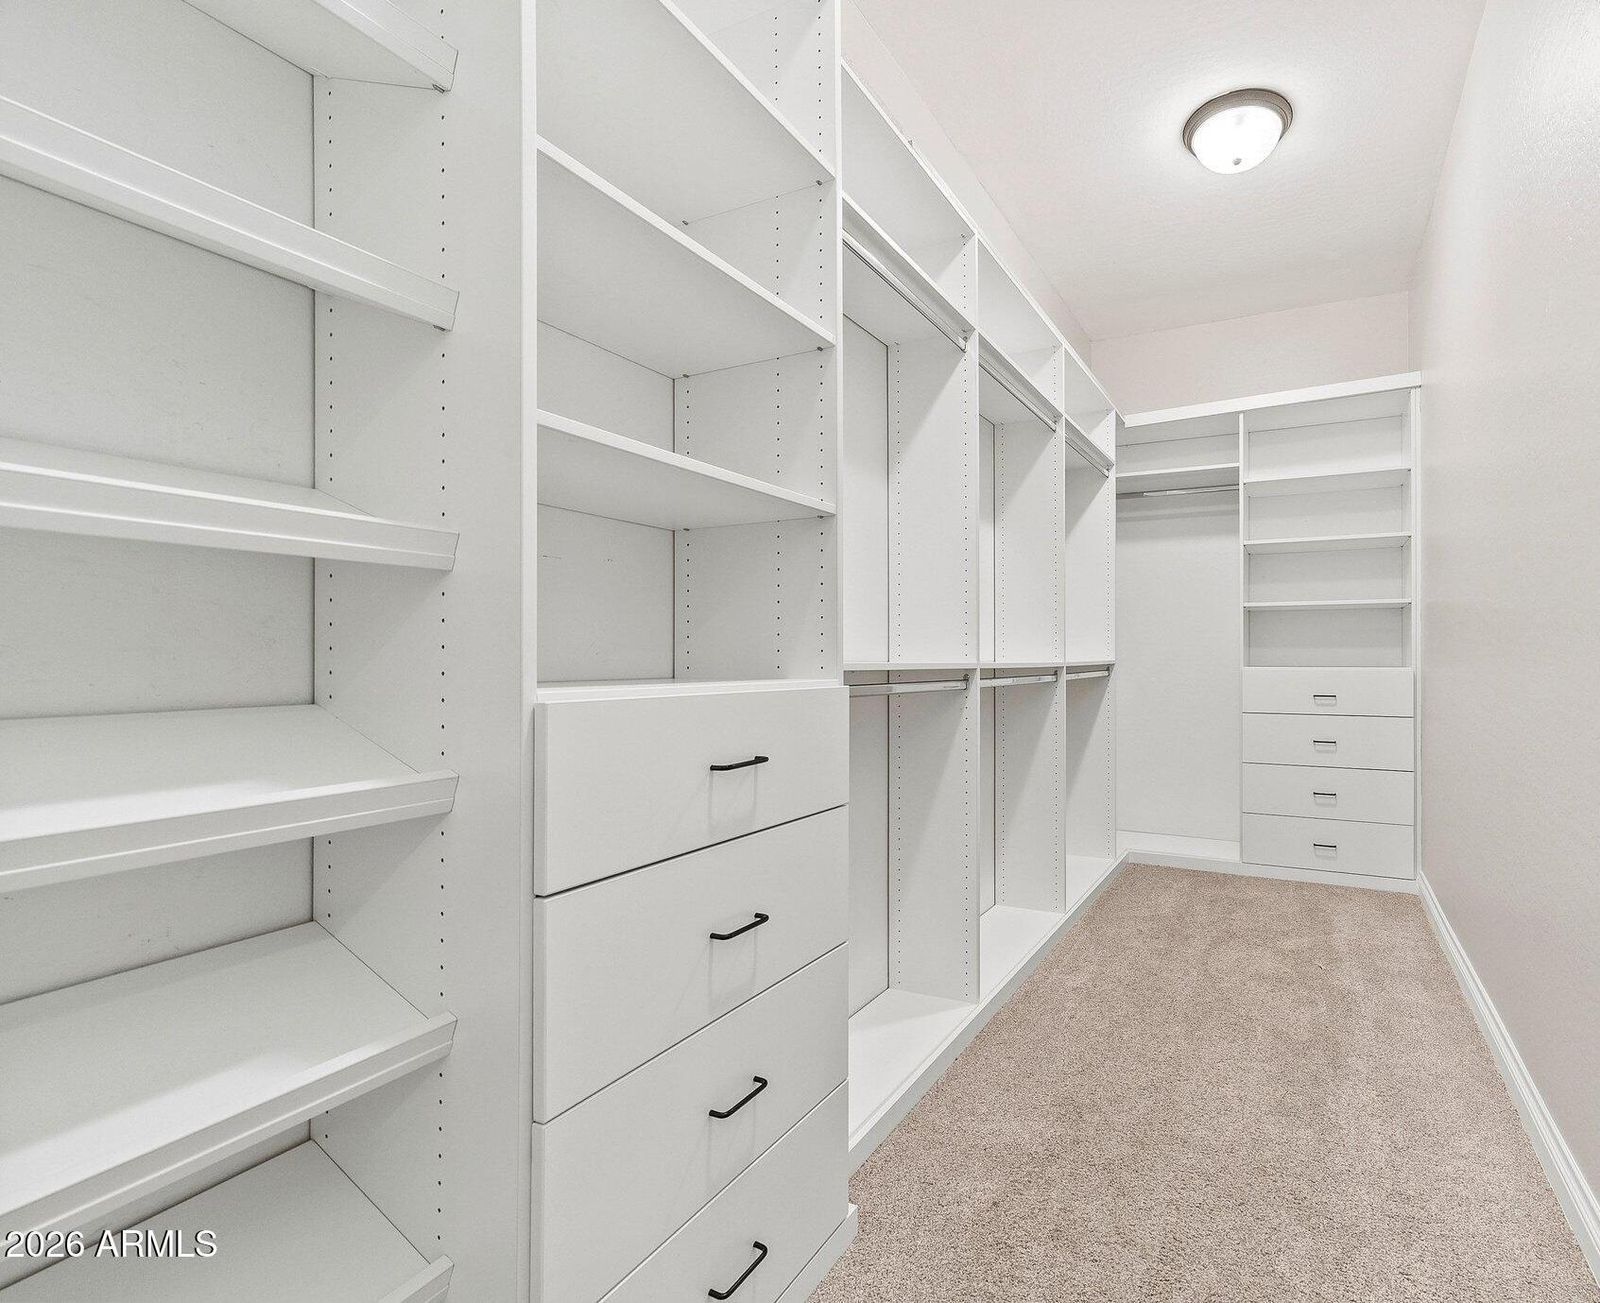
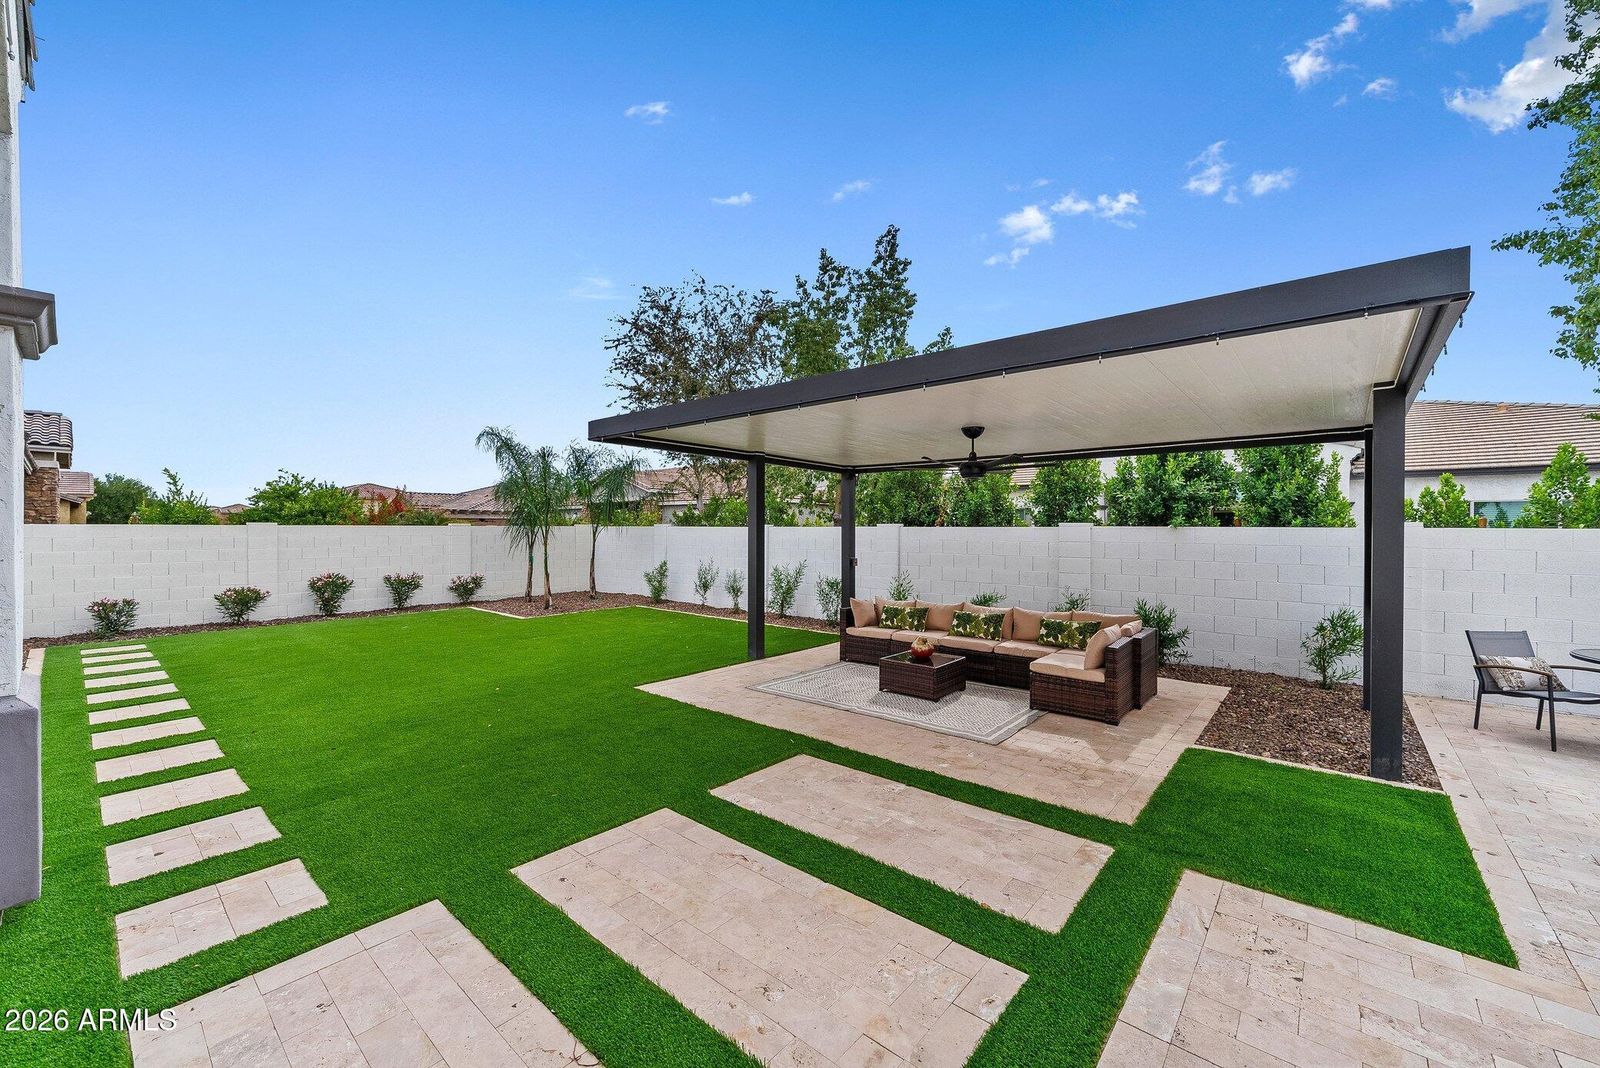
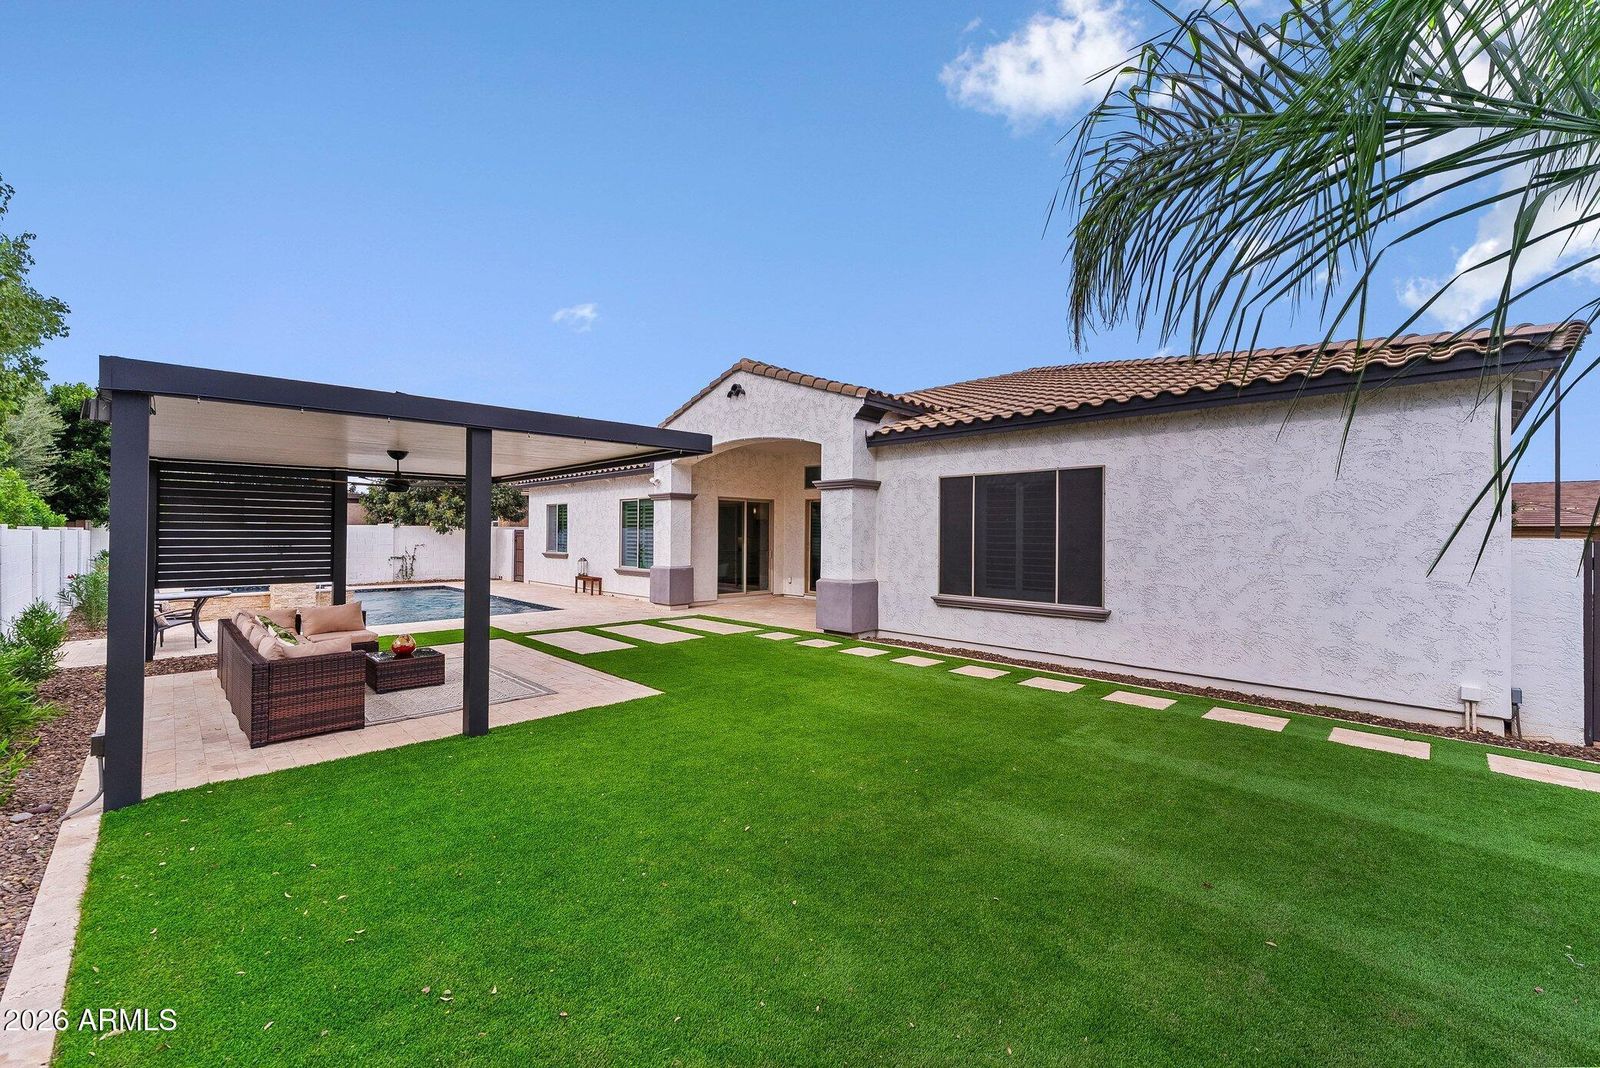
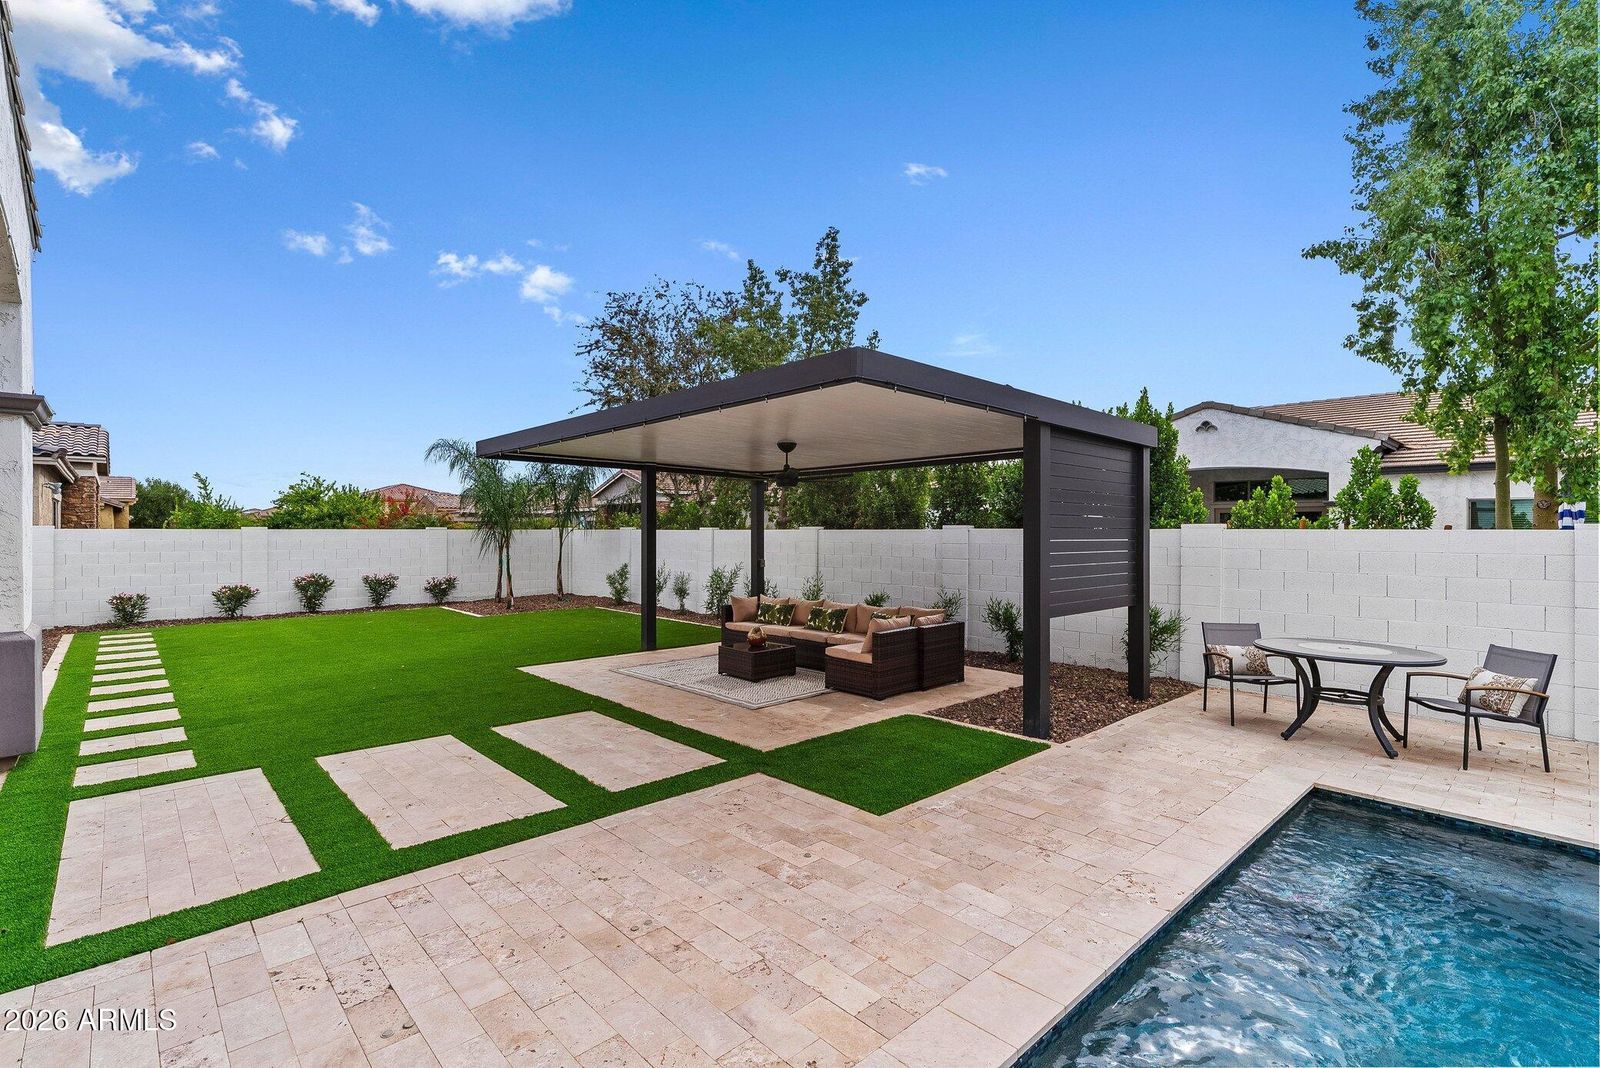
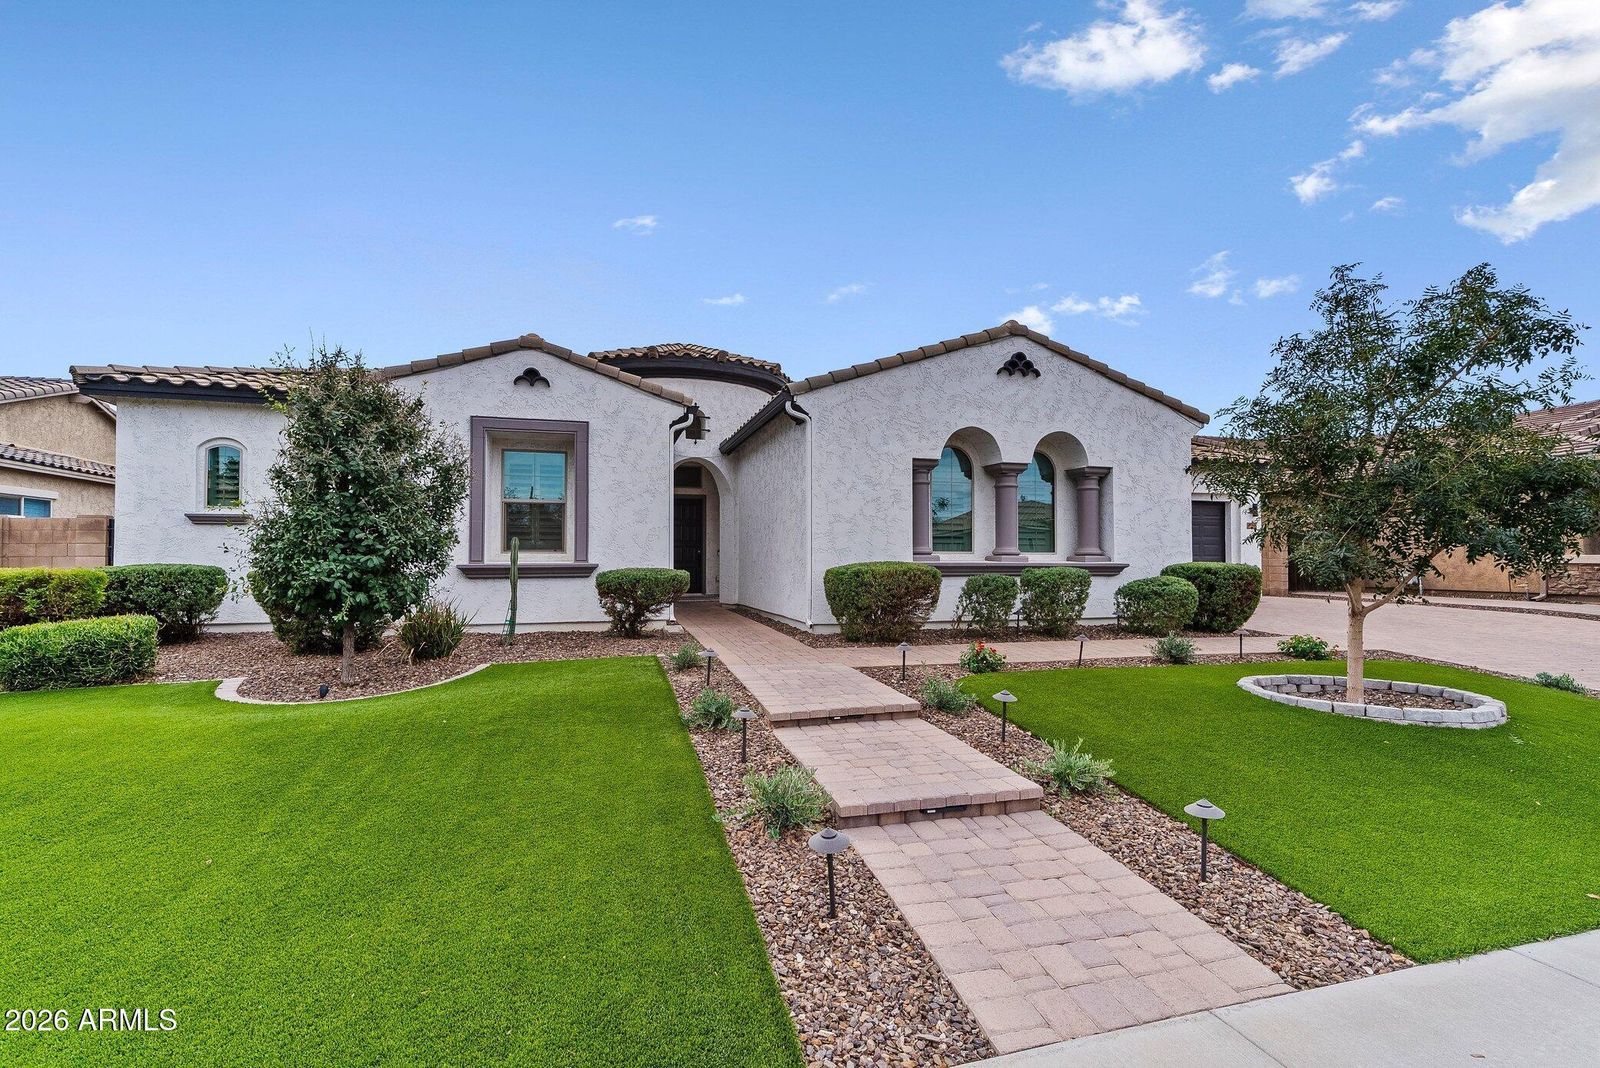
Front elevation at duskGreat room, media wall and fireplaceGreat room toward the entryGreat room and kitchen, wide viewKitchen with oversized islandKitchen, Wolf range and custom cabinetryCovered pergola and turf lawnPool and spa at duskCovered patio at duskRaised spa and pool water featuresBackyard, pergola and poolFront courtyard and entryFront courtyardFoyer and entry doorGreat room, media wallKitchen, island and pendantsKitchen, range wall from the islandKitchen island, reverse viewKitchen, sink and rangeWolf gas range, detailBreakfast nook and beverage refrigeratorBreakfast nook, second viewBreakfast nook, cabinetry and wine fridgeKitchen toward the breakfast nookScotsman ice maker, detailWalk-in pantryEnclosed office and denOffice and den, second viewBedroom with accent wallBedroomBath, tub and showerGarage, wide viewGarage with built-in cabinetsFoyer, wide viewFoyer and entryBedroomBedroom, second viewBath, double vanity and showerLaundry roomPrimary bedroomPrimary bedroom, reverse viewPrimary bedroom, bed detailPrimary bedroom, wide viewPrimary bath, soaking tub and double vanityPrimary bath, shower and vanityPrimary bath, soaking tubPrimary bath, vanity detailWalk-in closet, primary suiteBackyard, pergola and turf lawnBackyard and rear elevationBackyard, pergola and pool edgePergola seating areaFront elevation, aerial viewAerial view, pool and backyardAerial view, rear and poolAerial view, top downCommunity lake and neighborhood, aerialCommunity park and lake, aerialCommunity park, aerialGilbert Regional Park lake, aerialCommunity lake, aerialCommunity playground and park, aerialPickleball courts, aerialFront elevation and paver drivewayFront elevation and walkwayFront elevation at duskFront elevation at dusk, driveway viewBackyard and pergola at duskPool at duskBackyard, pergola and pool at duskPool and spa at dusk, close viewFront elevation at nightFront elevation
Listing photos, ARMLS MLS #7106481.
Inside and out
Completely remodeled and turnkey, with soaring 12 foot ceilings, upgraded trim work, designer lighting, and custom cabinetry throughout.
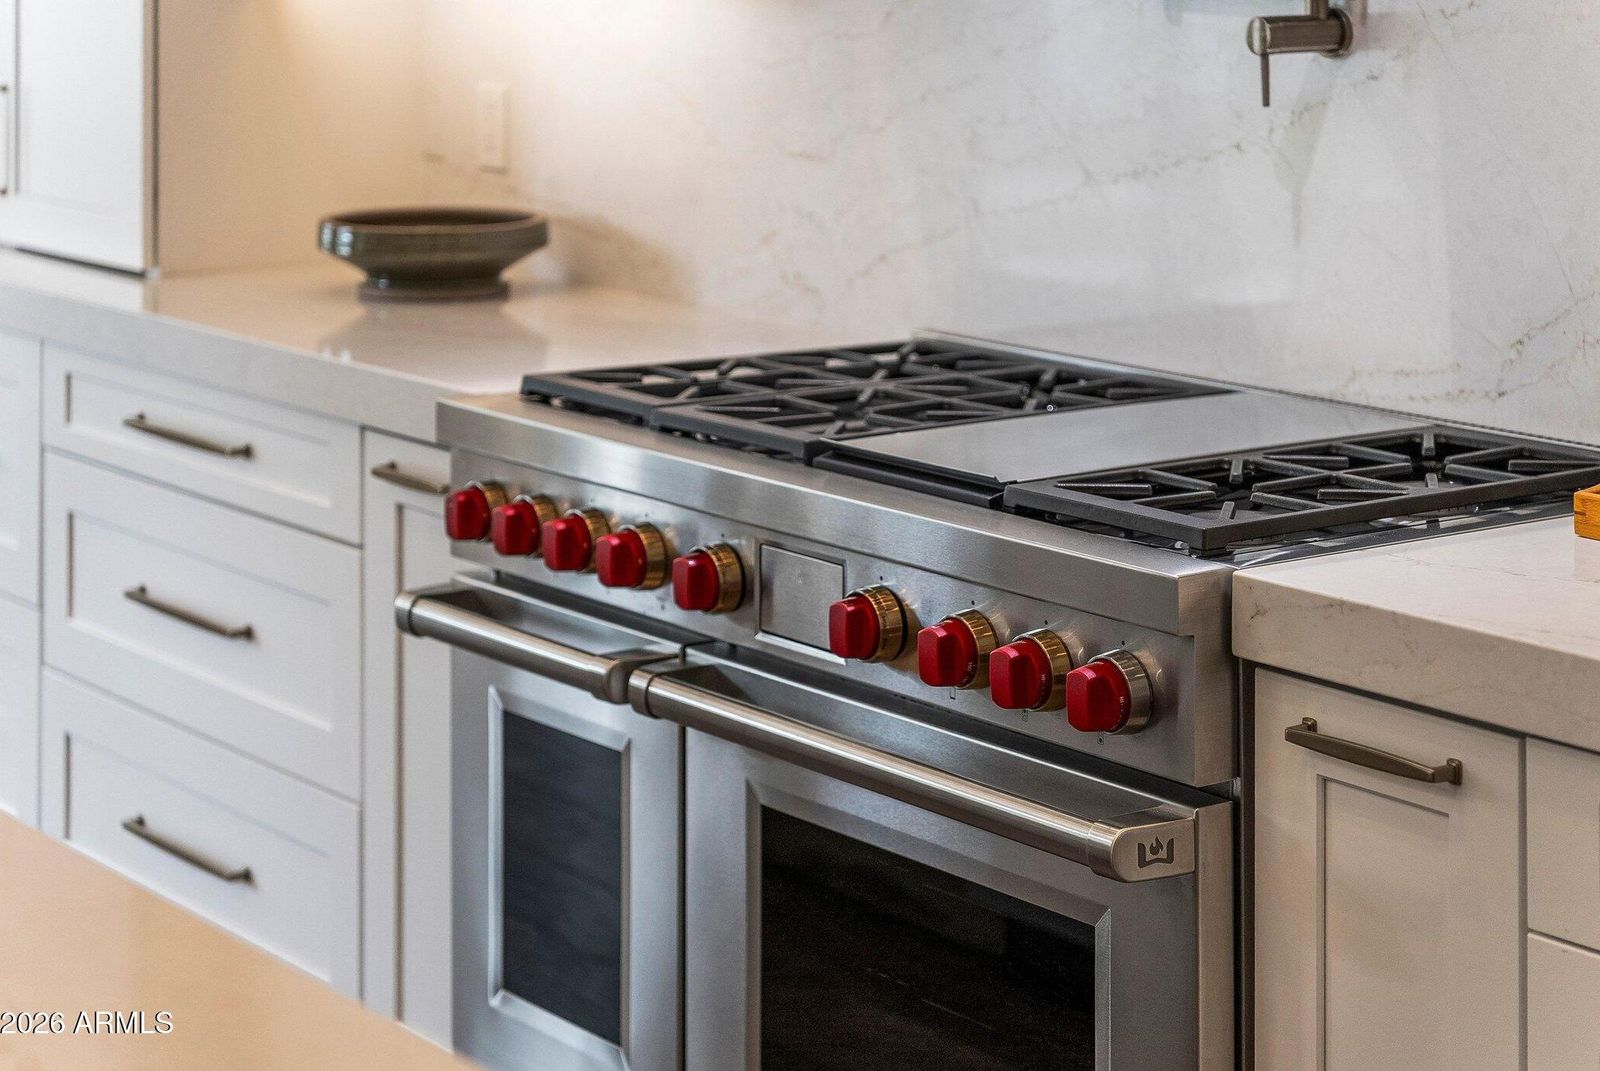
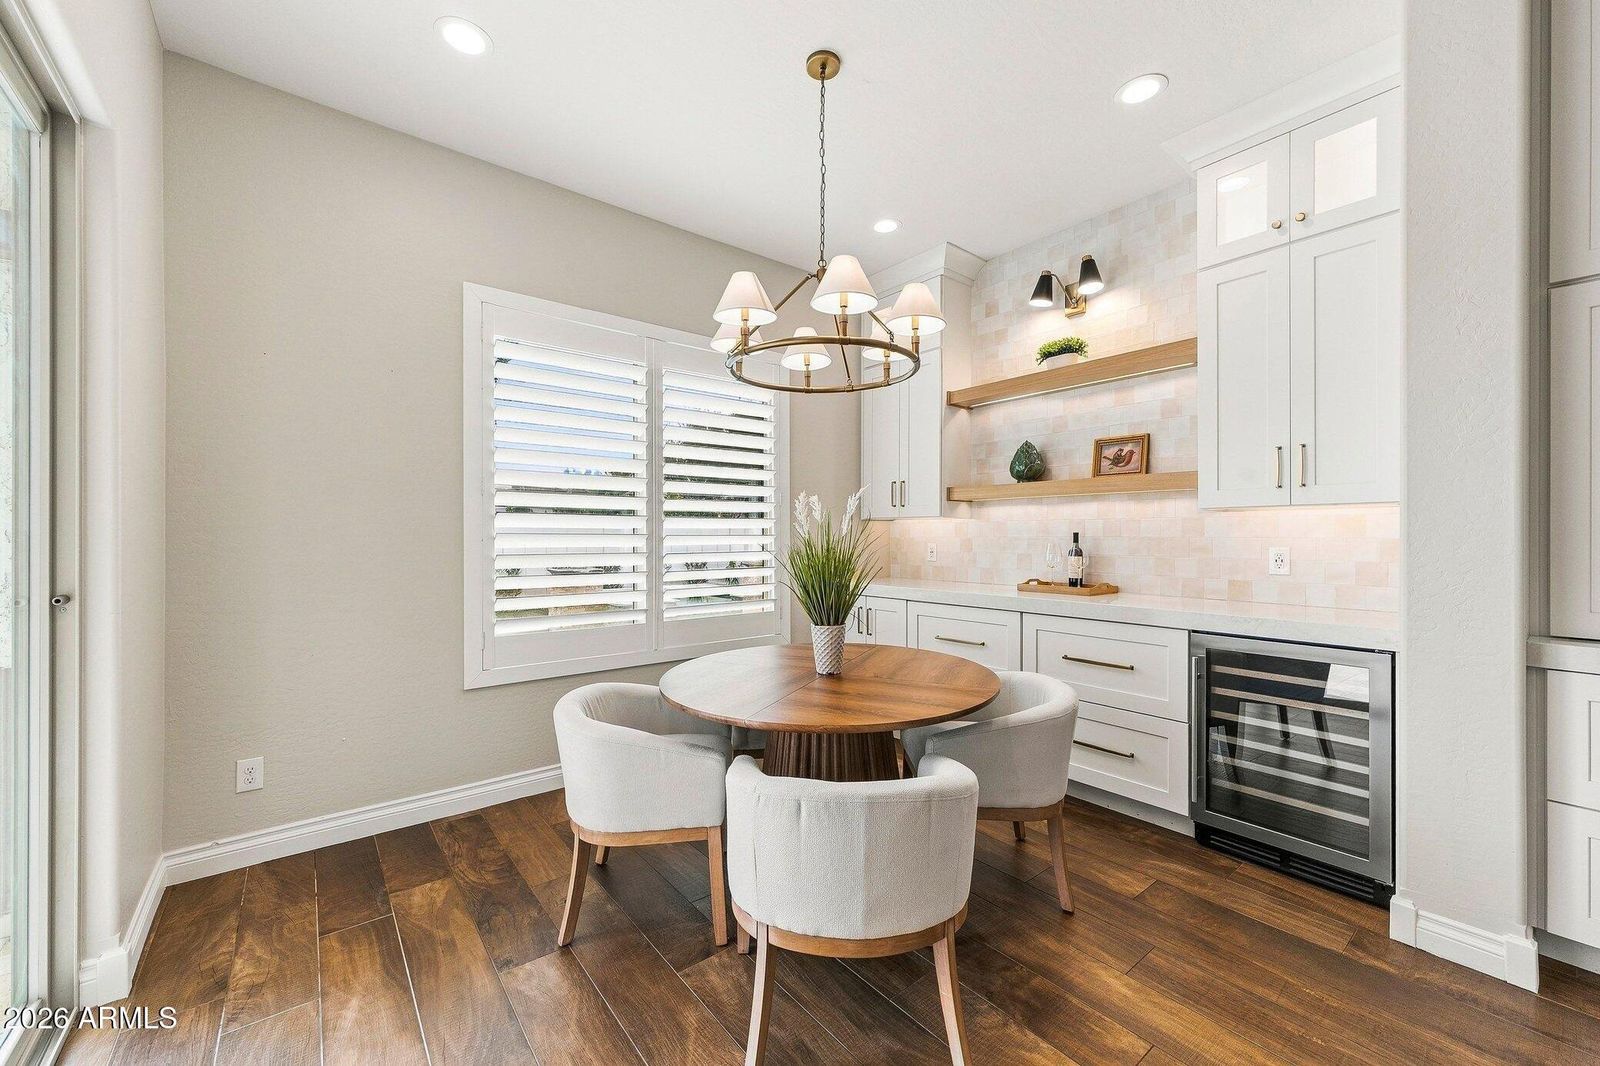
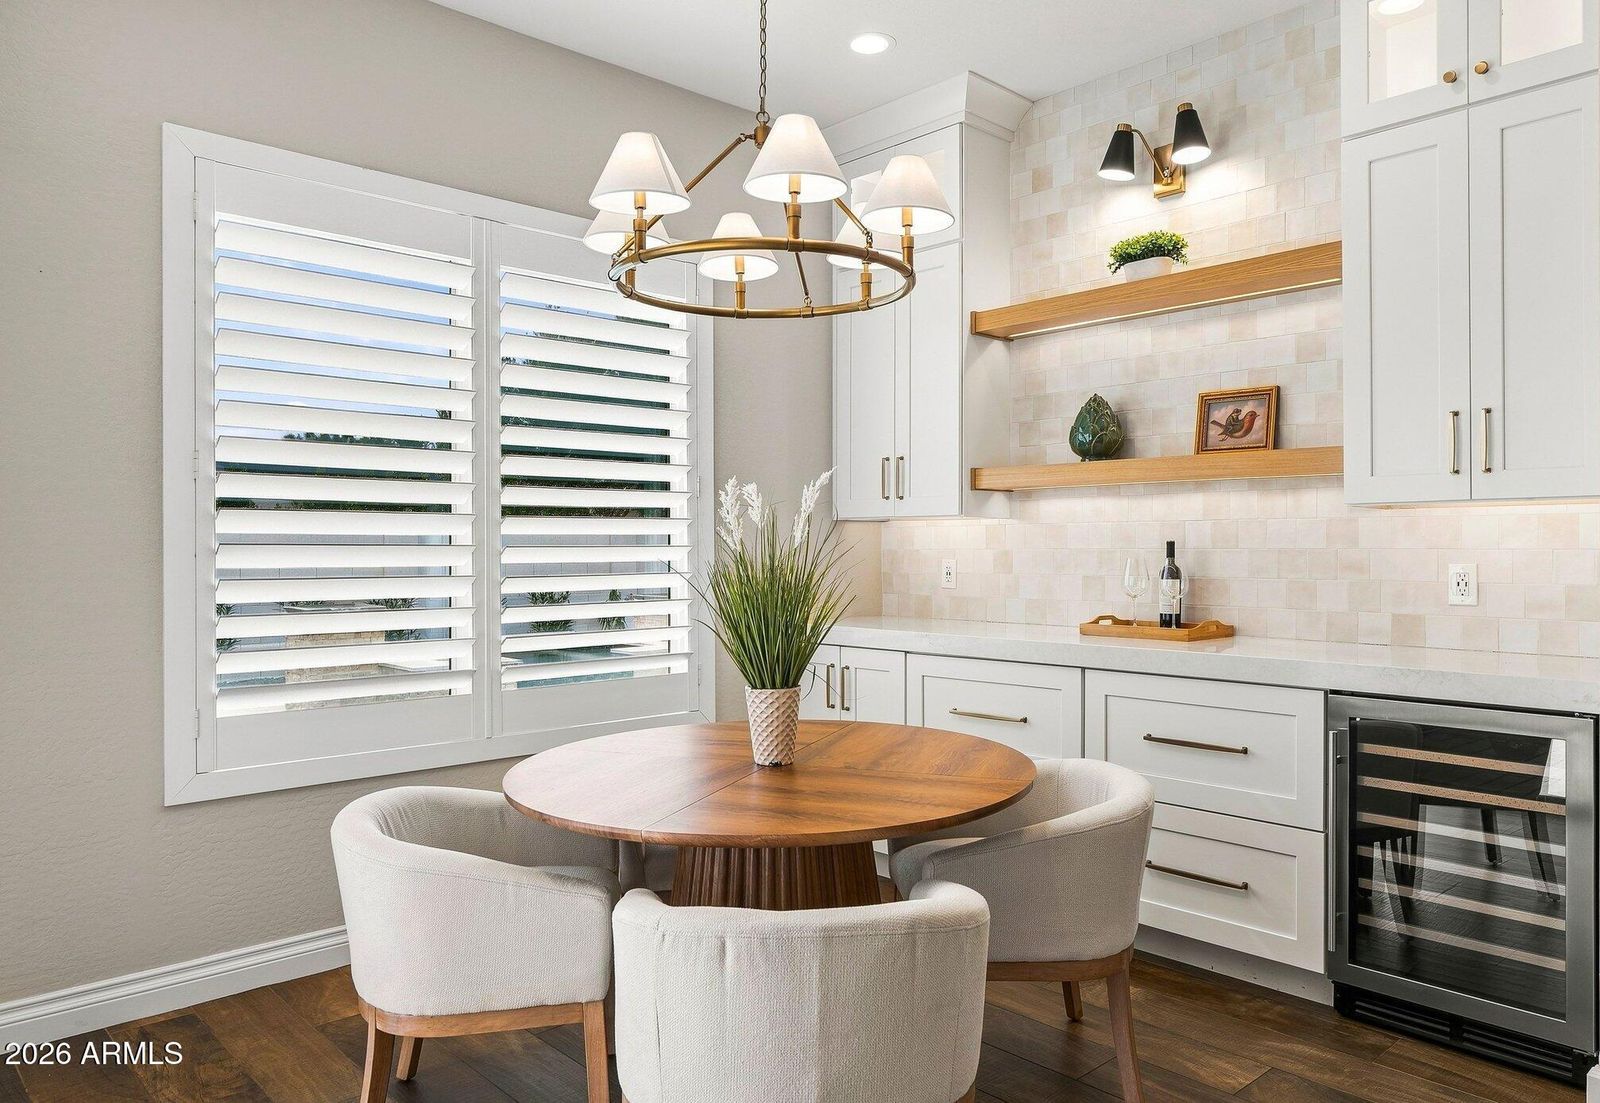
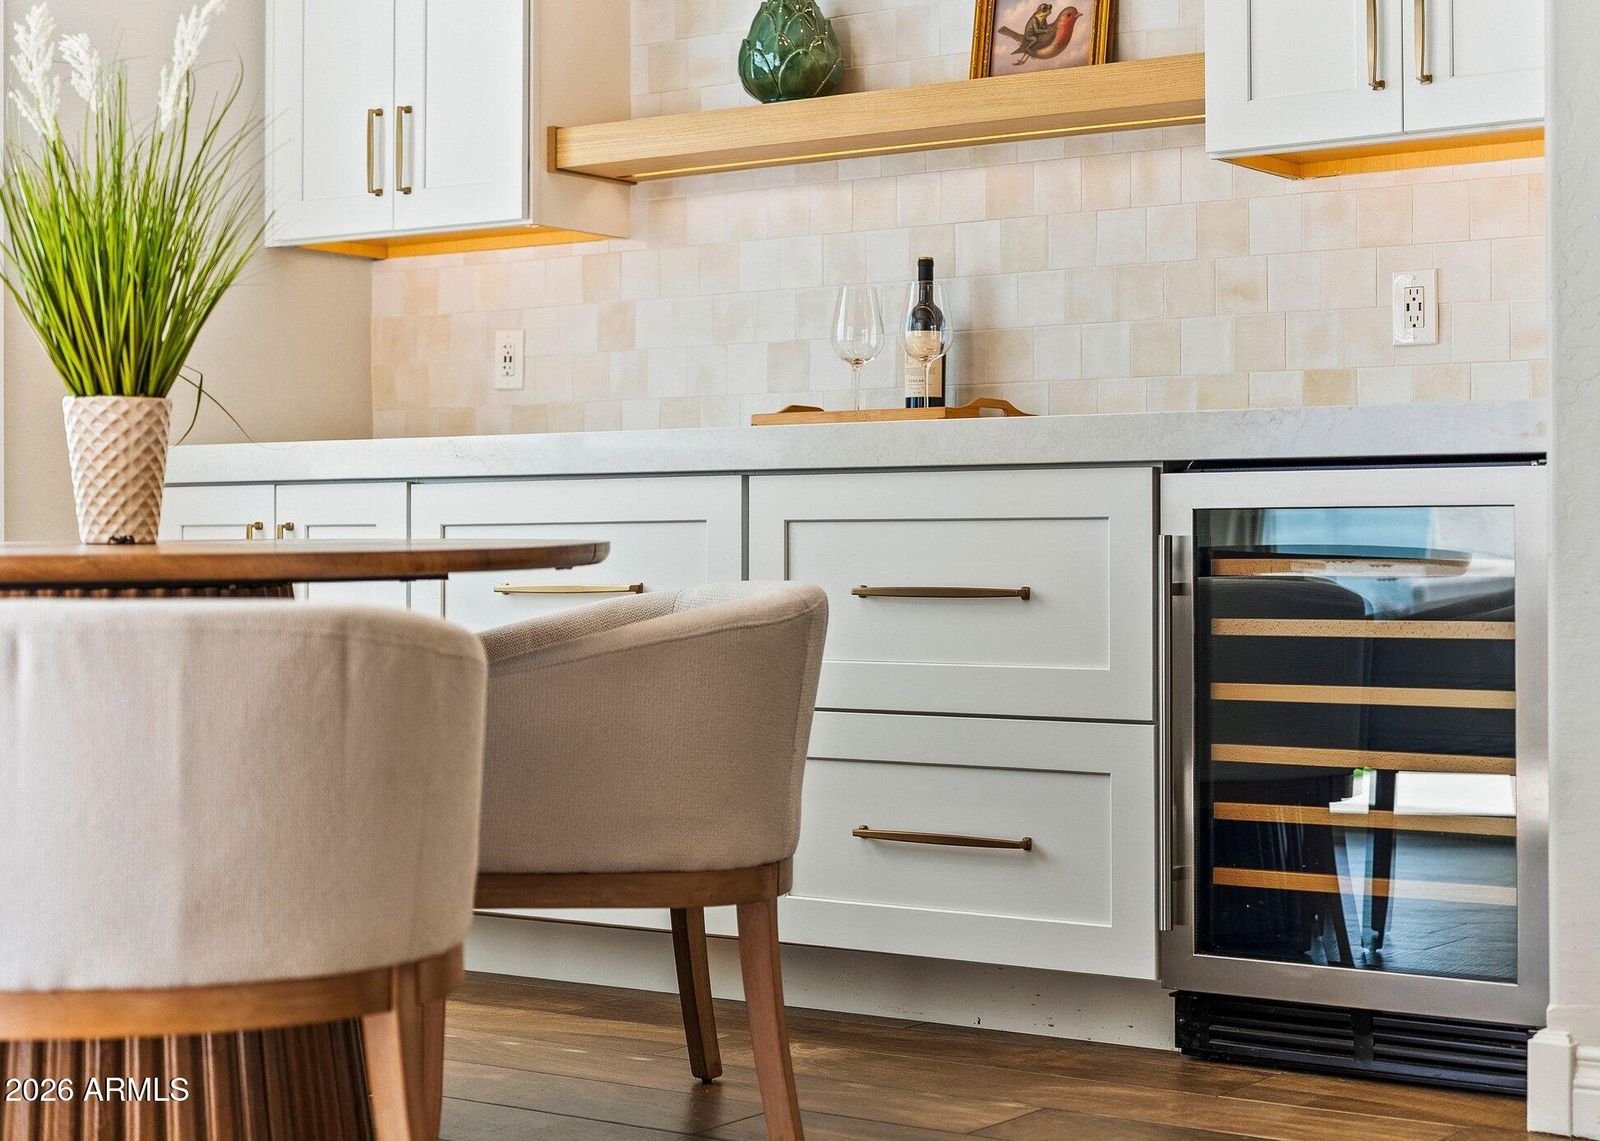
Chef inspired kitchen, a 48 inch Wolf gas range, a Scotsman sonic ice maker, floor to ceiling custom cabinetry, a reimagined walk-in pantry, and a breakfast nook with a beverage refrigerator.
Five bedrooms plus flex space, a large primary bedroom with two walk-in closets, four additional bedrooms, a dedicated flex room, and a fully enclosed office overlooking the great room.
Resort style backyard, brand new turf, travertine decking, a custom covered pergola, a commercial grade misting system, and a heated pool with a raised integrated jacuzzi and custom water spillovers.
The financing option
Offered at $1,300,000 in The Bridges at Gilbert, steps from Gilbert Regional Park and close to A+ rated Higley schools, restaurants, shopping, and freeway access.
A 2.00% seller concession ($26,000) written into the offer can fund a 2-1 buydown.
That buydown drops the buyer's payment by about $1,336 a month in year one. The math is in the next section.
Questions or a tour: call Jason LaFlesch at (602) 369-4663.
The featured financing: a 2-1 buydown
A 2% seller concession can go toward a 2-1 buydown, where the buyer's rate starts 2 points below the note rate in year one and 1 point below in year two. Move any slider and every number on this page recalculates. Defaults match the listing as it stands today, with an example buyer at 20% down and a 7.00% note rate, 30-year fixed, principal and interest only.
Loan at full price
$1,040,000
after 20% down
Full payment
$6,919
P&I at the note rate
Buydown escrow cost
$24,240
Funded by the concession, $1,760 to spare
Seller net · both options
$1,274,000
Price minus the concession
The 2-1 buydown escrow costs $24,240 at these settings, so the $26,000 concession funds it in full and leaves about $1,760 for the buyer's other closing costs.
Two ways to spend a $26,000 concession
Written into an offer either way, the seller's dollars are the same and the seller nets the same. The difference is entirely in what the buyer feels month to month.
Option A · Price reduction
Take it off the price
The concession comes off the price instead: $1,300,000 becomes $1,274,000. The buyer's loan shrinks by $20,800, so the payment shrinks a little, forever.
$6,781/ mo P&I
Saves the buyer $138/mo
Price after reduction$1,274,000
Seller dollars used$26,000
Seller net$1,274,000
Buyer saves over 2 years$3,321
Cash to close$5,200 less down payment
Option B · 2-1 Buydown
Keep the price, buy the rate down
Price stays at $1,300,000. The same seller dollars fund a 2-1 buydown escrow: the buyer's rate starts 2 points under the note rate, steps up 1 point in year two, then settles at the note rate.
$5,583/ mo P&I in year 1
Saves the buyer $1,336/mo in year 1
Year 1 · 5.00%
$5,583
save $1,336/mo
Year 2 · 6.00%
$6,235
save $684/mo
Year 3+ · 7.00%
$6,919
full note payment
Buydown escrow cost$24,240
Concession left overAbout $1,760
Seller dollars used$26,000
Seller net$1,274,000
Buyer saves over 2 years$24,240
The takeaway: the seller nets $1,274,000 either way. As a price cut, the $26,000 lowers the buyer's payment by $138 a month. As a buydown, the same dollars lower it by $1,336 a month in year one, about 9.7× as much. Matching that year-one payment with price alone would take a reduction of roughly $251,051.
At $1,300,000no buydown
$6,919
Price cut to $1,274,000Option A
$6,781
Buydown, year 2Option B · 6.00%
$6,235
Buydown, year 1Option B · 5.00%
$5,583
Monthly principal and interest only. Taxes, insurance, HOA, and mortgage insurance are not shown; a price reduction trims them slightly, a buydown does not change them.
Why the buydown works for this home
What buyers actually feel
Buyers shop the monthly payment, not the price. A $5,583 first-year payment reads very differently in a listing conversation than $6,919, and it is the number a payment-sensitive buyer feels month to month.
The relief lands when moving costs hit. The lowest payment comes in the first year, when the buyer is also paying for the move, furniture, and settling in.
The seller keeps their price. Holding the full price protects the appraisal and the neighborhood comp, instead of resetting both lower with a cut.
It gives agents something new to call about. Every agent with a buyer watching this home can now re-contact them with a payment story, not the same listing twice.
The honest trade-offs
The buydown savings are front-loaded. The payment steps up in year two and reaches the full note payment in year three. Buyers should be comfortable at $6,919, not just at $5,583.
Buyers qualify at the full note rate. The buydown lowers the early payments, not the qualifying payment, so it helps cash flow rather than borrowing power.
A price cut lasts forever. It also trims the down payment and slightly lowers taxes and insurance. For a buyer who plans to stay put for decades and never refinance, that permanence has real value.
It is an option, not an either-or. The concession can be split, part buydown and part closing costs, and any leftover after the buydown escrow still goes to the buyer's other closing costs.
How the buydown works in an offer
1
Offer at $1,300,000 with a 2.00% seller concession
Full list price, with the concession written into the contract as part of the offer.
2
Direct the concession to the buydown
The offer specifies that the seller concession funds a 2-1 buydown escrow with the buyer's lender, with any remainder going to the buyer's other closing costs.
3
The lender holds and applies it
At closing the buydown escrow (about $24,240 at the settings above) is funded from the concession and tops up the buyer's payment each month for the first two years. The seller nets the same as a price cut, and nothing changes for them after closing.